

|
시장보고서
상품코드
2122752
LED 드라이버 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)LED Driver - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
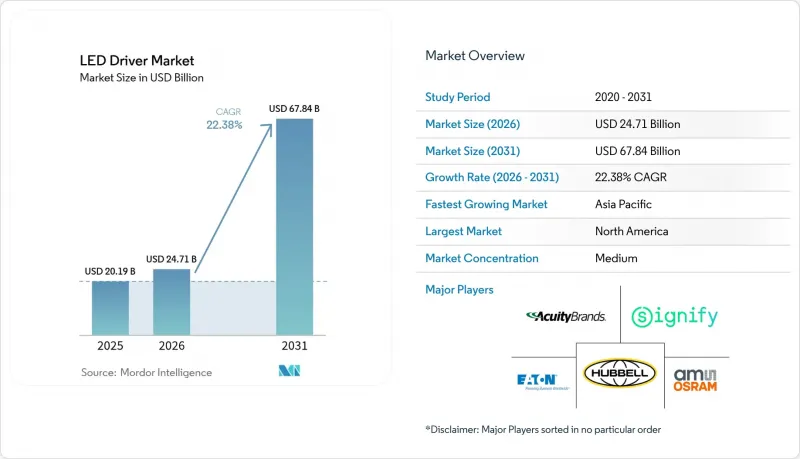
에 의하면, 2026년 LED 드라이버 시장 규모는 247억 1,000만 달러로 추정되고 2025년 201억 9,000만 달러에서 확대해, 2031년에는 678억 4,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 22.38%로 성장할 것으로 전망됩니다.

본 보고서는 제품 유형(정전류 LED 드라이버, 기타), 제어 기능(유선, 무선), 출력(25W 이하, 25-65W, 기타), 폼 팩터(외부 독립형, 통합형·온보드형, 기타), 최종 용도(주거용, 상업·사무실,소매 및 호스피탈리티, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 LED 드라이버 시장 동향 및 인사이트
보조금을 통한 LED 교체 프로그램이 시장 성장을 주도
인도의 ‘UJALA’ 이니셔티브는 고효율 램프의 대규모 보급을 통해 전력 수요를 20GW 줄이고, 연간 8,000만 톤의 CO2 배출을 방지할 수 있음을 보여줍니다. 기존의 할인 제도와 달리, 이 프로그램 시장 기반 접근 방식은 공급업체의 이익률을 유지하면서 에너지 모니터링 기능을 갖춘 첨단 드라이버를 중시하는 지속적인 제품 업그레이드를 촉진하고 있습니다. 중국, 말레이시아, 유럽연합(EU)의 유사한 정책은 전구 교체에서 조명 기구 전체 교체로 전환되고 있으며, 이로 인해 무선 제어를 지원하고 역률 0.9 이상을 목표로 하며 IEC 플리커 기준을 충족하는 드라이버에 대한 수요가 촉발되고 있습니다. 초기 LED 도입 물결이 2015년경 본격화됨에 따라, 58억 대 규모의 2차 교체 주기가 2025년부터 2028년에 걸쳐 정점에 도달하기 시작할 것입니다. 이러한 프로그램들은 예측 기간 동안 예측 가능한 대량 조달 파이프라인을 확보함으로써 LED 드라이버 시장에 전반적인 활력을 불어넣고 있습니다.
GaN-on-Si 드라이버 IC의 급격한 가격 하락이 보급을 뒷받침
Texas Instruments가 6인치에서 8인치 GaN 웨이퍼로 전환함에 따라, 다이 비용을 절감하면서도 수율 안정성을 향상시키고, 전력 변환 효율을 92% 이상으로 높이며, 열 예산을 축소하고 있습니다. 인피니언(Infineon)의 300mm 파일럿 라인은 2025년에 실리콘과 동등한 가격 수준에 도달했으며, 소매용 트럭 조명 및 가전제품 조명과 같은 주류 시장 진출을 가능하게 할 것입니다. GaN의 높은 스위칭 주파수 덕분에 자기 부품의 크기를 최대 40%까지 줄일 수 있어 조명 기구의 슬림화가 가능할 뿐만 아니라, 칩 온 보드(COB) 모듈에 있어 중요한 요소인 케이스 온도 저하도 실현합니다. 자동차용 헤드램프 시스템에서는 GaN의 높은 접합 온도 내성이 활용되어 전기차(EV)의 어댑티브 빔 아키텍처를 지원하고 있습니다. 이러한 경제성은 집적화의 선순환을 뒷받침하고 있습니다. 생산량이 증가함에 따라 비용 절감이 더욱 진전되어 LED 드라이버 시장을 더욱 확대해 나갈 것입니다.
실리콘 공급 제약이 지속되면서 드라이버 IC 생산에 병목 현상이 발생하고 있다.
Wolfspeed의 자금 사정이 악화되면서 고출력 조명 및 전기차(EV) 용도의 실리콘 카바이드(SiC) 웨이퍼 공급이 위협받고 있습니다. 파운드리 업체들은 첨단 3nm 로직을 우선시하고 있어, LED 드라이버에 사용되는 혼합 신호 공정용 16-90nm 공정의 생산 능력은 부족합니다. 일반적인 MOSFET의 리드타임은 40주를 초과하고, 특수한 PMIC의 경우 1년 이상에 달하기 때문에 설계 재검토나 여러 공급업체로부터의 조달 전략을 강구할 수밖에 없습니다. 이러한 공급 제약은 가격 변동을 초래하여 중견 OEM의 이익률을 압박하고 있습니다. 그 결과, 입찰 상한액이 고정된 실외 조명 프로젝트와 같은 부문에서 단기적인 출하 전망이 둔화되고 있습니다. 동남아시아의 생산 능력 확충이 본격화될 때까지 실리콘 공급 부족은 LED 드라이버 시장에 계속해서 뚜렷한 걸림돌이 될 것으로 보입니다.
부문별 분석
정전류 디바이스는 고루멘 용도에서 수십 년에 걸친 설계 실적을 바탕으로 2025년에는 LED 드라이버 시장 점유율의 60.55%를 차지했습니다. 그러나 정전력 드라이버는 최대 92%의 변환 효율을 실현하고, 재설계 없이 가변 전압의 LED 부하에 대응할 수 있기 때문에 2026년부터 2031년까지 연평균 성장률(CAGR) 22.96%가 예상됩니다. 자동차용 프론트 조명 틈새 시장에서 인피니언(Infineon)의 ‘Litix Power Flex’ 시리즈는 성능이 비약적으로 향상되었습니다. SPI 제어를 통한 조광 기능과 멀티 스트링 보호 기능 덕분에 발열 증가 없이 기능이 확대되었습니다.
어댑티브 라이팅의 보급이 이러한 전환을 뒷받침하고 있습니다. 건축물 파사드, 스포츠 경기장, 조광이 가능한 사무실용 조명 기구에서는 전류가 다이오드의 허용 범위 내에 머무르면서 출력을 동적으로 조정할 수 있다는 점이 큰 장점이 됩니다. 이러한 범용성 덕분에 조명 기구 제조업체는 SKU 증가를 억제할 수 있으며, 현장에서의 업그레이드도 용이해집니다. 무선 프로토콜이 보급되는 가운데, 펌웨어를 통해 선택 가능한 전력 특성 곡선 덕분에 정전력 설계는 진화를 거듭하는 LED 드라이버 시장에서 선호되는 플랫폼이 되고 있습니다.
DALI 및 0-10V를 필두로 하는 유선 시스템은 기존 구조물에 제어용 케이블이 매립되어 있기 때문에 2025년 LED 드라이버 시장 규모의 64.82%를 차지했습니다. 그러나 무선 기능은 보급 곡선의 가파른 상승 단계에 접어들고 있으며, 2031년 연평균 성장률(CAGR)은 23.62%로 전망됩니다. 레그란(Legrand)사의 Matter 인증을 받은 월박스형 조광기는 앱 기반 초기 설정에 대한 소비자의 높은 관심을 보여주고 있습니다.
총비용 관점에서 볼 때, 제어 배선을 제거함으로써 상업시설의 개보수 예산에서 인건비를 15-25% 절감할 수 있으며, 대부분의 경우 ROI 측면에서 LED와 제어 시스템의 조합이 유리하게 작용합니다. Thread의 IPv6 기반은 빌딩 관리 시스템과의 통합을 용이하게 하며, BLE 메쉬는 비연속 조명의 점검에 있어 저전력 폴백 수단을 제공합니다. 무선 펌웨어 업데이트가 주류가 된 현재, 무선 드라이버는 향후 기능에 대응함으로써 작동 수명을 연장합니다. 이러한 장점 덕분에 무선 기술은 LED 드라이버 시장의 핵심 축으로서 입지를 공고히 하고 있습니다.
지역별 분석
2025년 북미의 매출 점유율 31.96%는 83-195lm/W라는 높은 기준을 부과하는 엄격한 램프 효율 규제에 기인하며, 이로 인해 사양 결정자들은 고효율 드라이버를 선택하도록 유도되었습니다. 코카콜라 컨솔리데이티드(Coca-Cola Consolidated)의 6개 시설 업그레이드와 같은 기업의 개보수 사례에서는 연간 9만 7,063달러를 절감하여, 투자 회수 기간이 짧다는 주장을 뒷받침하고 있습니다. ‘CHIPS법’은 국내 반도체 제조 공장에 2,000억 달러를 배정하고 있으며, 이를 통해 아날로그 및 파워 부품 공급 체제의 탄력성이 향상되고 있습니다. 캐나다와 멕시코는 통합된 공급망을 활용하여 기술 기준과 인증 검사소를 공유함으로써 국경을 넘는 출하를 원활하게 하고 있습니다.
아시아태평양은 가장 빠른 구조적 성장을 보이고 있으며, 2031년 연평균 성장률(CAGR)은 23.51%로 예측됩니다. 중국의 탄탄한 제조거점 덕분에 부품 원가(BOM)가 대폭 절감되었으며, 지방 정부의 스마트 시티 보조금이 NB-IoT 및 LoRa 게이트웨이를 탑재한 드라이버에 대한 지역 수요를 자극하고 있습니다. 인도에서는 사상 최대 규모의 ‘UJALA’ 프로그램을 통해 수명이 다한 램프 재고가 보충되면서, 조명 기구 업그레이드 주기의 제2파가 본격화되고 있습니다. 일본, 한국, 대만에서는 EV 주도의 헤드램프 기술 혁신을 수출 가능한 어댑티브 빔용 드라이버로 확대되고 있습니다. 아세안 시장에서는 공급망의 다각화가 진행되고 있으며, 베트남은 북미 브랜드의 최종 마감 및 조립 거점으로 부상하고 있습니다.
유럽에서는 2030년까지 연간 96TWh의 전력 절감을 목표로 하는 ‘에코디자인 2019/2020’을 통해 그 기세가 유지되고 있습니다. 독일 KfW 은행의 보조금 제도에서는 지능형 조명 도입에 우대 금리를 연계하고 있어, 물류 창고에서의 드라이버 교체가 가속화되고 있습니다. 동유럽의 개보수 프로젝트는 유럽연합(EU)의 결속 기금 지원을 받고 있는 반면, 영국의 건축 규정 ‘파트 L’에는 오픈 프로토콜 통신이 가능한 드라이버를 권장하는 동적 조명에 관한 지침이 포함되어 있습니다. 중동 및 아프리카에서는 ‘비전 2030’ 프로그램에 힘입어 전 세계 LED 드라이버 시장이 확대되고 있으며, 그 대표적인 예로 현지 조립 사업에 힘입은 사우디아라비아의 LED 도입 전망(CAGR 9.6%)을 들 수 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
제8장 투자 분석
KTH 26.09.08According to Mordor Intelligence, LED driver market size in 2026 is estimated at USD 24.71 billion, growing from 2025 value of USD 20.19 billion with 2031 projections showing USD 67.84 billion, growing at 22.38% CAGR over 2026-2031.
This report is Segmented by Product Type (Constant Current LED Drivers, and More), Control Feature (Wired, Wireless), Power Output (Less Than25W, 25-65W, and More), Form Factor (External Stand-Alone, Integrated/On-Board, and More), End-Use Application (Residential, Commercial and Office, Retail and Hospitality, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global LED Driver Market Trends and Insights
Subsidy-fuelled LED Retrofit Programs Drive Market Acceleration
India's UJALA initiative illustrates how large-scale distribution of efficient lamps can slash electricity demand by 20 GW and avoid 80 million t of CO2 annually. Unlike earlier discount schemes, the program's market-based approach sustained vendor margins, encouraging continual product upgrades that now emphasize advanced drivers with energy-monitoring functions. Similar schemes in China, Malaysia and the European Union are moving from bulb replacements toward holistic luminaire swaps, triggering demand for drivers that support wireless controls, target power factors above 0.9 and meet IEC flicker criteria. Because early LED waves entered service around 2015, a secondary replacement cycle of 5.8 billion units begins peaking between 2025 and 2028. These programs collectively add momentum to the LED driver market by ensuring predictable, large-volume procurement pipelines over the forecast period.
Rapid Price Declines in GaN-on-Si Driver ICs Enable Mass Adoption
Texas Instruments' migration from 6-inch to 8-inch GaN wafers cuts die cost while improving yield consistency, pushing power-conversion efficiency beyond 92% and shrinking thermal budgets.Infineon's 300 mm pilot line is expected to reach silicon-parity pricing in 2025, opening mainstream channels such as retail track lighting and appliance illumination. GaN's higher switching frequencies reduce magnetics size by up to 40%, enabling slimmer luminaire profiles and lowering enclosure temperatures, a critical factor for chip-on-board modules. Automotive headlamp systems benefit from GaN's resilience at high junction temperatures, supporting adaptive-beam architectures in electric vehicles. These economics support a virtuous cycle of integration: as volumes climb, cost drops deepen, broadening the LED driver market even further.
Persistent Silicon Supply Constraints Create Bottlenecks in Driver IC Production
Wolfspeed's liquidity pressures threaten silicon-carbide wafer availability for high-power lighting and EV applications. Foundries prioritize advanced 3-nm logic, leaving 16-90 nm capacity thin for the mixed-signal processes used in LED drivers. Lead times exceed 40 weeks for common MOSFETs; speciality PMICs stretch beyond a year, forcing design pivots and multi-sourcing strategies. The constraint drives price volatility that squeezes mid-tier OEM margins, dampening near-term shipment potential in segments such as outdoor lighting projects with firm bid ceilings. Until capacity additions in Southeast Asia come online, silicon shortfalls remain a measurable drag on the LED driver market.
Other drivers and restraints analyzed in the detailed report include:
- Smart-Lighting Mandates in New-Build Codes Create Compliance-Driven Demand
- Mainstream Adoption of Matter/Thread Wireless Controls Standardizes Connectivity
- Limited Interoperability Across Legacy Wired Protocols Fragments Market Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Constant current devices held 60.55% LED driver market share in 2025, driven by decades of design familiarity in high-lumen applications. However, constant power drivers deliver up to 92% conversion efficiency and accommodate variable-voltage LED loads without redesign, supporting a projected 22.96% CAGR between 2026 and 2031. In the automotive front-lighting niche, Infineon's Litix Power Flex series illustrates the performance jump: SPI-controlled dimming and multi-string protection broaden functionality without thermal penalty.
The rise of adaptive lighting scenarios reinforces the shift. Architectural facades, sports arenas and tunable-white office fixtures benefit when output can adjust dynamically while current remains within diode tolerances. This versatility lowers SKU proliferation for luminaire makers and enhances field-upgrade paths. As wireless protocols proliferate, firmware-selectable power curves make constant power designs the preferred platform in the evolving LED driver market.
Wired systems, led by DALI and 0-10 V, accounted for 64.82% of the LED driver market size in 2025 because existing-bearing structures embed control cabling. Yet wireless features head into the steep part of the adoption curve, with a 23.62% CAGR through 2031. Legrand's Matter-approved wall-box dimmers demonstrate consumer enthusiasm for app-based commissioning.
From a total-cost lens, eliminating control wires trims labour 15-25% in commercial retrofit budgets, often swinging ROI in favour of LED plus controls. Thread's IPv6 foundation eases building-management integration, and BLE mesh provides low-energy fallback for emergency lighting checks. With over-the-air firmware updates now mainstream, wireless drivers extend operating lifetimes by accommodating future features. These advantages cement wireless as a pillar of the LED driver market.
Complete Report Scope:
- By Product Type
- Constant Current LED Drivers
- Constant Voltage LED Drivers
- Constant Power LED Drivers
- By Control Feature
- Wired
- 0-10 V
- DALI
- DMX
- PLC
- Trailing-Edge
- Wireless
- Wi-Fi
- Bluetooth/BLE
- Zigbee
- Thread / Matter
- Li-Fi
- Wired
- By Power Output
- Less than 25 W
- 25 - 65 W
- 65 -150 W
- Greater than 150 W
- By Form Factor
- External Stand-Alone
- Integrated / On-Board
- Linear Drivers
- Compact / Module Drivers
- By End-Use Application
- Residential
- Commercial and Office
- Retail and Hospitality
- Outdoor and Street Lighting
- Industrial
- Healthcare and Education
- Automotive Lighting Systems
- Horticulture and Agriculture
- Consumer-Electronics Backlighting
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America's 31.96% revenue share in 2025 derives from rigorous lamp-efficacy rules that raise the bar to 83-195 lm/W, steering specifiers toward high-efficiency drivers. Corporate retrofits such as Coca-Cola Consolidated's six-facility upgrade realize USD 97,063 annual savings and underline the quick payback narrative. The CHIPS Act allocates USD 200 billion for domestic fabs, improving resilience for analog and power components. Canada and Mexico leverage integrated supply chains to share technical standards and qualification labs, smoothing cross-border shipments.
Asia-Pacific exhibits the fastest structural rise, projecting a 23.51% CAGR through 2031. China's manufacturing depth slashes BOM costs, and its municipal smart-city grants stimulate local demand for drivers with NB-IoT or LoRa gateways. India's record-scale UJALA program replenishes lamp inventories at end-of-life, kick-starting a second-wave luminaire upgrade cycle. Japan, South Korea and Taiwan channel EV-led headlamp innovations into exportable adaptive-beam drivers. ASEAN markets absorb supply-chain diversification, with Vietnam emerging as a finish-and-assembly hub for North American brands.
Europe sustains momentum through Ecodesign 2019/2020, which targets 96 TWh savings annually by 2030. Germany's KfW-bank subsidies tie preferential interest rates to intelligent-lighting deployment, accelerating driver replacements in logistics warehouses. Eastern European retrofit pipelines receive cohesion-fund backing, while the United Kingdom's Building Regulations Part L references dynamic-lighting guidance that favours drivers capable of open-protocol communication. The Middle East and Africa supplement the global LED driver market with Vision 2030 programs, typified by Saudi Arabia's 9.6% CAGR LED adoption outlook underpinned by local assembly ventures.
- Signify
- ams OSRAM
- Acuity Brands Lighting
- Hubbell Incorporated
- Eaton (Cooper Lighting)
- Lutron Electronics
- Cree LED (SGH)
- MEAN WELL Enterprises
- Inventronics
- Tridonic (Zumtobel)
- Delta Electronics
- Shenzhen Done Power
- ERP Power
- Lifud Technology
- Helvar
- Murata Manufacturing
- Texas Instruments
- ON Semi
- Allegro MicroSystems
- ROHM Semiconductor
- Macroblock Inc.
- TCI Srl
- MOSO Power
- Current (GE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Subsidy-fuelled LED retrofit programs (post-2025 roll-outs)
- 4.2.2 Rapid price declines in GaN-on-Si driver ICs
- 4.2.3 Smart-lighting mandates in new-build codes
- 4.2.4 Mainstream adoption of Matter/Thread wireless controls
- 4.2.5 Surge in EV headlamp LED driver demand
- 4.2.6 Corporate net-zero targets accelerating industrial upgrades
- 4.3 Market Restraints
- 4.3.1 Persistent silicon supply constraints for driver ICs
- 4.3.2 Limited interoperability across legacy wired protocols
- 4.3.3 Design-in complexity for non-isolated drivers
- 4.3.4 High import tariffs on Chinese constant-current modules
- 4.4 Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Constant Current LED Drivers
- 5.1.2 Constant Voltage LED Drivers
- 5.1.3 Constant Power LED Drivers
- 5.2 By Control Feature
- 5.2.1 Wired
- 5.2.1.1 0-10 V
- 5.2.1.2 DALI
- 5.2.1.3 DMX
- 5.2.1.4 PLC
- 5.2.1.5 Trailing-Edge
- 5.2.2 Wireless
- 5.2.2.1 Wi-Fi
- 5.2.2.2 Bluetooth/BLE
- 5.2.2.3 Zigbee
- 5.2.2.4 Thread / Matter
- 5.2.2.5 Li-Fi
- 5.2.1 Wired
- 5.3 By Power Output
- 5.3.1 Less than 25 W
- 5.3.2 25 - 65 W
- 5.3.3 65 -150 W
- 5.3.4 Greater than 150 W
- 5.4 By Form Factor
- 5.4.1 External Stand-Alone
- 5.4.2 Integrated / On-Board
- 5.4.3 Linear Drivers
- 5.4.4 Compact / Module Drivers
- 5.5 By End-Use Application
- 5.5.1 Residential
- 5.5.2 Commercial and Office
- 5.5.3 Retail and Hospitality
- 5.5.4 Outdoor and Street Lighting
- 5.5.5 Industrial
- 5.5.6 Healthcare and Education
- 5.5.7 Automotive Lighting Systems
- 5.5.8 Horticulture and Agriculture
- 5.5.9 Consumer-Electronics Backlighting
- 5.5.10 Other Applications
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Qatar
- 5.6.5.1.5 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Nigeria
- 5.6.5.2.4 Kenya
- 5.6.5.2.5 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Signify
- 6.4.2 ams OSRAM
- 6.4.3 Acuity Brands Lighting
- 6.4.4 Hubbell Incorporated
- 6.4.5 Eaton (Cooper Lighting)
- 6.4.6 Lutron Electronics
- 6.4.7 Cree LED (SGH)
- 6.4.8 MEAN WELL Enterprises
- 6.4.9 Inventronics
- 6.4.10 Tridonic (Zumtobel)
- 6.4.11 Delta Electronics
- 6.4.12 Shenzhen Done Power
- 6.4.13 ERP Power
- 6.4.14 Lifud Technology
- 6.4.15 Helvar
- 6.4.16 Murata Manufacturing
- 6.4.17 Texas Instruments
- 6.4.18 ON Semi
- 6.4.19 Allegro MicroSystems
- 6.4.20 ROHM Semiconductor
- 6.4.21 Macroblock Inc.
- 6.4.22 TCI Srl
- 6.4.23 MOSO Power
- 6.4.24 Current (GE)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Emerging Opportunities in Non-Isolated Drivers
- 7.3 Visible-Light Communication Integration
- 7.4 GaN and SiC-based Driver IC Adoption


