

|
시장보고서
상품코드
2122753
전선 대 기판 커넥터 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Wire-to-Board Connector - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
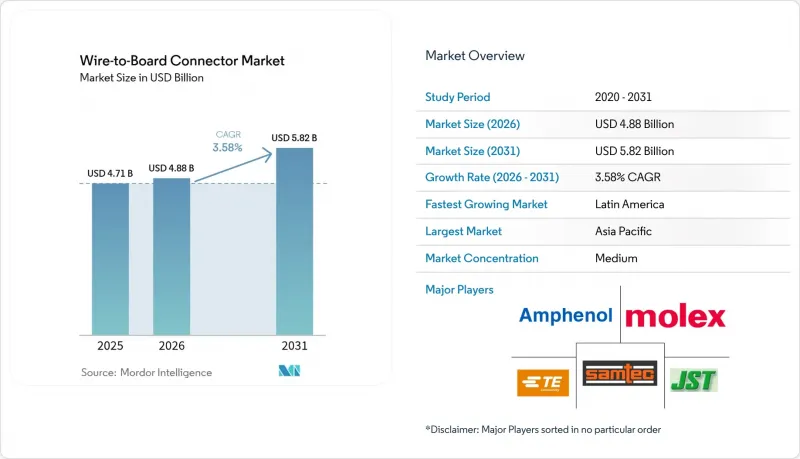
에 의하면, 전선 대 기판 커넥터 시장 규모는 2025년 47억 1,000만 달러로 평가되었습니다. 2026년에는 48억 8,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 3.58%로 성장을 지속하여, 2031년까지 58억 2,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 피치 크기(2mm 이하, 2.1-4mm, 4mm 초과), 장착 유형(표면 실장형, 스루홀), 정격 전류(1A 이하, 1.1A-3A, 3A 초과),배향(수직, 직각), 최종 사용자 산업(가전제품, IT 및 통신, 자동차, 의료기기, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 전선 대 기판 커넥터 시장 동향 및 인사이트
아시아에서 초소형 웨어러블 기기에 따른 2mm 이하 피치에 대한 수요 견인
피트니스 트래커나 스마트 워치에서는 더 작은 실적가 요구되고 있기 때문에 현재 2mm 이하 커넥터가 출하량의 대부분을 차지하고 있습니다. Molex의 0.175mm 피치 제품군은 0.35mm의 패드 크기를 유지하면서도 스태거드 접점을 통해 납땜의 한계를 극복하고 있음을 보여줍니다. 금속 사출 성형(MIM) 기술을 통해 엄격한 공차를 충족하는 초소형 하우징의 양산이 가능해졌습니다. 아시아태평양의 제조업체들은 필요한 금형을 집중적으로 확보함으로써 해당 지역의 우위를 더욱 공고히 하고 있습니다. 폼 팩터가 소형화됨에 따라, 다학제적 팀이 신호 무결성과 전자기 간섭(EMI) 대책을 동시에 해결하고 있습니다.
EV용 배터리 BMS의 급속한 보급에 따른 대전류 커넥터 수요 증가
EV 배터리 팩의 배터리 관리 시스템에서는 6A를 초과하는 커넥터 사양이 점점 늘어나고 있으며, 이는 전선 대 기판 커넥터 시장에서 가장 빠르게 성장하고 있는 전류 등급입니다. TE Connectivity의 ‘HC-Stak’은 단자 크기를 최대 30% 줄이고 알루미늄 배선을 지원함으로써 차량 경량화 목표 달성을 용이하게 합니다. PennEngineering의 ‘ECCB’와 같은 특수 부싱은 알루미늄의 산화에도 불구하고 낮은 저항을 유지합니다. 중국, 유럽, 북미의 전기차 판매량 증가는 공급업체의 거점 배치에 영향을 미치는 수요 집중 현상을 초래하고 있습니다.
PCB 면적 축소에 따른 랜딩 패드 제한
0.4mm 이하의 커넥터 패드는 픽 앤 플레이스 정밀도에 문제를 야기하고 재작업 비용을 증가시켜 단기적인 성장을 저해하고 있습니다. 레이아웃의 고밀도화는 크로스 토크와 열 핫스팟을 악화시켜 비용이 많이 드는 고 Tg 라미네이트의 사용을 불가피하게 만들며, 비용 절감 효과를 저해하고 있습니다. 수율 저하로 인해 일부 OEM은 조립 라인 업그레이드가 완료될 때까지 차세대 레이아웃 도입을 연기하고 있습니다.
부문별 분석
2mm 이하 커넥터는 2025년 매출의 47.35%를 차지하며, 전선 대 기판 커넥터 시장의 소형화 추세를 주도했습니다. 스마트폰, 웨어러블, 임베디드 기기의 기판이 더욱 소형화됨에 따라, 이 부문은 2031년까지 연평균 성장률(CAGR) 3.59%로 성장할 전망입니다. 2.1-4mm급은 크기보다 기계적 견고성이 우선시되는 자동차용 모듈에서 여전히 필수적입니다. 4mm를 초과하는 제품은 특수한 대전류 요구 사항을 충족하고 있지만, 시장 점유율은 꾸준히 감소하고 있습니다.
저항값 50mΩ 이하인 80마이크로미터 피치 접점에 대한 조사 프로토타입은 미래의 패러다임 전환을 시사하고 있습니다. 아시아태평양의 제조 거점에는 2mm 이하 금형의 대부분이 집중되어 있어, 이 지역의 우위를 강화하고 있습니다. 피치가 축소됨에 따라 설계자는 신호 무결성, 열 확산, 삽입력 등을 동시에 최적화해야 하며, 전선 대 기판 커넥터 시장에서 이 부문은 부문 간 협업의 핵심이 되고 있습니다.
2025년 매출액 중 표면 실장 커넥터가 56.85%를 차지했으며, 이는 소비자용 및 산업용 제품 라인 전반에 걸친 자동화의 진전을 반영하고 있습니다. 자동 픽 앤 플레이스(pick-and-place)를 통해 접합부당 비용이 절감되고 PCB 드릴링 작업도 줄어들기 때문에 연평균 성장률(CAGR) 3.5%가 유지되고 있습니다. 스루홀은 여전히 전력 전자 분야에서 중요하며, 이 분야에서는 더 큰 솔더 배럴이 방열 및 내충격성에 기여하고 있습니다.
고밀도 표면 실장 기판에서의 리워크는 인접한 부품이 작업을 방해하기 때문에 비용이 많이 듭니다. IPC/WHMA-A-620 표준에서는 더 엄격한 공정 허용 오차를 요구하고 있지만, 많은 구형 생산 라인은 이를 충족하는 데 어려움을 겪고 있습니다. 아시아태평양은 여전히 가장 잘 갖춰진 표면 실장 인프라를 유지하고 있는 반면, 북미의 일부 시설에서는 전선 대 기판 커넥터 시장에서 견고한 조립을 위해 여전히 스루홀 방식을 선호하고 있습니다.
지역별 분석
아시아태평양은 중국, 일본, 한국에 PCB 및 최종 조립 생산 능력이 집중되어 있어 2025년 매출의 46.25%를 차지했습니다. 인도는 인센티브를 통해 추가 생산 거점을 유치함으로써 지역 기반을 확대되고 있습니다. 동남아시아 국가들은 반도체 패키징을 주도하며, 고밀도 커넥터를 현지 공급망에 통합하고 있습니다. 이러한 기본적 요인으로 인해, 예측 기간 동안 전선 대 기판 커넥터 시장은 이 지역에 확고히 자리 잡을 전망입니다.
북미에서는 멕시코의 자동차 조립, 미국의 첨단 항공우주 산업, 그리고 지역 전반에 걸친 의료기기 수출이 결합되어 있습니다. 생산의 국내 복귀(리쇼어링) 노력과 관세의 영향으로 일부 커넥터 제품 라인은 아시아에서 철수되고 있지만, 비용 격차는 여전히 존재하고 있습니다. 캐나다의 광산기계 부문은 전선 대 기판 커넥터 시장에서 내환경성이 뛰어난 제품에 대한 국지적인 수요를 창출하고 있습니다.
유럽에서는 커넥터의 기술 혁신이 EV(전기차) 구동계 도입 및 인더스트리 4.0으로의 업그레이드와 연동되고 있습니다. 독일은 자동차용 대전류 커넥터 개발을 주도하고 있는 반면, 북유럽의 전력 회사들은 풍력 발전 및 그리드 저장 설비에 커넥터를 통합하고 있습니다. 엄격한 RoHS 및 REACH 규제로 인해 전 세계 공급업체들은 규정을 준수하는 화학 물질을 채택해야 하는 압박을 받고 있습니다. 라틴아메리카는 브라질 자동차 산업의 성장에 힘입어, 각 OEM 업체들이 환율 리스크를 헤지하기 위해 현지 조달 비율을 높이고 있는 덕분에 4.99%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 규모는 작지만 증가 추세에 있는 아프리카와 중동의 태양광 마이크로그리드 프로젝트가 전 세계적인 확산을 보완하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the wire-to-board connector market size is expected to grow from USD 4.71 billion in 2025 to USD 4.88 billion in 2026 and is forecast to reach USD 5.82 billion by 2031 at 3.58% CAGR over 2026-2031.
This report is Segmented by Pitch Size (Up To 2 Mm, 2. 1 To 4 Mm, Above 4 Mm), Mounting Type (Surface-Mount, and Through-Hole), Current Rating (Up To 1 A, 1. 1 A To 3 A, and More), Orientation (Vertical, and Right-Angle), End-User Vertical (Consumer Electronics, IT and Telecommunication, Automotive, Medical Devices, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Wire-to-Board Connector Market Trends and Insights
Ultra-compact Wearables Driving Sub-2 mm Pitch Demand in Asia
Sub-2 mm connectors now dominate shipments because fitness trackers and smartwatches require ever-smaller footprints. Molex's 0.175 mm pitch range illustrates how staggered contacts overcome soldering limits while keeping 0.35 mm pads. Metal Injection Molding supports mass production of microminiature housings with tight tolerances. Asia-Pacific manufacturers concentrate the necessary tooling, reinforcing the region's lead. As form factors shrink, cross-disciplinary teams address signal integrity and electromagnetic interference concurrently.
Rapid EV-Battery BMS Adoption Boosting High-Current Connectors
Battery management systems in EV packs increasingly specify connectors above 6 A, the fastest-growing current class of the wire-to-board connector market. TE Connectivity's HC-Stak cuts terminal size by up to 30% and supports aluminum cabling, easing vehicle mass targets. Specialized bushings such as PennEngineering's ECCB maintain low resistance despite aluminum oxidation. Rising EV volumes in China, Europe, and North America create demand clusters that influence supplier footprints.
PCB Real-Estate Shrink Limiting Landing Pads
Connector pads under 0.4 mm challenge pick-and-place accuracy and raise rework costs, depressing short-term growth. Denser layouts heighten crosstalk and thermal hotspots, forcing expensive high-Tg laminates that erode savings. Yield drops prompt some OEMs to delay next-gen layouts until assembly lines upgrade.
Other drivers and restraints analyzed in the detailed report include:
- Automation Retrofits in Brownfield Factories Raising Sensor Refresh
- LEO-Satellite Constellations Requiring Vibration-Resistant Connectors
- Solder-Joint Reliability at >125 °C Under-Hood
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sub-2 mm connectors captured 47.35% of 2025 revenue and anchor the wire-to-board connector market's miniaturization wave. The segment expands at a 3.59% CAGR to 2031 as smartphones, hearables, and implantables shrink boards further. The 2.1-4 mm class remains essential in automotive modules where mechanical robustness trumps size. Above-4 mm products cater to specialized high-current needs but steadily lose share.
Research prototyping 80 µm pitch contacts with <50 mΩ resistance hints at future disruption. Asia-Pacific fabs house most sub-2 mm tooling, reinforcing regional dominance. Designers must co-optimize signal integrity, thermal spread, and insertion force as pitches fall, making this slice of the wire-to-board connector market a nexus for cross-discipline collaboration.
Surface-mount connectors owned 56.85% of 2025 sales, reflecting automation's pull across consumer and industrial lines. Automated pick-and-place lowers cost per joint and limits PCB drilling, supporting a 3.5% CAGR. Through-hole remains critical for power electronics, where larger solder barrels aid heat dissipation and shock resistance.
Rework on dense surface-mount boards is costly because neighboring components block access. IPC/WHMA-A-620 calls for tighter process windows that many legacy lines struggle to meet. Asia-Pacific maintains the strongest surface-mount infrastructure, whereas some North American facilities still favor through-hole for rugged assemblies in the wire-to-board connector market.
Complete Report Scope:
- By Pitch Size
- Upto 2 mm
- 2.1 - 4 mm
- Above 4 mm
- By Mounting Type
- Surface-Mount
- Through-Hole
- By Current Rating
- Up to 1 A
- 1.1 A - 3 A
- 3.1 A - 6 A
- Above 6 A
- By Orientation
- Vertical
- Right-angle
- By End-User Vertical
- Consumer Electronics
- IT and Telecommunication
- Automotive
- Industrial Automation
- Aerospace and Defense
- Medical Devices
- Others (Energy, Lighting)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 46.25% of 2025 turnover owing to clustered PCB and final-assembly capacity in China, Japan, and South Korea. Incentives draw supplementary builds to India, widening the regional base. Southeast Asian nations lead semiconductor packaging, pulling high-density connectors into local supply chains. These fundamentals keep the wire-to-board connector market firmly anchored in the region for the forecast horizon.
North America combines automotive assembly in Mexico, advanced aerospace in the United States, and medical device exports across the zone. Reshoring initiatives and tariff exposure are nudging selected connector lines back from Asia, yet cost gaps persist. Canada's mining equipment sector adds pockets of demand for ruggedized variants of the wire-to-board connector market.
Europe aligns connector innovation with EV drivetrain rollouts and Industrie 4.0 upgrades. Germany spearheads high-current development for vehicles, while Nordic utilities integrate connectors into wind and grid-storage assets. Strict RoHS and REACH mandates drive global suppliers to adopt compliant chemistries. Latin America, led by Brazil's automotive growth, posts the fastest 4.99% CAGR as OEMs deepen local content to buffer currency risk. Small but rising African and Middle-Eastern projects in solar micro-grids round out global exposure.
- TE Connectivity Ltd.
- Molex LLC
- Amphenol ICC (Amphenol Corp.)
- J.S.T. Mfg. Co. Ltd.
- Samtec Inc.
- Hirose Electric Co. Ltd.
- Harting Technology Group
- Phoenix Contact GmbH and Co. KG
- Wago Kontakttechnik GmbH and Co. KG
- ERNI Deutschland GmbH
- Kyocera-AVX Components
- Wurth Elektronik GmbH and Co. KG
- Yazaki Corp.
- Luxshare Precision
- Foxconn Interconnect Technology
- JAE Electronics Inc.
- LEMO SA
- Harwin Plc
- Global Connector Technology (GCT)
- Omron Electronic Components
- Shenzhen Deren Electronics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ultra-compact wearables driving sub-2 mm pitch demand in Asia
- 4.2.2 Rapid EV-battery BMS adoption boosting high-current WTB connectors
- 4.2.3 Automation retrofits in brownfield factories raising sensor-connector refresh
- 4.2.4 LEO-satellite constellation build-outs requiring vibration-resistant connectors
- 4.2.5 Open-compute server designs shifting to higher-speed mezzanine WTB formats
- 4.2.6 Medical disposables (single-use endoscopes) scaling volumes of low-cost micro-WTB
- 4.3 Market Restraints
- 4.3.1 PCB real-estate shrink limiting connector landing padsLess than 0.4 mm
- 4.3.2 Solder-joint reliability concerns at Above 125 °C under-hood environments
- 4.3.3 Trade-war tariffs inflating BOM pricing for U S importers
- 4.3.4 Supply-chain counterfeit risk for high-density connectors
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory and Technological Outlook
- 4.5.1 Materials RoHS/REACH compliance trends
- 4.5.2 Technology Snapshot - 112 Gbps PAM4 and 0.175 mm pitch road-maps
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Buyers
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Pitch Size
- 5.1.1 Upto 2 mm
- 5.1.2 2.1 - 4 mm
- 5.1.3 Above 4 mm
- 5.2 By Mounting Type
- 5.2.1 Surface-Mount
- 5.2.2 Through-Hole
- 5.3 By Current Rating
- 5.3.1 Up to 1 A
- 5.3.2 1.1 A - 3 A
- 5.3.3 3.1 A - 6 A
- 5.3.4 Above 6 A
- 5.4 By Orientation
- 5.4.1 Vertical
- 5.4.2 Right-angle
- 5.5 By End-User Vertical
- 5.5.1 Consumer Electronics
- 5.5.2 IT and Telecommunication
- 5.5.3 Automotive
- 5.5.4 Industrial Automation
- 5.5.5 Aerospace and Defense
- 5.5.6 Medical Devices
- 5.5.7 Others (Energy, Lighting)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Nordics
- 5.6.2.5 Rest of Europe
- 5.6.3 South America
- 5.6.3.1 Brazil
- 5.6.3.2 Rest of South America
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South-East Asia
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Gulf Cooperation Council Countries
- 5.6.5.1.2 Turkey
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 TE Connectivity Ltd.
- 6.4.2 Molex LLC
- 6.4.3 Amphenol ICC (Amphenol Corp.)
- 6.4.4 J.S.T. Mfg. Co. Ltd.
- 6.4.5 Samtec Inc.
- 6.4.6 Hirose Electric Co. Ltd.
- 6.4.7 Harting Technology Group
- 6.4.8 Phoenix Contact GmbH and Co. KG
- 6.4.9 Wago Kontakttechnik GmbH and Co. KG
- 6.4.10 ERNI Deutschland GmbH
- 6.4.11 Kyocera-AVX Components
- 6.4.12 Wurth Elektronik GmbH and Co. KG
- 6.4.13 Yazaki Corp.
- 6.4.14 Luxshare Precision
- 6.4.15 Foxconn Interconnect Technology
- 6.4.16 JAE Electronics Inc.
- 6.4.17 LEMO SA
- 6.4.18 Harwin Plc
- 6.4.19 Global Connector Technology (GCT)
- 6.4.20 Omron Electronic Components
- 6.4.21 Shenzhen Deren Electronics
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


