

|
시장보고서
상품코드
2122762
RWE(Real World Evidence) 솔루션 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Real-World Evidence Solutions - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
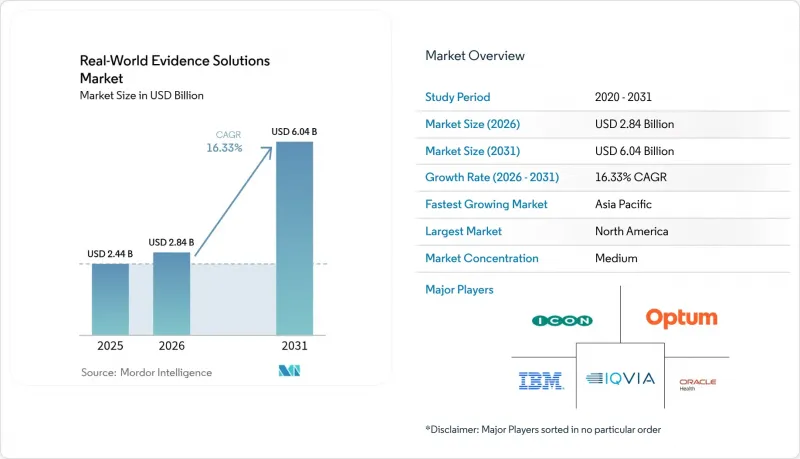
에 의하면, RWE(Real World Evidence) 솔루션 시장 규모는 2025년 24억 4,000만 달러로 평가되었습니다. 2026년에는 28억 4,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 16.33%로 성장을 지속하여, 2031년에는 60억 4,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 구성 요소(서비스, 기타), 배포 모드(클라우드 기반, 기타), 치료 분야(종양학, 기타), 용도(의약품 개발 및 승인, 기타), 최종 사용자(제약 및 의료기기 기업, 기타), 지역(북미, 유럽, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 RWE(Real World Evidence) 솔루션 시장 동향 및 인사이트
주요 규제 당국의 규제 수용도 증가
미국 FDA의 ‘실세계 증거 프레임워크(Real-World Evidence Framework)’와 이에 상응하는 시범 프로그램을 통해, 청구 데이터 및 전자 건강 기록(EHR)을 기반으로 구축된 외부 관리 코호트를 제출하기 위한 공식적인 절차가 확립되었습니다. 유럽의약품청(EMA)도 ‘데이터 분석 및 리얼 월드 연구 네트워크(DARI)’를 통해 이러한 추세를 따르며, 여러 합성군(synthetic arm) 제안에 대해 긍정적인 적격성 의견을 발표했습니다. 일본의 PMDA도 이에 발맞추어 2024년에 실세계 데이터의 신뢰성 검증에 관한 지침을 발표했습니다. 현재, 후원 기업들은 2상 임상시험의 초기 단계부터 관찰 연구 평가 지표를 포함시키기 시작하여 3상 임상시험의 불확실성을 줄이고 있습니다. 그 결과, 투명성이 높은 데이터 리니지는 단순한 규정 준수상의 사후 요건에서 최전선의 차별화 요인으로 변화했습니다. 이에 따라 감사 대응이 가능한 파이프라인을 제공하는 벤더가 높이 평가받으며, 리스크 회피 성향이 강한 바이오의약품 조달 팀 간의 계약 체결이 가속화되고 있습니다.
디지털화된 의료 데이터의 급속한 확대
2024년, 미국 비연방 급성기 병원의 전자 건강 기록(EHR) 도입률은 89.0%를 넘어섰으며, 실제 세계 증거 솔루션 시장에 페타바이트 규모의 구조화된 데이터가 추가되었습니다. 웨어러블 기기는 지속적인 생리학적 데이터 스트림을 생성하며, 차세대 시퀀싱의 출력은 분자 시그니처를 통해 질병 레지스트리를 보강하고 있습니다. 다중 모드 연계를 통해 연구자들은 영상 데이터, 약국 청구 데이터, 사회적 결정 요인 지표를 결합할 수 있게 되어, 기존의 임상 검사만으로는 파악할 수 없었던 표현형을 규명할 수 있게 되었습니다. 그러나 EU의 GDPR(EU 개인정보보호규정)이나 캘리포니아주의 CPRA와 같은 더욱 엄격한 개인정보 보호 관련 법규로 인해 감독 체제가 강화되고 있습니다. 식별자를 비가역적인 해시 값으로 변환하는 토큰화 제공업체는 핵심 파트너로 자리 잡고 있습니다. 또한, 원시 데이터를 집계하는 대신 코드를 데이터 측으로 이동시키는 연합 학습 네트워크(Federated Learning Network)를 통해, 데이터 거주지 규정을 위반하지 않고 국경을 초월한 공동 연구가 가능해졌습니다. 서로 다른 분류 체계를 공통의 데이터 모델 아래에서 통합할 수 있는 벤더는 연구 시작 기간을 수개월 단축하여 측정 가능한 우위를 확보하고 있습니다.
AI 및 고급 분석 플랫폼의 성숙에 따른 실행 가능한 인사이트력 도출
트랜스포머 기반 자연어 처리 모델은 2024년 검증 연구에서 비정형 병리 보고서에서 종양학 엔드포인트를 추출할 때 F1 점수 0.90 이상을 달성하여, 수작업에 의한 데이터 추출 비용을 60% 이상 절감했습니다. IQVIA의 Applied AI 포트폴리오를 통해 도입된 NVIDIA의 DGX H100 클러스터는 모델 훈련 시간을 며칠에서 몇 시간으로 단축하여 예측 모델의 신속한 반복 개발을 가능하게 하고 있습니다. 합성 데이터 생성 기술은 클래스 불균형 및 개인정보 보호 제약 사항을 해결하고, 개인을 식별할 수 있는 기록을 공개하지 않으면서도 학습 데이터 세트를 확장합니다. 이러한 생산성 향상은 고액의 라이선스 비용을 정당화하며, AI 플랫폼의 성장을 실제 세계 증거(Real-World Evidence) 솔루션 시장 전체보다 더 빠른 속도로 추진하고 있습니다. 또한, GPU를 통한 추론 속도 향상은 지불 기관과의 협상 중에 필요에 따라 증거를 검색하는 메디컬 어페어즈 팀에게 중요한 구매 기준인 쿼리 지연 시간을 줄여줍니다.
부문별 분석
2025년에는 서비스가 리얼 월드 에비던스 솔루션 시장의 54.30%를 차지했습니다. 이는 임상시험 설계, 데이터 큐레이션, 규제 전략에서 스폰서가 외부 역학자, HEOR 컨설턴트, 생물통계학자에 의존하고 있음을 반영합니다. IQVIA, ICON, Syneos Health와 같은 주요 서비스 제공업체들은 약국 청구 데이터와 EHR 피드를 연동하는 토큰화 파이프라인을 번들로 제공하고 있으며, 이를 통해 종단적 추적 조사가 가능해져 고객의 전환 비용이 증가하고 있습니다. 다년간의 아웃소싱 계약을 통해 수익 전망이 확보되고, 거시경제 변동으로 인한 영향이 완화되고 있습니다. 또한, 서비스 팀은 GDPR(EU 개인정보보호규정)에서 의무화한 개인정보 영향 평가에 대한 자문도 제공하여 유럽 내 연구 승인 절차를 신속화하는 데 기여하고 있습니다.
소프트웨어 부문은 현재 규모는 작지만, 플랫폼 벤더들이 클라우드 네이티브 아키텍처를 상용화하고 있어 연평균 성장률(CAGR) 17.78%로 확대되고 있습니다. 구독 모델이 변동이 심한 프로젝트 비용을 대체함으로써 벤더의 현금 흐름을 개선하고 있습니다. 핵심 플랫폼에 통합된 AI 모듈은 방사선 진단 보고서나 유전체 보고서에서 엔드포인트를 자동으로 추출함으로써, 수동 코딩으로 인한 병목 현상을 해소합니다. 예를 들어, ConcertAI의 SaaS 제품군은 비정형 병리 소견을 수집하여 트랜스포머 모델을 활용해 종양의 병기를 분류하고, 분석 가능한 정형화된 데이터 형태로 출력합니다. 플랫폼 도입은 많은 경우 맞춤형 분석을 요구하는 추가 서비스 요청으로 이어져, 소프트웨어 부문과 컨설팅 부문 간의 상생적 성장의 선순환을 만들어내고 있습니다.
클라우드는 탄력적인 컴퓨팅 능력과 종량제 가격 책정을 활용하여 2025년에는 실제 세계 증거(RWE) 솔루션 시장 규모의 64.35%를 차지했습니다. AWS 시장에서 RWE 분석 관련 게시물 수는 전년 대비 40% 이상 증가했으며, 이는 공동 책임형 보안 모델을 충족하는 사전 승인된 공급업체에 대한 구매자의 강한 선호도를 보여줍니다. 초기 전환 단계에서는 익명화된 코호트가 대상이 되며, 보호 대상인 의료 정보는 암호화 프레임워크와 키 관리 방안이 성숙된 후에야 전환됩니다. 미국의 의료 시스템에서는 수요가 정점에 달할 때 퍼블릭 클라우드의 GPU 버스트를 활용하여 NLP 모델을 학습시킴으로써, 자본 집약적인 서버 구매를 피하고 있습니다.
하이브리드 배포는 연평균 성장률(CAGR) 20.66%로 확대되고 있으며, 학술 의료 센터 및 공공 자금 지원 연구 네트워크는 On-Premise 환경에서의 데이터 주권과 확장 가능한 분석 간의 균형을 모색하고 있습니다. 예를 들어, Oracle의 ‘Cloud&Customer’ 노드는 병원 방화벽 내에 설치되어 있으면서도 고부하 계산 작업을 위해 퍼블릭 리전과 연동되어, 유럽 데이터 보호 위원회(EDPB)의 데이터 거주에 관한 지침을 충족합니다. 이러한 조치를 통해 워크로드 오케스트레이션(PHI를 포함한 기밀성이 높은 쿼리를 자동으로 프라이빗 클러스터로 라우팅하는 기능)을 제공하는 벤더는 도입에 있어 중대한 장벽을 해소하고, 기존의 On-Premise 환경을 대체하고 있습니다. 자본 집약적인 시설에서는 기존 서버 랙의 수명을 연장하는 동시에 버스트 워크로드를 위해 클라우드 GPU를 활용함으로써 총 소유 비용(TCO)을 개선하고 있습니다.
지역별 분석
2025년, 북미는 40.95%의 점유율을 차지하며 실제 세계 증거(RWE) 솔루션 시장을 주도했습니다. FDA의 RWE 파일럿 프로그램은 명확한 절차적 지침을 제공하여 후원사의 증거 관련 위험을 완화하고 있습니다. 한편, 미국의 보험사들은 고가 의약품 계약에 성과 지표를 포함하고 있으며, 이는 간접적으로 규정 준수를 충족하는 분석에 대한 수요를 견인하고 있습니다. 자본 시장은 데이터 중심의 비즈니스 모델을 높이 평가하고 있으며, 나스닥에 상장된 RWE 벤더의 기업 가치는 임상 CRO 동종 업체를 상회하는 매출 배수로 거래되고 있어, 제품 로드맵에 대한 적극적인 재투자가 가능해졌습니다.
유럽은 2위를 차지했습니다. 이는 국경을 넘는 데이터 재사용에 필요한 기술적·법적 프레임워크를 의무화하는 향후 시행될 ‘유럽 헬스 데이터 스페이스(HDS)’ 규정에 힘입은 결과입니다. GDPR(EU 개인정보보호규정)을 준수하는 아키텍처와 HDS 인증을 통해 벤더는 각국의 의료 서비스 기관과 원활하게 협력할 수 있게 됩니다. 여러 지불 주체가 존재하는 환경은 틈새 비즈니스 기회를 창출하고 있습니다. 프랑스의 ATU(임시 승인) 제도나 독일의 AMNOG(신약 승인) 절차에서는 부가가치를 확인하기 위한 실세계 증거의 수용이 확대되고 있어, 암이나 희귀질환에 특화된 데이터 세트의 비즈니스 기회가 창출되고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR)은 17.46%로 예측됩니다. 중국 국가약품감독관리국은 신약 신청의 보충 자료로 외국 실세계 데이터를 수용하는 것에 관한 2024년 지침을 발표하여 다국적 후원사의 신청 장벽을 낮췄습니다. 일본 후생노동성은 디지털 바이오마커 시범 사업에 자금을 지원하며 신경학 연구의 데이터 소스를 확대되고 있습니다. 호주의 ‘My Health Record’ 시스템은 인구의 95% 이상의 커버리지를 달성하여, 해외 스폰서를 유치할 수 있는 견고한 종단적 데이터 세트를 구축하고 있습니다. 국경을 초월한 민관 파트너십을 통해 데이터 사전의 표준화가 진행되고 있어, 다국간 코호트 통합이 가능해졌으며, 전 세계 AI 모델 알고리즘의 일반화 성능이 향상되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the real-world evidence solutions market size is expected to grow from USD 2.44 billion in 2025 to USD 2.84 billion in 2026 and is forecast to reach USD 6.04 billion by 2031 at 16.33% CAGR over 2026-2031.
This report is Segmented by Component (Services, and More), Deployment Mode (Cloud-Based, and More), Therapeutic Area (Drug Development & Approvals, and More), Application (Drug Development & Approvals, and More), End User (Pharmaceutical & Medical-Device Companies, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Real-World Evidence Solutions Market Trends and Insights
Growing Regulatory Acceptance Across Major Agencies
The U.S. FDA's Real-World Evidence Framework and corresponding pilot programs have formalized pathways for submitting externally controlled cohorts built from claims and EHR records. The European Medicines Agency mirrors this trend under its Data Analysis and Real-World Interrogation Network, publishing positive qualification opinions for multiple synthetic-arm proposals. Japan's PMDA followed with its 2024 guidance on real-world data reliability testing. Sponsors now embed observational endpoints as early as phase II, reducing uncertainty in pivotal trials. Transparent data lineage has thus shifted from a compliance afterthought to a frontline differentiator, rewarding vendors that deliver audit-ready pipelines and accelerating contract sign-offs among risk-averse biopharma procurement teams.
Rapid Expansion of Digitized Healthcare Data
Electronic health record adoption levels surpassed 89.0% among U.S. non-federal acute-care hospitals in 2024, adding petabytes of structured data to the real-world evidence solutions market. Wearables generate continuous physiologic streams, while next-generation sequencing outputs enrich disease registries with molecular signatures. Multi-modal linkages enable researchers to combine imaging, pharmacy claims and social-determinant indicators, uncovering phenotypes invisible to traditional trials. Yet stricter privacy statutes such as the EU's GDPR and California's CPRA are sharpening oversight. Tokenization providers that convert identifiers into non-reversible hashes have become central partners, and federated-learning networks that move code to the data rather than aggregating raw files allow cross-border collaboration without breaching residency rules. Vendors able to harmonize disparate taxonomies under common data models shorten study start-up by months, gaining a measurable edge.
AI and Advanced Analytics Platforms Mature to Extract Actionable Insights
Transformer-based natural language processing models achieved F1 scores above 0.90 on extracting oncology endpoints from unstructured pathology reports in 2024 validation studies, cutting manual abstraction costs by more than 60%. NVIDIA's DGX H100 clusters, deployed through IQVIA's Applied AI portfolio, reduce model training times from days to hours, enabling rapid iteration on predictive models. Synthetic-data generation techniques address class imbalance and privacy constraints, broadening training sets without exposing identifiable records. Such productivity gains justify premium license fees, pushing AI platform growth faster than the overall real-world evidence solutions market. GPU-accelerated inferencing also lowers query latency, a key buying criterion for medical-affairs teams conducting on-demand evidence searches during payer negotiations.
Other drivers and restraints analyzed in the detailed report include:
- Pharmaceutical Companies Leverage RWE to Curb R&D Timelines and Costs
- Value-Based Reimbursement Models Drive Outcomes-Oriented Evidence
- Data Privacy and Interoperability Challenges Hinder Seamless Integration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated 54.30% of the real-world evidence solutions market in 2025, reflecting sponsor dependence on external epidemiologists, HEOR consultants and biostatisticians for study design, data curation and regulatory strategy. Large service providers such as IQVIA, ICON and Syneos Health bundle tokenization pipelines that connect pharmacy claims with EHR feeds, extending longitudinal follow-up and raising client switching costs. Multi-year outsourcing frameworks ensure predictable revenue visibility, cushioning macro-economic swings. Services teams also advise on privacy-impact assessments required under GDPR, expediting European study approvals.
Software, though currently smaller, is scaling at an 17.78% CAGR as platform vendors commercialize cloud-native architectures. Subscription models replace volatile project fees, improving vendor cash flow. AI modules embedded in core platforms automatically extract endpoints from radiology and genomic reports, eliminating manual coding bottlenecks. ConcertAI's SaaS suite, for example, ingests unstructured pathology notes, classifies tumor staging with transformer models and returns structured data formats ready for analysis. Platform adoption often triggers follow-on service requests for bespoke analytics, creating a symbiotic growth loop between software and consulting units.
Cloud captured 64.35% of the real-world evidence solutions market size in 2025, benefiting from elastic compute and pay-as-you-go pricing. AWS Marketplace listings for RWE analytics rose by more than 40% year on year, indicating strong buyer preference for pre-approved vendors that satisfy shared-responsibility security models. Early migrations involve de-identified cohorts, with protected health information moving only after encryption frameworks and key-management policies mature. U.S. health systems leverage public cloud GPU bursts to train NLP models during peak demand, avoiding capital-intensive server purchases.
Hybrid deployment is advancing at 20.66% CAGR as academic medical centers and publicly funded research networks balance on-premise data sovereignty with scalable analytics. Oracle's Cloud@Customer nodes, for instance, sit behind hospital firewalls yet federate with public regions for high-intensity compute jobs, satisfying European Data Protection Board residency guidance. Vendors that deliver policy-based workload orchestration-automatically routing PHI-sensitive queries to private clusters-address a critical adoption hurdle and displace legacy on-prem installations. Capital-intensive sites extend the lifespan of existing server racks while accessing cloud GPUs for burst workloads, improving total cost of ownership.
Complete Report Scope:
- By Component
- Services
- Data Sets
- Clinical-Settings Data
- Claims & Billing Data
- Pharmacy Dispensing Data
- Patient-Powered & PRO Data
- Other Components
- Software & Analytics Platforms
- By Deployment Mode
- Cloud-based
- On-premise
- Hybrid
- By Therapeutic Area
- Oncology
- Cardiology
- Diabetes
- Neurology
- Psychiatry
- Immunology
- Other Therapeutic Areas
- By Application
- Drug Development & Approvals
- Medical-Device Development & Approvals
- Pharmacovigilance & Safety Studies
- Regulatory Decision-making & Reimbursement
- By End User
- Pharmaceutical & Medical-Device Companies
- Contract Research Organizations (CROs)
- Healthcare Providers & Payer-provider networks
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle-East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led the real-world evidence solutions market in 2025 with a 40.95% share. The FDA's RWE pilot programs provide clear procedural guidance, reducing evidentiary risk for sponsors, while U.S. insurers embed outcome metrics into high-cost drug contracts, indirectly driving demand for compliant analytics. Capital markets reward data-centric business models; valuations for listed RWE vendors on Nasdaq trade at revenue multiples above clinical CRO peers, enabling aggressive reinvestment in product roadmaps.
Europe ranked second, supported by the upcoming European Health Data Space regulation, which mandates technical and legal frameworks for cross-border data reuse. GDPR-compliant architectures and HDS accreditation smooth vendor onboarding with national health services. Multi-payer environments foster niche opportunities: France's ATU system and Germany's AMNOG pathway increasingly accept real-world evidence to confirm added benefit, opening business for specialized oncology and rare-disease datasets.
Asia-Pacific is the fastest-growing region, projected at a 17.46% CAGR. China's National Medical Products Administration issued 2024 guidance on accepting foreign real-world data for supplemental New Drug Applications, lowering submission barriers for multinational sponsors. Japan's MHLW funds digital-biomarker pilots, expanding sources for neurology studies. Australia's My Health Record system surpasses 95% population coverage, creating robust longitudinal datasets that attract overseas sponsors. Cross-border public-private partnerships are standardizing data dictionaries, enabling multi-country cohort pooling and improving algorithm generalizability for global AI models.
- IQVIA
- Optum
- Oracle Health
- ICON
- IBM
- Syneos Health
- TriNetX LLC
- Thermo Fisher Scientific
- Flatiron Health
- SAS Institute, Inc.
- Aetion Inc.
- Komodo Health
- MedPace
- ConcertAI
- Tempus Labs
- Clarivate
- Clinerion Ltd.
- Veeva Systems
- Verto Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory Acceptance Across Major Agencies
- 4.2.2 Expansion Of Digitized Healthcare Data
- 4.2.3 Pharmaceutical Use Of External Control Arms
- 4.2.4 Value-Based Reimbursement Models
- 4.2.5 Artificial-Intelligence And Advanced Analytics Platforms Maturing
- 4.2.6 Strategic Collaborations Between Cros, Tech Vendors, And Health Systems
- 4.3 Market Restraints
- 4.3.1 Data Privacy And Interoperability Hurdles
- 4.3.2 Regulatory Fragmentation In Cross-Border Studies
- 4.3.3 High Acquisition And Licensing Costs For Curated Longitudinal Datasets
- 4.3.4 Stakeholder Skepticism Regarding Methodological Rigor And Bias In RWE Studies
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Component
- 5.1.1 Services
- 5.1.2 Data Sets
- 5.1.2.1 Clinical-Settings Data
- 5.1.2.2 Claims & Billing Data
- 5.1.2.3 Pharmacy Dispensing Data
- 5.1.2.4 Patient-Powered & PRO Data
- 5.1.2.5 Other Components
- 5.1.3 Software & Analytics Platforms
- 5.2 By Deployment Mode
- 5.2.1 Cloud-based
- 5.2.2 On-premise
- 5.2.3 Hybrid
- 5.3 By Therapeutic Area
- 5.3.1 Oncology
- 5.3.2 Cardiology
- 5.3.3 Diabetes
- 5.3.4 Neurology
- 5.3.5 Psychiatry
- 5.3.6 Immunology
- 5.3.7 Other Therapeutic Areas
- 5.4 By Application
- 5.4.1 Drug Development & Approvals
- 5.4.2 Medical-Device Development & Approvals
- 5.4.3 Pharmacovigilance & Safety Studies
- 5.4.4 Regulatory Decision-making & Reimbursement
- 5.5 By End User
- 5.5.1 Pharmaceutical & Medical-Device Companies
- 5.5.2 Contract Research Organizations (CROs)
- 5.5.3 Healthcare Providers & Payer-provider networks
- 5.5.4 Other End Users
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle-East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.4.1 IQVIA Inc.
- 6.4.2 Optum Inc.
- 6.4.3 Oracle Health
- 6.4.4 ICON plc
- 6.4.5 IBM
- 6.4.6 Syneos Health
- 6.4.7 TriNetX LLC
- 6.4.8 Thermo Fisher Scientific, Inc.
- 6.4.9 Flatiron Health
- 6.4.10 SAS Institute, Inc.
- 6.4.11 Aetion Inc.
- 6.4.12 Komodo Health
- 6.4.13 Medpace Holdings Inc.
- 6.4.14 ConcertAI
- 6.4.15 Tempus Labs
- 6.4.16 Clarivate
- 6.4.17 Clinerion Ltd.
- 6.4.18 Veeva Systems
- 6.4.19 Verto Health
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


