

|
시장보고서
상품코드
2122788
세포 채취 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cell Harvesting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 세포 채취 시장 규모는 75억 7,000만 달러로 추정되고, 2025년 67억 1,000만 달러에서 확대해, 2031년에는 138억 6,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 12.86%로 성장할 것으로 전망됩니다.
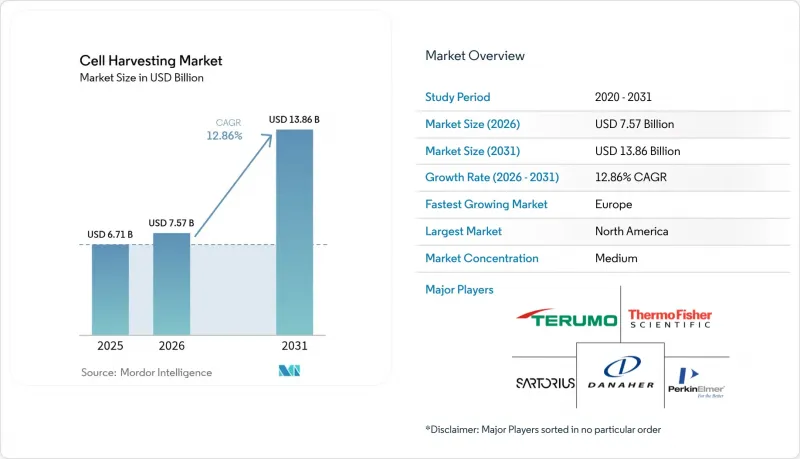
본 보고서는 세포 채취 유형별(수동식 세포 채취 장치 및 자동식 세포 채취 장치), 용도별(바이오의약품 용도, 줄기세포 연구, 기타 용도), 최종 사용자별(생명공학·바이오의약품 기업 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 세포 채취 시장 동향 및 인사이트
세포 및 유전자 치료에 대한 투자 확대
지난 10년 동안 23억 달러가 넘는 주식 투자가 세포 및 유전자 치료 벤처 기업에 유입되었으며, 전 세계적으로 1,500건 이상의 임상시험이 진행 중입니다. FDA는 2024년에 최초의 중간엽 줄기세포 제품인 ‘Ryoncil’을 포함한 8개의 신규 첨단 치료법을 승인하며, 복잡한 생물학적 제제에 대한 규제 당국의 신뢰를 보여주었습니다. 대형 제약사들은 사업 규모를 빠르게 확장하고 있습니다. 브리스톨-마이어스 스퀴브(Bristol-Myers Squibb)는 3개의 CAR-T 전용 공장을 개설했으며, 아스트라제네카(AstraZeneca)는 생체 내 프로그램을 가속화하기 위해 에소바이오텍(EsoBiotec)에 4억 2,500만 달러를 투자했습니다. 이러한 자본 유입으로 개발 기간이 단축되면서, 신뢰성이 높은 고처리량 채취 장치가 필요한 자가 유래 및 타가 유래 배치 생산량이 증가하고 있습니다. 투자자들은 현재 여러 제품 파이프라인을 지원할 수 있는 플랫폼을 우선시하고 있어, 모듈식 추가 기능을 갖춘 통합형 채취 장치의 매력이 높아지고 있습니다.
바이오의약품 제조 인프라 확대
후지필름 디오신스는 덴마크와 텍사스주에서 16억 달러 규모의 확장 계획을 통해 2만 리터 규모의 바이오리액터 8기와 전용 다운스트림 시설을 증설하는 한편,롯데바이오로직스는 2027년까지 12만 리터의 생산 능력을 달성하기 위해 마츠시마 바이오 캠퍼스에 10억 달러를 투자하기로 결정했습니다. 이러한 메가 프로젝트는 지역 클러스터를 형성하며, 일회용 및 스테인리스 라인 모두에 대응 가능한 채취 장치가 필요합니다. 많은 CDMO에서는 여전히 가동률이 50% 미만에 머물러 있으며, 오늘날에는 임상 규모의 자가 유래 로트를 비용 효율적으로 처리하면서, 내일에는 대규모 동종 유래 로트 생산으로 유연하게 전환할 수 있는 시스템에 대한 수요가 높아지고 있습니다. 교체 가능한 원심 분리 및 여과 요소를 갖춘 모듈식 스키드 구조를 제공하는 공급업체는 이러한 가동률 격차를 해소하고, 생산 우선순위가 변경되더라도 신속하게 재구성할 수 있습니다.
줄기세포 조달을 둘러싼 윤리적·규제적 우려
배아 줄기세포 연구나 유효성이 입증되지 않은 지방 유래 기법에 대해서는 재주입되는 세포가 FDA의 생물학적 제제 규제의 대상이 된다는 점을 미국 항소법원이 확인함에 따라 감독이 강화되고 있습니다. EU, 미국,아시아 간의 기증자 선별 규정 차이는 다국적 연구를 복잡하게 만들고 문서화 비용을 증가시키고 있습니다. 규제가 느슨한 지역에서 ‘기적의 치료법’을 선전하는 무허가 클리닉은 일반 시민의 신뢰를 훼손하고 있으며, 규제 당국은 경고문을 발부하고 클리닉 폐쇄를 명령하는 사태에 이르렀습니다. 윤리적 조달과 GMP를 준수하는 출처를 문서화하는 규정 준수 공급업체는 차별화를 꾀할 수 있지만, 국가마다 다르며 끊임없이 변화하는 동의 요건과 조직 은행 감사에 대응해야 합니다.
부문 분석
자동화 시스템은 노동 시간과 오염 위험을 줄여주는 폐쇄형 프로그래밍 가능한 워크플로우를 통해 2025년 세포 채취 시장의 62.85% 점유율을 차지했습니다. 2031년까지 연평균 성장률(CAGR) 14.92%를 나타낼 것으로 예측됩니다. 수동식 채취 장치는 탐색적 연구나 수작업이 효과적인 변동성이 큰 초기 단계의 프로토콜에서 여전히 중요한 역할을 하고 있습니다. 그러나 학술 연구 기관의 실험실조차도 기존 인큐베이터에 추가할 수 있는 반자동 모듈을 도입하여 수작업 감시와 디지털 모니터링을 융합하고 있습니다. 업계 전반에 걸쳐 연속 처리 및 일회용 어셈블리로의 전환이 진행됨에 따라, 향후 10년이 끝날 무렵에는 세포 채취 시장의 70% 이상을 자동화 시스템이 차지할 것으로 전망됩니다.
자동화의 기세는 공장의 디지털화 목표와 일치합니다. 각 벤더들은 원심 분리, 여과, 세척을 하나의 인클로저에 통합하여 라인 승인 및 검증 과정을 효율화하고 있습니다. 원격 진단 및 소프트웨어 업데이트를 통해 가동 중지 시간을 단축하고 성능을 사양 범위 내로 유지하고 있습니다. 여러 관할 구역에서 시스템 인증을 획득하고 24시간 부품 지원을 제공할 수 있는 공급업체는 전 세계적으로 임상시험이 확대됨에 따라 경쟁 우위를 확보하고 있습니다.
지역별 분석
북미는 2025년, 성숙한 CGT 규제 체계, 광범위한 CDMO 네트워크, 그리고 전문 물류 사업자의 지원을 받아 전 세계 매출의 38.95%를 차지했습니다. 그러나 2024년에는 적격 미국 환자 중 이용 가능한 치료법을 이용할 수 있었던 비율은 20% 미만에 그쳤으며, 이는 자동화 채취기를 통해 완화될 수 있는 프로세스의 비효율성을 여실히 드러내고 있습니다. 지역의 성장은 숙련된 인력 공급에 의존하고 있으며, 기술자를 양성하기 위해 장비 공급업체와 커뮤니티 칼리지간의 제휴 프로그램이 진행되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 14.11%로 확대될 것으로 예측됩니다. 2024년에는 전 세계 CGT 임상시험의 37%가 중국에서 수행되었으며, 일본의 ‘패스트 트랙’ 제도와 한국의 ‘재생의료법’에 따라 승인까지의 기간이 단축되었습니다. WuXi AppTec이나 SK Bioscience와 같은 국내 기업들은 CGT 허브에 막대한 투자를 하고 있으며, 현지 GMP 지침을 준수하는 채취 모듈의 대량 발주를 주도하고 있습니다. 낮은 운영 비용, 정부의 우대 조치, 만성 질환 유병률의 상승이 수요를 끌어올리고 있지만, 공급업체들은 끊임없이 변화하는 수입 규제와 다국어 품질 문서에 대응해야 하는 과제에 직면해 있습니다.
유럽은 조화로운 EMA(유럽의약품청) 지침과 덴마크, 아일랜드, 독일의 견고한 CDMO 인프라를 바탕으로 여전히 큰 시장 점유율을 유지하고 있습니다. 후지필름 디오신스의 덴마크 공장 확장은 지역의 자급자족률 향상을 목표로 한 지속적인 자본 유입을 상징하는 사례입니다. 에너지 비용의 급등으로 인해 시설에서는 사이클 타임이 짧은 에너지 절약형 채취기 도입이 진행되고 있습니다. 중동 및 아프리카 및 남미는 의료 시스템이 3차 의료에 대한 투자를 추진하고, 양자 간 기술 이전 협정을 체결하고 있어 새로운 기회가 확대되는 지역으로 주목받고 있습니다. 전력 변동에도 견딜 수 있는 콤팩트하고 견고한 하베스터는 이러한 지역에서 점점 더 널리 받아들여지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the cell harvesting market size in 2026 is estimated at USD 7.57 billion, growing from 2025 value of USD 6.71 billion with 2031 projections showing USD 13.86 billion, growing at 12.86% CAGR over 2026-2031.

This report is Segmented by Type of Cell Harvesting (Manual Cell Harvesters and Automated Cell Harvesters), Application (Biopharmaceutical Application, Stem-Cell Research, and Other Applications), End User (Biotechnology & Biopharmaceutical Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Cell Harvesting Market Trends and Insights
Growing Investment in Cell and Gene Therapies
More than USD 2.3 billion in equity has entered cell and gene therapy ventures during the last decade, underpinning over 1,500 active clinical studies worldwide. The FDA cleared eight novel advanced therapies in 2024, including the first mesenchymal stromal cell product, Ryoncil, demonstrating regulatory confidence in complex biologics. Pharmaceutical majors are scaling quickly: Bristol Myers Squibb opened three dedicated CAR-T plants, and AstraZeneca spent USD 425 million for EsoBiotec to accelerate in vivo programs. Capital inflows shorten development timelines and increase the volume of autologous and allogeneic batches that require reliable, high-throughput harvesters. Investors now prioritize platforms that can support multiproduct pipelines, lifting the appeal of integrated harvest devices with modular add-ons.
Expansion of Biopharmaceutical Manufacturing Infrastructure
Fujifilm Diosynth's USD 1.6 billion Denmark-Texas expansion adds eight 20,000 L bioreactors and specialized downstream suites, while Lotte Biologics is committing USD 1 billion for its Songdo Bio Campus to reach 120,000 L capacity by 2027. Such mega-projects create regional clusters that need harvesters compatible with both single-use and stainless-steel trains. Many CDMOs still operate at less than 50% utilization, prompting demand for flexible systems that can cost-effectively handle clinical-scale autologous lots today and pivot to large allogeneic runs tomorrow. Suppliers offering modular skid architecture with interchangeable centrifugation or filtration elements address this utilization gap and can be rapidly redeployed as production priorities change.
Ethical and Regulatory Concerns Around Stem Cell Sourcing
Embryonic stem cell research and unproven adipose-derived procedures face increased oversight after U.S. appellate courts confirmed that reinjected cells fall under FDA biologics regulation. Divergent donor screening rules in the EU, United States, and Asia complicate multinational studies and raise documentation costs. Unlicensed clinics advertising miracle cures in regions with light enforcement undermine public confidence, prompting regulators to publish warning letters and mandate clinic closures. Compliant suppliers that document ethical sourcing and GMP provenance can differentiate, but they must navigate evolving consent requirements and tissue-bank audits that vary by country.
Other drivers and restraints analyzed in the detailed report include:
- Rising Prevalence of Chronic Diseases Requiring Cell Therapies
- Technological Advancements in Automated Cell Processing
- High Cost of Automated Harvesting Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automated systems held 62.85% of the cell harvesting market share in 2025 thanks to closed, programmable workflows that cut labor hours and contamination risk. They are projected to record a 14.92% CAGR through 2031. Manual harvesters remain relevant for exploratory work or highly variable early-phase protocols that benefit from hands-on manipulation. However, even academic labs are adopting semi-automated modules that bolt onto legacy incubators, blending tactile oversight with digital monitoring. Industry-wide migration toward continuous processing and single-use assemblies will likely elevate automated systems to more than 70% of the cell harvesting market size by decade's end.
Automation's momentum aligns with factory digitization goals. Vendors are bundling integrated centrifugation, filtration, and washing in one chassis to streamline line clearance and validation. Remote diagnostics and software updates provide shorter downtimes and keep performance within specification. Suppliers able to certify systems in multiple jurisdictions and offer 24-hour parts support gain a competitive edge as global trials expand.
Complete Report Scope:
- By Type of Cell Harvesting
- Manual Cell Harvesters
- Automated Cell Harvesters
- By Application
- Biopharmaceutical Application
- Stem-Cell Research
- Other Applications
- By End User
- Biotechnology & Biopharmaceutical Companies
- Research Institutes
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 38.95% of global revenue in 2025, supported by a mature CGT regulatory framework, extensive CDMO network, and specialized logistics operators. Yet fewer than 20% of eligible U.S. patients accessed available therapies in 2024, underscoring process inefficiencies that automated harvesters can mitigate. Regional growth also depends on skilled labor supply, prompting partnership programs between equipment vendors and community colleges to cultivate technicians.
Asia-Pacific is projected to expand at 14.11% CAGR to 2031. China hosted 37% of global CGT trials in 2024, and Japan's Fast Track and South Korea's Regenerative Medicine Law cut approval timelines. Domestic players like WuXi AppTec and SK Bioscience have invested heavily in CGT hubs, driving bulk orders for harvest modules compatible with local GMP guidelines. Lower operating costs, government incentives, and rising chronic-disease prevalence amplify demand, but suppliers must adapt to evolving import regulations and multilingual quality documentation.
Europe maintains a sizable share anchored by harmonized EMA guidelines and robust CDMO infrastructure in Denmark, Ireland, and Germany. Fujifilm Diosynth's Danish plant expansion exemplifies continued capital inflow aimed at increasing regional self-sufficiency. Energy costs push facilities to adopt energy-efficient harvesters with shorter cycle times. The Middle East & Africa and South America are emerging opportunity zones as healthcare systems invest in tertiary care and establish bilateral technology-transfer agreements. Compact, rugged harvesters that tolerate power fluctuations find growing reception in these regions.
- Thermo Fisher Scientific
- Danaher (Cytiva, Beckman Coulter)
- Sartorius
- Miltenyi Biotec
- Becton Dickinson & Co.
- Lonza Group
- Stem Cell Technologies
- Corning
- PerkinElmer
- Eppendorf
- Greiner Bio-One
- Eurofins
- Terumo
- Nipro
- Tomtec Inc.
- Alcami
- Esco Lifesciences
- PromoCell
- CellGenix
- Regen Lab SA
- PluriStem Therapeutics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Investment in Cell and Gene Therapies
- 4.2.2 Expansion of Biopharmaceutical Manufacturing Infrastructure
- 4.2.3 Rising Prevalence of Chronic Diseases Requiring Cell Therapies
- 4.2.4 Technological Advancements in Automated Cell Processing
- 4.2.5 Supportive Regulatory Frameworks for Advanced Therapies
- 4.2.6 Emergence of Personalized and Point-of-Care Cell Therapy Platforms
- 4.3 Market Restraints
- 4.3.1 Ethical and Regulatory Concerns Around Stem Cell Sourcing
- 4.3.2 High Cost of Automated Harvesting Systems
- 4.3.3 Variability and Quality Control Challenges in Donor-Derived Cells
- 4.3.4 Cold-Chain and Logistics Complexities for Live Cells
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers / Consumers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type of Cell Harvesting
- 5.1.1 Manual Cell Harvesters
- 5.1.2 Automated Cell Harvesters
- 5.2 By Application
- 5.2.1 Biopharmaceutical Application
- 5.2.2 Stem-Cell Research
- 5.2.3 Other Applications
- 5.3 By End User
- 5.3.1 Biotechnology & Biopharmaceutical Companies
- 5.3.2 Research Institutes
- 5.3.3 Other End Users
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Thermo Fisher Scientific
- 6.3.2 Danaher (Cytiva, Beckman Coulter)
- 6.3.3 Sartorius AG
- 6.3.4 Miltenyi Biotec
- 6.3.5 Becton Dickinson & Co.
- 6.3.6 Lonza Group
- 6.3.7 STEMCELL Technologies
- 6.3.8 Corning Inc.
- 6.3.9 PerkinElmer Inc.
- 6.3.10 Eppendorf SE
- 6.3.11 Greiner Bio-One
- 6.3.12 Eurofins Scientific
- 6.3.13 Terumo Corporation
- 6.3.14 Nipro Corporation
- 6.3.15 Tomtec Inc.
- 6.3.16 Alcami Corporation
- 6.3.17 Esco Lifesciences
- 6.3.18 PromoCell GmbH
- 6.3.19 CellGenix GmbH
- 6.3.20 Regen Lab SA
- 6.3.21 PluriStem Therapeutics
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


