|
시장보고서
상품코드
2122793
의료용 코팅 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Medical Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
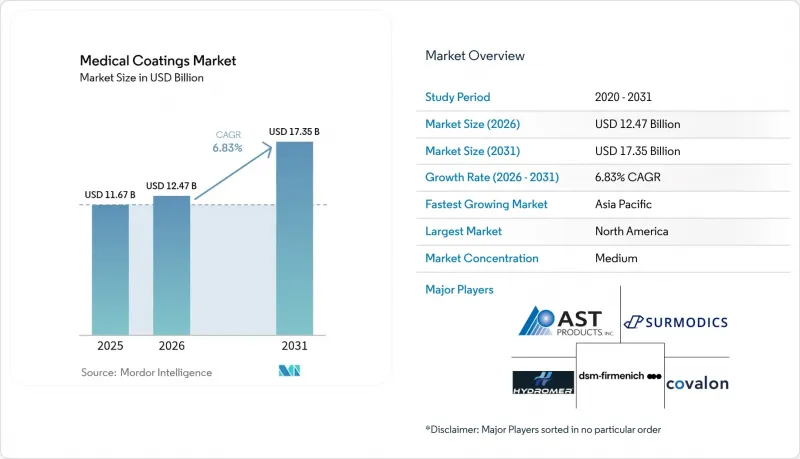
에 의하면, 의료용 코팅 시장 규모는 2025년에 116억 7,000만 달러로 평가되었고, 2026년 124억 7,000만 달러에서 2031년에는 173억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.83%를 나타낼 전망입니다.
본 보고서는 화학 조성별(실리콘, 불소수지 등), 코팅 기능 유형별(항균, 친수성/윤활성 등), 성막 기술별(화학기상증착법, 플라즈마 분사 등), 용도별(의료기기, 임플란트 등), 지역별(아시아태평양, 북미, 유럽, 남미 등)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 의료용 코팅 시장 동향 및 인사이트
첨단 의료 치료에 대한 인식 제고
의료 종사자들은 현재 표면 공학을, 수동적인 의료기기를 약물을 투여하고 생체 신호를 감지하며 감염을 예방하는 능동적인 치료 시스템으로 변혁시키는 수단으로 인식하고 있습니다. 정형외과 분야에서 항균 보호와 골유착 촉진을 동시에 실현하는 다기능 코팅은 이러한 변화를 상징하는 예입니다. 코팅이 적용된 임플란트의 재수술률이 낮다는 학술적 증거에 힘입어, 병원 측은 다소 높은 가격을 지불하는 것을 수용하고 있습니다. 한편, 의료기기 제조업체들은 원격 환자 모니터링을 가능하게 하는 센싱 층을 제품에 통합하고 있습니다.
일회용·저침습 기기의 급증
팬데믹 기간 동안의 감염 대책에서 얻은 교훈을 바탕으로 일회용 카테터 및 수술 기구로의 전환이 가속화되었습니다. 코팅 공급업체들은 재사용 가능한 기구의 멸균 부담을 해소하기 위해, 1회 사용을 전제로 한 비용 최적화된 친수성 마감을 제공함으로써 이에 대응했습니다. 외래수술센터(ASC)에서는 환자 회전율 향상과 교차 오염 위험 감소라는 이점을 얻을 수 있어, 코팅이 적용된 일회용 제품에 대한 수요 증가를 뒷받침하고 있습니다.
원자재 가격 변동
2024년 PTFE 공급 부족과 실리콘 전구체의 비용 급등으로 인해 많은 코팅 제조업체는 공급 계약 재협상을 할 수밖에 없었으며, 출하 지연과 가격 인상을 감수해야 했습니다. 헤지 능력이 부족한 중소 공급업체들은 수직 통합형 경쟁사들에게 시장 점유율을 빼앗겼습니다. 대기업들은 재고 완충을 통해 충격을 흡수했지만, 에너지 가격 변동이 지속되면서 투입 비용 예측은 여전히 어려운 상황입니다.
부문 분석
2025년, 파릴렌 코팅은 의료용 코팅 시장의 29.10%를 차지했습니다. 핀홀이 없는 컨포멀 코팅층은 신경 프로브, 심장 박동기, 마이크로플루이딕스 칩을 보호하며, 중요한 임플란트의 장기적인 신뢰성을 뒷받침하고 있습니다. 심혈관 분야와 신경 조절 분야에서는 수요가 안정적이지만, 원자재 부족과 성막 주기의 길이가 공급업체에 비용 압박을 가하고 있습니다. 불소 수지 솔루션은 카테터 시술에서 초저마찰에 대한 수요에 힘입어 연평균 성장률(CAGR) 7.32%라는 견실한 성장세를 보이고 있습니다. PFAS 규제에 대한 관심이 높아지면서 불확실성은 증가하고 있지만, 생명 유지 기기에 대한 의료 분야의 적용 예외가 예상되므로 전망은 유지되고 있습니다. 실리콘계 화학 물질은 엘라스토머 특성 덕분에 플렉서블 튜브나 상처 관리용 필름 분야에서 여전히 중요한 역할을 하고 있는 반면, 금속 이온 및 바이오 세라믹 코팅은 골유착(osseointegration)을 위한 고부가가치 틈새 시장을 차지하고 있습니다.
의료용 코팅 시장에서는 파릴렌 필름에 친수성 탑코트가 적용되거나, 불소계 폴리머 층에 항균 첨가제가 채택되는 등 배합 기술의 상호 융합이 진행되고 있습니다. 이러한 하이브리드 구조를 제공하는 공급업체들은 벤더 목록 축소를 목표로 하는 OEM 기업들과 다년 계약을 체결하고 있습니다. 원자층 증착법의 발전으로 파릴렌 위의 이산화티타늄 핵 형성을 옹스트롬 단위로 제어할 수 있게 되어, 배리어 성능이 향상되고 있습니다.
2025년에는 병원 측의 생물막 형성 억제 요청을 배경으로 항균층이 매출 점유율의 30.10%를 차지했습니다. 은 이온 및 항생제 코팅은 인공 관절과 중심정맥 카테터에서 지속적인 병원체 살균률을 보여주고 있어 의료기기의 안전성을 높이고 있습니다. 친수성·윤활성 코팅은 연평균 성장률(CAGR) 7.74%로 가장 빠른 성장을 보이고 있으며, 그 배경에는 복잡한 해부학적 구조 내를 원활하게 진행해야 하는 신경혈관 및 말초 중재 시술에 대한 수요가 있습니다.
항균성과 윤활성을 겸비한 다기능 제제가 주목받고 있으며, 특히 감염 예방과 쾌적성이 모두 중요한 요도 카테터 분야에서 두드러집니다. 항혈전성 화학 물질은 심혈관 이식편이나 심실 보조 장치 등의 용도에서 중요한 역할을 하고 있습니다. ‘기타’ 범주에 포함되는 약물 방출형 제품은 서방형 스텐트의 새로운 승인을 계기로 주목받고 있으나, 비용 문제가 중요한 심혈관 분야 이외에서의 광범위한 보급에 걸림돌이 되고 있습니다. OEM 업체들은 현재 마찰 계수, 로그 감쇠값, 세포 독성 점수 등의 성능 지표를 명시하고 있으며, 코팅 제조업체에 각 매개변수의 목표치 달성을 요구하고 있어 기술적 진입 장벽이 높아지고 있습니다.
지역별 분석
북미는 견실한 보험 환급 제도, 엄격한 FDA 승인 절차, 그리고 다국적 OEM 본사의 집중을 배경으로 2025년 매출의 34.10%를 차지하며 선두를 유지했습니다. 병원 구매 위원회는 CMS가 의무화한 감염 저감 지표를 지원하는 코팅을 중시하고 있으며, 이것이 항균제의 안정적인 판매량을 뒷받침하고 있습니다. 캐나다의 의료기기 수출 장려책과 멕시코의 수탁 제조 클러스터도 이 지역의 성장을 뒷받침하고 있습니다.
아시아태평양은 중국의 ‘중국 제조 2025’ 목표와 고령화에 따른 수술 건수 증가에 힘입어 연평균 성장률(CAGR) 8.78%로 가장 빠르게 성장하고 있습니다. 중국의 국내 제조업체들은 파릴렌 및 친수성 화학 물질을 통합함으로써 수입 의료기기와 성능 격차를 좁히고 있는 반면, 일본과 한국의 기업들은 센서가 내장된 임플란트 개발을 선도하고 있습니다. 인도 및 아세안 시장에서는 카테터 검사실 증가에 따라 기본적인 실리콘 코팅에서 마찰 감소 효과가 높은 첨단 불소 수지 코팅으로의 전환이 진행되고 있습니다.
유럽은 큰 수익원이 되고 있지만, PFAS(퍼플루오로알킬 물질)를 둘러싼 불확실성이 불소 수지의 미래를 불투명하게 만들고 있습니다. 그럼에도 불구하고, 독일의 정형외과 클러스터와 아일랜드의 수출 지향형 의료기기 공장은 플라즈마 및 CVD(화학적 기상 증착) 라인에 대한 투자를 유지하고 있습니다. 남미와 중동 및 아프리카는 여전히 발전 단계에 있지만, 미래 전망은 밝다고 할 수 있습니다. 브라질의 임플란트 공장 대상 세제 혜택과 사우디아라비아의 ‘비전 2030’에 따른 의료 인프라 확충으로 인해, 코팅이 적용된 정형외과 및 심혈관용 제품에 대한 수요가 증가하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the medical coatings market size was valued at USD 11.67 billion in 2025 and estimated to grow from USD 12.47 billion in 2026 to reach USD 17.35 billion by 2031, at a CAGR of 6.83% during the forecast period (2026-2031).
This report is Segmented by Chemistry (Silicone, Fluoropolymer, and More), Coating Function Type (Antimicrobial, Hydrophilic/Lubricious, and More), Deposition Technology (Chemical Vapor Deposition, Plasma Spray, and More), Application (Medical Device, Implants, and More), and Geography (Asia-Pacific, North America, Europe, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Coatings Market Trends and Insights
Growing Awareness of Advanced Medical Treatments
Healthcare practitioners now view surface engineering as a pathway to transform passive devices into active therapeutic systems that deliver drugs, sense biological signals and resist infection. Multifunctional coatings that simultaneously provide antimicrobial protection and bone-integration support in orthopedics exemplify this shift. Academic evidence demonstrating lower revision rates in coated implants is convincing hospitals to pay premium prices, while device makers integrate sensing layers that enable remote patient monitoring.
Surge in Single-Use, Minimally Invasive Devices
Pandemic-era infection-control lessons accelerated the pivot to disposable catheters and surgical tools. Coating suppliers responded with cost-optimized hydrophilic finishes designed for one-time use, eliminating the sterilization burden of re-usable instruments. Ambulatory centers benefit through faster turnover and reduced cross-contamination risk, supporting volume growth in coated disposables.
Raw-Material Price Volatility
Shortages of PTFE and spikes in silicone precursor costs in 2024 forced many coaters to renegotiate supply contracts, delay shipments and raise prices. Smaller providers lacking hedging capacity lost share to vertically integrated rivals. Although larger players absorbed shocks through inventory buffers, persistent energy-price swings keep input costs unpredictable.
Other drivers and restraints analyzed in the detailed report include:
- Stricter HAI Regulations Boosting Antimicrobial Uptake
- Venture Funding in Smart Implants
- Fragmented Regulatory Pathways for Nanocoatings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Parylene coatings represented 29.10% of the medical coatings market in 2025. Their pin-hole-free conformal layers protect neural probes, pacemakers and microfluidic chips, underpinning long-term trust in critical implants. Demand remains stable in cardiology and neuromodulation, yet raw material scarcity and deposition cycle length put cost pressure on suppliers. Fluoropolymer solutions are experiencing a robust growth rate of 7.32% CAGR, driven by the demand for ultra-low friction in catheter procedures. Regulatory focus on PFAS limits heightens uncertainty, but healthcare exemptions expected for life-saving devices preserve outlook. Silicone-based chemistries retain relevance in flexible tubing and wound-care films due to elastomeric properties, while metal-ion and bioceramic coatings inhabit high-value niches for osseointegration.
The medical coatings market is witnessing formulation cross-pollination whereby parylene films gain hydrophilic top-coats and fluoropolymer layers adopt antimicrobial additives. Suppliers offering such hybrid stacks secure multi-year contracts with OEMs looking to shrink vendor lists. Advancements in atomic layer deposition allow angstrom-level control of titanium oxide nucleation on parylene, boosting barrier performance.
Antimicrobial layers accounted for 30.10% of the revenue share in 2025, driven by hospital mandates to curb biofilm formation. Silver-ion and antibiotic coatings demonstrate sustained pathogen-kill rates in joint replacements and central-line catheters, enhancing device safety. Hydrophilic/lubricious finishes are experiencing the fastest growth at a 7.74% CAGR, powered by neurovascular and peripheral interventions that require smooth navigation through tortuous anatomy.
Multi-effect formulations that merge antimicrobial and lubricious traits stand out, particularly for urinary catheters where infection and comfort both matter. Anti-thrombogenic chemistries play a significant role in applications such as cardiovascular grafts and ventricular assist devices. Drug-eluting options in the "Others" basket gain traction as controlled-release stents receive new approvals, yet cost remains a barrier to widespread uptake outside critical cardiovascular segments. OEMs now specify performance dashboards-coefficient of friction, log-reduction values, cytotoxicity scores-and expect coaters to meet targets across parameters, raising technical entry hurdles.
Complete Report Scope:
- By Chemistry
- Silicone
- Fluoropolymer
- Parylene
- Others (Metal-based (Ti, Ag, Au), Bio ceramics)
- By Coating Function Type
- Antimicrobial
- Hydrophilic/Lubricious
- Anti-thrombogenic/Hemocompatible
- Others (Drug-eluting, Radiopaque)
- By Deposition Technology
- Chemical Vapor Deposition (CVD)
- Plasma Spray
- Dip and Spray
- Others
- By Application
- Medical Device
- Implants (Orthopedic, Cardiovascular, Dental)
- Surgical Instruments and Tools
- Others
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America retained the top spot with 34.10% of 2025 revenue, underpinned by robust reimbursement, rigorous FDA pathways and a concentration of multinational OEM headquarters. Hospital purchasing committees emphasize coatings that support infection-reduction metrics mandated by CMS, anchoring steady antimicrobial volumes. Canada's device export incentives and Mexico's contract-manufacturing clusters also stimulate regional growth.
Asia Pacific is the fastest mover at an 8.78% CAGR, driven by China's Made in China 2025 targets and rising procedure rates among aging populations. Domestic Chinese manufacturers integrate parylene and hydrophilic chemistries to close performance gaps with imported devices, while Japanese and South Korean firms pioneer sensor-integrated implants. India and ASEAN markets progress from basic silicone coatings toward advanced fluoropolymer friction-reduction as catheter labs proliferate.
Europe contributes a sizeable revenue pool but faces PFAS uncertainty that clouds fluoropolymer futures. Nonetheless, Germany's orthopedic clusters and Ireland's export-oriented device plants sustain investment in plasma and CVD lines. South America and the Middle East & Africa remain nascent yet promising; Brazil's tax incentives for implant factories and Saudi Arabia's Vision 2030 healthcare build-out elevate demand for coated orthopedic and cardiovascular products.
- Abbott Laboratories - St. Jude Coatings
- AST Products, Inc.
- Axalta Coating Systems
- Biocoat, Inc.
- Covalon Technologies Ltd.
- DSM
- Freudenberg Medical
- Harland Medical Systems
- Hydromer, Inc.
- Medicoat AG
- Merit Medical Systems
- Momentive Performance Materials
- PPG Industries
- Precision Coating Co.
- Surmodics, Inc.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Awareness Regarding Advancement of Medical Treatments
- 4.2.2 Sharp rise in single-use, minimally-invasive devices post-pandemic
- 4.2.3 Stricter HAIs regulations driving antimicrobial adoption
- 4.2.4 Surge in ambulatory surgical centers requiring low-friction coatings
- 4.2.5 Venture funding into smart implant start-ups
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility (silicones, parylene dimers)
- 4.3.2 Complex, fragmented regulatory pathways for nanocoatings
- 4.3.3 Supply-chain risks for specialty fluoropolymers
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Chemistry
- 5.1.1 Silicone
- 5.1.2 Fluoropolymer
- 5.1.3 Parylene
- 5.1.4 Others (Metal-based (Ti, Ag, Au), Bio ceramics)
- 5.2 By Coating Function Type
- 5.2.1 Antimicrobial
- 5.2.2 Hydrophilic/Lubricious
- 5.2.3 Anti-thrombogenic/Hemocompatible
- 5.2.4 Others (Drug-eluting, Radiopaque)
- 5.3 By Deposition Technology
- 5.3.1 Chemical Vapor Deposition (CVD)
- 5.3.2 Plasma Spray
- 5.3.3 Dip and Spray
- 5.3.4 Others
- 5.4 By Application
- 5.4.1 Medical Device
- 5.4.2 Implants (Orthopedic, Cardiovascular, Dental)
- 5.4.3 Surgical Instruments and Tools
- 5.4.4 Others
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 NORDIC Countries
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Abbott Laboratories - St. Jude Coatings
- 6.4.2 AST Products, Inc.
- 6.4.3 Axalta Coating Systems
- 6.4.4 Biocoat, Inc.
- 6.4.5 Covalon Technologies Ltd.
- 6.4.6 DSM
- 6.4.7 Freudenberg Medical
- 6.4.8 Harland Medical Systems
- 6.4.9 Hydromer, Inc.
- 6.4.10 Medicoat AG
- 6.4.11 Merit Medical Systems
- 6.4.12 Momentive Performance Materials
- 6.4.13 PPG Industries
- 6.4.14 Precision Coating Co.
- 6.4.15 Surmodics, Inc.
- 6.4.16 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment