

|
시장보고서
상품코드
2122825
극저온 밸브 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cryogenic Valves - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 극저온 밸브 시장 규모는 2025년에 32억 7,000만 달러로 평가되었고, 2026년 34억 1,000만 달러에서 2031년까지 41억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.24%를 나타낼 전망입니다.
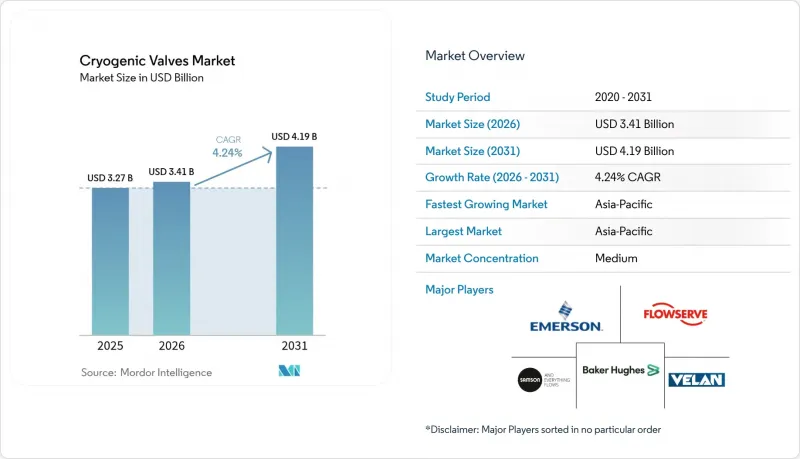
본 보고서는 제품 유형별(볼 밸브, 게이트 밸브, 글로브 밸브, 체크 밸브, 기타 제품 유형), 작동 방식별(수동, 공압, 전동), 가스별(액체 질소, 액화천연가스 등), 최종 사용자 산업별(석유 및 가스,에너지 및 전력, 화학, 기타), 지역별(아시아태평양, 북미, 유럽, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 극저온 밸브 시장 동향 및 인사이트
LNG 인프라 투자 증가
2024-2028년 예정된 확장으로 인해 전 세계 LNG 액화 능력은 40% 증가할 전망입니다. 이에 따라 미국이 카타르를 제치고 최대 수출국이 될 것이며, 아시아태평양이 신규 화물의 대부분을 구매하게 될 것입니다. 베이커 휴즈(Baker Hughes)는 루이지애나주의 2개 생산 라인을 대상으로 56억 달러 상당의 LNG 설비 수주를 확보했으며, 이는 초저누설 성능을 보장할 수 있는 현장 실적이 입증된 밸브 파트너에 대한 계약업체 수요가 높음을 보여줍니다. 선박용 벙커링 수요는 2030년까지 연간 1,600만 톤을 넘어설 것으로 예측되며, 이에 따라 각 항만에서는 비상 차단 밸브가 통합된 자동 극저온 이송 장치의 도입이 진행되고 있습니다. 엔터프라이즈 프로덕츠 파트너스는 휴스턴 선박 수로의 냉동 용량을 하루 30만 배럴 확대하고 있으며, 이에 따라 -162°C까지 견딜 수 있는 트리플 오프셋식 스톱 밸브에 대한 신규 수주가 발생하고 있습니다. 사우디 아람코의 77억 달러 규모의 파딜리 업그레이드 계획에서는 스위트 가스 처리 능력이 하루 13억 입방피트 증가하며, 각 트레인에는 혼합 냉매에 대응하기 위한 중복 극저온 유로가 장착됩니다.
산업용 가스 수요 증가
텍사스주에 위치한 에어 리키드(Air Liquide)사의 4기 모듈식 공기 분리 장치는 엑슨모빌(ExxonMobil)사의 저탄소 수소 복합 시설에 하루 9,000톤의 산소를 공급하는 동시에 북미 대륙 최대 규모의 아르곤 공급원이 되어, 산소 용도 인증을 취득할 수 있는 밸브 제조업체에 장기적인 수요를 창출하고 있습니다. 의료 분야의 확대에 따라 액체 산소 소비량은 계속 증가하고 있으며, 병원에서는 환자용 회로 내의 입자 탈락을 방지하는 밸브 설계가 의무화되어 있습니다. 식품 가공업체에서는 급속 냉동을 위해 액체 질소 터널이 선호되고 있으며, 위생적인 마무리를 유지하면서 -196°C까지의 급격한 온도 변화를 견딜 수 있는 밸브가 요구되고 있습니다. 재생에너지로 가동되는 공기 분리 플랜트에서는 변동하는 전력 요금에 맞추어 출력을 조절할 수 있도록 반응성이 빠른 제어 트림이 요구되고 있습니다.
안전성 및 규정 준수의 복잡성
ASME B31.3 규격에서는 -425°F 이하의 환경에서 충격 시험을 통과한 재료의 사용이 의무화되어 있습니다. 이 규격을 준수하는 밸브에는 샤르피 시험을 통해 검증된 오스테나이트계 스테인리스 스틸 또는 알루미늄 합금이 사용됩니다. 2025년 ASME VIII 개정판에서는 새로운 극저온 사례가 도입되어, 설계자는 새로운 규정을 충족하기 위해 더 두꺼운 보닛이나 벨로우즈 씰을 추가해야 합니다. MSS SP-158-2021에서는 고압 가스 시험이 의무화되어 있어 개발 비용 증가로 이어지지만, 정전 위험을 줄이기 위해 유틸리티자들은 이 인증을 점점 더 강력하게 요구하고 있습니다. 미국 연방 규정집(49 CFR)에서는 밸브가 누출 없이 탱크의 시험 압력을 유지해야 하고, 기계적 손상에 대한 견고한 보호 장치를 갖추어야 한다고 규정하고 있어, 이는 트레일러의 레이아웃 선택에 영향을 미치고 있습니다. 안전 밸브의 5년 주기 재인증은 지속적인 서비스 수익을 창출하는 한편, 소규모 사업자에게는 소유 비용 증가로 이어지고 있습니다. 소규모 제조업체들은 여러 관할 구역에 걸친 규격 준수를 따라잡는 데 어려움을 겪고 있으며, 이로 인해 유서 깊은 브랜드들이 경쟁 우위를 점하고 있습니다.
부문 분석
볼 밸브는 입증된 확실한 차단 성능과 간편한 유지보수 덕분에 2025년 극저온 밸브 시장에서 33.74%라는 압도적인 점유율을 차지했습니다. 각 제조업체는 끓는 액화 가스로부터 시트를 격리하는 연장 스템 설계를 채택하여, 이로 인해 얼음 축적 및 시트 손상을 줄이고 있습니다. 에머슨의 피셔 HP 시리즈는 스프링식 PTFE 링을 채택하여 -198°C에서 클래스 VI 차단 성능을 유지하고 있습니다. 글로브 밸브는 도입 대수는 적지만, 수소 액화 프로젝트에서 그 정밀한 유량 조절 능력이 높이 평가되고 있어 연평균 성장률(CAGR) 5.18%를 나타낼 것으로 예측됩니다. 글로브 밸브의 극저온 밸브 시장 규모는 8-10 t/h의 액체 수소를 생산하는 파일럿 플랜트에서 현저히 확대될 것으로 전망되며, 각 플랜트에서는 오르토-파라 전환 열을 관리하기 위한 가변 유량 제어가 요구되고 있습니다.
두 유형 모두 기술적 개선이 계속되고 있습니다. 볼 밸브 제조업체는 초저수준의 누출 배출을 실현하는 ISO 15848-1 클래스 A 인증을 받은 흑연제 보닛 씰을 채택하고 있으며, 이는 ESG 크레딧 획득을 목표로 하는 사업자에게 중요한 요소가 되고 있습니다. 글로브 밸브 OEM 제조업체는 등백분율 특성을 발휘하는 성형 플러그를 채택하여 다단식 팽창기에서의 공정 안정성을 향상시키고 있습니다. 게이트 밸브와 체크 밸브는 틈새 용도를 유지하고 있습니다. 게이트 밸브는 최대 42인치 풀보어 LNG 적재 라인을 지원하며, 듀얼 플레이트식 극저온 체크 밸브는 보일오프 가스 재순환 루프에서 역서지를 방지합니다. 특수한 버터플라이 밸브와 플러그 밸브는 극히 낮은 토크가 필수적인 초저밀도 헬륨 용도 등 시장의 틈새를 메우고 있습니다.
2025년 현재, 수동 기어식 및 핸드휠식 조작 장치가 극저온 밸브 시장의 59.10%를 차지했으며, 그 간편함과 정전 시 고유한 페일세이프 기능이 높이 평가받고 있습니다. LNG 수출 터미널에서는 부두 측에서 비상 상황이 발생했을 때 화물 라인을 확실하게 차단하기 위해 수동 차단 밸브가 채택되고 있습니다. 그러나 시설 소유자가 인력 감축을 위해 원격 조작으로의 전환을 추진하고 있어, 이 부문의 성장은 완만합니다. 공압식 액추에이터는 2031년까지 연평균 성장률(CAGR) 5.33%로 확대될 것으로 예상되며, 플랜트 에어 또는 질소를 이용하여 ‘페일 클로즈(고장 시 폐쇄)’ 로직 하에서 신속한 스트로크를 실현합니다. 수소 관련 시설에서는 전기 모터에 따른 발화 위험을 피하기 위해 공압식 구동이 선호되고 있습니다.
전동 액추에이터는 제품의 식감을 유지하기 위해 유량을 미세 조정하는 디지털로 제어되는 질소 냉동 터널 등, 풍부한 위치 피드백이 필수적인 틈새 분야에서 채택이 진행되고 있습니다. 공압 구동 장치에 클러치 해제 가능한 기어박스를 통합한 하이브리드 솔루션은 수동 오버라이드와 자동 속도 제어를 결합하여 이중 용도 설비에서 수요를 흡수하고 있습니다. OEM 업체들은 스템의 마찰이나 사이클 횟수를 측정하는 스마트 포지셔너를 탑재하는 사례가 증가하고 있으며, 이 데이터는 플랜트의 히스토리안으로 전송되어 누출이 발생하기 전에 유지보수 작업 지시를 발동시킵니다. 이러한 예측 유지보수 모델은 애프터마켓과의 연계성을 강화하고, 설치된 밸브 1대당 수명 주기 수익을 향상시킵니다.
지역별 분석
아시아태평양은 2025년에 극저온 밸브 시장의 26.10%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 5.48%로 확대될 것으로 전망됩니다. 중국의 ‘가스 투 파워(Gas-to-Power)’ 정책 전환과 인도의 폭염으로 인한 수요 증가가 수입 증가세를 회복시키고 있는 반면, 일본과 한국은 미국산 화물을 환적하는 허브 시설에 대한 투자를 추진하고 있습니다. 호주에서는 노후화된 액화 플랜트가 개보수 주기에 접어들면서 애프터마켓 밸브 서비스 수요를 끌어올리고 있습니다. 중국, 한국, 호주의 정부 수소 로드맵에 따라 시범 액화 플랜트에서 고압 글로브 밸브에 대한 신규 입찰이 증가하고 있습니다.
북미에서는 미국이 세계 최대의 LNG 수출국이 된 점과 수소 허브에 대한 연방 정부의 적극적인 자금 지원의 혜택을 받고 있습니다. 멕시코만 연안의 브라운필드형 액화 프로젝트에서는 북미 밸브 제조업체 협회(NAVMA) 회원 자격이 요건으로 규정되어 있어, 현지 재고를 보유한 국내 공급업체가 우대받고 있습니다. 에어 리퀴드(Air Liquide)사의 베이타운(Baytown) 투자에 더해, 여러 중규모 액체 산소 건설 및 소유 프로젝트로 인해 산업용 가스 밸브 수요는 견조한 추세를 보이고 있습니다. 2027년에 브리티시컬럼비아주에서 선적이 예정된 캐나다 최초의 LNG는 서반구 수요를 더욱 끌어올릴 것입니다.
유럽에서는 2024년 LNG 수입이 둔화되었지만, 수소 관련 사업을 강력히 추진하고 있습니다. 독일이 계획 중인 10GW 규모의 전해조 용량은 액화 및 지하 저장 계획과 연계되어 있으며, 두 계획 모두 초저누출 차단 밸브가 지정되어 있습니다. ‘호라이즌 유럽(Horizon Europe)’은 스페인과 네덜란드 간 이동식 LH2 탱크의 시범 운영에 자금을 지원하고 있으며, 이를 통해 특수 화물 취급용 밸브 수주가 발생하고 있습니다. 북유럽 항만에서는 그린 코리도(Green Corridor) 해운 동맹을 지원하기 위해 LNG 벙커링 도입이 가속화되고 있습니다.
중동 및 아프리카에서는 대규모 신규 가스 처리 프로젝트가 진행되고 있습니다. 사우디아람코의 파딜리 확장 계획, 카타르의 노스 필드 사우스, 그리고 오만의 여러 석유화학 복합 시설에서는 사워 가스 화합물을 견딜 수 있는 내구성이 뛰어난 극저온용 금속 재료가 요구되고 있습니다. 아부다비에서는 블루 암모니아 개발이 진행 중이며, LNG 플랜트의 설계 개념이 밸브 패키지에도 적용될 전망입니다. 아프리카에서는 모잠비크의 육상 LNG 플랜트 건설이 연기되고 있지만, 치안이 안정되면 새로운 밸브 조달 사이클이 예상됩니다.
남미는 여전히 발전 단계에 있지만, 장래성은 높습니다. 브라질은 계절적인 가스 부족에 대처하기 위해 부유식 저장·재기화 설비(FSRU) 도입을 검토하고 있으며, 이를 위해서는 소형 극저온 밸브 스키드가 필요합니다. 아르헨티나의 바카 무에르타 셰일가스전은 장래에 LNG 수출 바지선 프로젝트공급원이 될 가능성이 있지만, 일정이 불투명하여 단기적인 수요는 소폭에 그칠 전망입니다. 칠레의 광업 부문에서는 공정 효율 향상을 위해 액체 산소 도입이 검토되고 있어, 규모는 작지만 수익성이 높은 밸브 수요가 예상됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the cryogenic valves market size was valued at USD 3.27 billion in 2025 and estimated to grow from USD 3.41 billion in 2026 to reach USD 4.19 billion by 2031, at a CAGR of 4.24% during the forecast period (2026-2031).
This report is Segmented by Product Type (Ball Valve, Gate Valve, Globe Valve, Check Valve, Other Product Types), Actuation (Manual, Pneumatic, Electric), Gas (Liquid Nitrogen, Liquid Natural Gas, and More), End-User Industry (Oil and Gas, Energy and Power, Chemicals, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cryogenic Valves Market Trends and Insights
Rising LNG Infrastructure Investments
Expansions slated between 2024-2028 will lift global LNG liquefaction capacity by 40%, with the United States overtaking Qatar as lead exporter while Asia-Pacific purchases the bulk of incremental cargoes. Baker Hughes secured USD 5.6 billion of LNG equipment awards for two Louisiana trains, illustrating contractor appetite for field-proven valve partners able to guarantee ultra-low-leak performance. Marine bunkering demand is forecast to exceed 16 million t annually by 2030, prompting ports to specify automated cryogenic transfer assemblies that integrate emergency shut-off valves. Enterprise Products Partners is expanding Houston Ship Channel refrigeration capacity by 300,000 bbl/d, creating new orders for triple-offset stop-valves rated down to -162 °C. Saudi Aramco's USD 7.7 billion Fadhili upgrade will add 1.3 Bcf/d of sweet-gas processing, each train fitted with redundant cryogenic flow-paths to handle mixed refrigerants.
Growth in Industrial Gas Demand
Air Liquide's four modular air-separation units in Texas will deliver 9,000 t/d of oxygen to ExxonMobil's low-carbon hydrogen complex and generate the continent's largest argon stream, placing long-cycle demand on valve makers able to certify for oxygen service. Healthcare expansion keeps liquid-oxygen consumption rising, and hospitals mandate valve designs that prevent particle shedding in patient circuits. Food processors favour liquid nitrogen tunnels for flash-freezing, with valves that tolerate rapid thermal cycling down to -196 °C while maintaining hygienic finishes. Renewable-powered air-separation plants require fast-response control trim so operators can throttle output to match fluctuating grid tariffs.
Safety & Compliance Complexities
ASME B31.3 mandates impact-tested materials below -425 °F; complying valves use austenitic stainless or aluminium alloys proven by Charpy testing. The 2025 ASME VIII update introduces fresh cryogenic case studies, prompting designers to add thicker bonnets or bellows seals to satisfy the new rules. MSS SP-158-2021 requires high-pressure gas tests that inflate development costs, yet utilities increasingly insist on the certification to reduce outage risk. U.S. Code 49 CFR obliges valves to hold tank test pressure without seepage and to include robust guards against mechanical damage, shaping layout choices on trailers. Five-year recertification cycles for safety valves generate recurring service revenue but raise ownership costs for small operators. Smaller fabricators struggle to keep pace with multi-jurisdiction code work, giving established brands a competitive edge.
Other drivers and restraints analyzed in the detailed report include:
- Hydrogen-Economy Project Pipeline Acceleration
- Capacity Additions in Petro-chem & Specialty Gas Plants
- Stainless-Steel & Nickel Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ball valves held a dominant 33.74% cryogenic valves market share in 2025, owing to proven tight shut-off and straightforward maintenance. Manufacturers supply extended-stem designs that isolate the seat from boiling liquefied gases, cutting ice buildup and seat damage. Emerson's Fisher HP series uses spring-energised PTFE rings to hold Class VI shut-off at -198 °C. Globe valves, though smaller in installed base, are expected to grow at 5.18% CAGR as hydrogen liquefaction projects favour their throttling precision. The cryogenic valves market size for globe valves is anticipated to widen notably in pilot plants producing 8-10 t/h of liquid hydrogen, each calling for variable-flow control to manage ortho-para conversion heat.
Technical enhancements continue across both lines. Ball-valve makers are adding graphite bonnet seals certified to ISO 15848-1 Class A for ultra-low fugitive emissions, an important factor for operators seeking ESG credits. Globe-valve OEMs are deploying contoured plugs that deliver equal-percentage characteristics, enhancing process stability in multi-stage expanders. Gate and check valves retain niche uses: gate valves accommodate full-bore LNG loading lines up to 42 in, while dual-plate cryogenic check valves prevent reverse surge in boil-off gas recirculation loops. Specialty butterfly and plug valves fill gaps such as helium service at ultra-low density where very low torque is essential.
Manual gear and hand-wheel operators represented 59.10% of the cryogenic valves market in 2025, prized for simplicity and intrinsic fail-safe capability during power loss. LNG export terminals rely on manual isolation valves to secure cargo lines during berth-side emergencies. The segment, however, grows slowly as facility owners look to remote operation to cut staffing. Pneumatic actuation will expand at 5.33% CAGR to 2031, leveraging plant air or nitrogen to deliver quick stroke times under fail-closed logic. Hydrogen sites favour pneumatic drives to avoid ignition risks linked to electric motors.
Electric actuators achieve niche uptake where data-rich position feedback is essential, such as in digitally managed nitrogen freezing tunnels that fine-tune flow to maintain product texture. Hybrid solutions that bolt a declutchable gearbox onto a pneumatic drive combine manual override with automated speed, capturing demand in dual-use installations. OEMs increasingly embed smart positioners measuring stem friction and cycle count, feeding plant historians that trigger service work orders before leakage occurs. This predictive-maintenance model strengthens aftermarket ties and lifts lifetime revenue per installed valve.
Complete Report Scope:
- By Product Type
- Ball Valve
- Gate Valve
- Globe Valve
- Check Valve
- Other Product Types
- By Actuation
- Manual
- Pneumatic
- Electric
- By Gas
- Liquid Nitrogen
- Liquid Natural Gas
- Hydrogen
- Oxygen
- Other Gases
- By End-user Industry
- Oil and Gas
- Energy and Power
- Chemicals
- Food and Beverage
- Medical
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific controlled 26.10% of the cryogenic valves market in 2025 and is projected to expand by a 5.48% CAGR through 2031. China's gas-to-power policy reversal and India's heat-wave-driven demand are reviving import growth, while Japan and South Korea invest in re-loading hubs that reposition cargoes from the United States. Australia's ageing liquefaction trains enter refurbishment cycles, pushing aftermarket valve services. Government hydrogen roadmaps in China, South Korea and Australia create incremental bids for high-pressure globe valves at pilot liquefier sites.
North America benefits from the United States becoming the world's largest LNG exporter and from aggressive federal funding for hydrogen hubs. Gulf Coast brownfield liquefaction projects stipulate North American Valve Manufacturers Association membership, favouring domestic suppliers with local inventories. Air Liquide's Baytown investment plus multiple mid-scale liquid-oxygen build-owns maintain steady industrial-gas valve uptake. Canada's first LNG shipment slated for 2027 from British Columbia will add western-hemisphere demand.
Europe, despite softer LNG imports in 2024, commits heavily to hydrogen. Germany's planned 10 GW of electrolyser capacity links to liquefaction and underground storage schemes, each specifying ultra-low-leak isolation valves. Horizon Europe funds mobile LH2 tank trials between Spain and the Netherlands, generating specialty cargo-handling valve orders. Nordic ports accelerate LNG bunkering roll-outs supporting green-corridor shipping alliances.
The Middle East and Africa witness sizeable greenfield gas processing. Saudi Aramco's Fadhili expansion, Qatar's North Field South and multiple Omani petro-chem complexes need durable cryogenic metallurgy that resists sour-gas compounds. Abu Dhabi is exploring blue-ammonia, which will import design philosophies from LNG trains to valve packages. In Africa, Mozambique's postponed onshore LNG plant, once security stabilises, promises a fresh cycle of valve procurement.
South America remains nascent yet promising. Brazil eyes floating storage and regasification units to manage seasonal gas deficits, requiring compact cryogenic valve skids. Argentina's Vaca Muerta shale may eventually feed LNG export barge projects, though timetable uncertainty tempers near-term demand. Chile's mining sector investigates liquid oxygen for process efficiency, presenting small but high-margin valve prospects.
- BAC Valves
- Baker Hughes
- Bray International
- Burkert India Private Limited
- Cryofab Inc.
- Emerson Electric Co.
- Flowserve Corporation
- Habonim
- HEROSE GmbH
- L&T Valves Limited
- Meca-Inox
- Neway Valve
- OPW, A Dover Company
- Parker Hannifin Corp
- Powell Valves
- Samson AG
- Swagelok Company
- Velan
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising LNG infrastructure investments
- 4.2.2 Growth in industrial gas demand
- 4.2.3 Hydrogen-economy project pipeline acceleration
- 4.2.4 Capacity additions in petro-chem & specialty gas plants
- 4.2.5 Small-scale LNG bunkering at global ports
- 4.3 Market Restraints
- 4.3.1 Safety & compliance complexities
- 4.3.2 Stainless-steel & nickel price volatility
- 4.3.3 Supply-chain gaps in vacuum-brazed components
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Ball Valve
- 5.1.2 Gate Valve
- 5.1.3 Globe Valve
- 5.1.4 Check Valve
- 5.1.5 Other Product Types
- 5.2 By Actuation
- 5.2.1 Manual
- 5.2.2 Pneumatic
- 5.2.3 Electric
- 5.3 By Gas
- 5.3.1 Liquid Nitrogen
- 5.3.2 Liquid Natural Gas
- 5.3.3 Hydrogen
- 5.3.4 Oxygen
- 5.3.5 Other Gases
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Energy and Power
- 5.4.3 Chemicals
- 5.4.4 Food and Beverage
- 5.4.5 Medical
- 5.4.6 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Italy
- 5.5.3.4 France
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration Analysis
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 BAC Valves
- 6.4.2 Baker Hughes
- 6.4.3 Bray International
- 6.4.4 Burkert India Private Limited
- 6.4.5 Cryofab Inc.
- 6.4.6 Emerson Electric Co.
- 6.4.7 Flowserve Corporation
- 6.4.8 Habonim
- 6.4.9 HEROSE GmbH
- 6.4.10 L&T Valves Limited
- 6.4.11 Meca-Inox
- 6.4.12 Neway Valve
- 6.4.13 OPW, A Dover Company
- 6.4.14 Parker Hannifin Corp
- 6.4.15 Powell Valves
- 6.4.16 Samson AG
- 6.4.17 Swagelok Company
- 6.4.18 Velan
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


