|
시장보고서
상품코드
2122833
주차 관리 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Parking Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
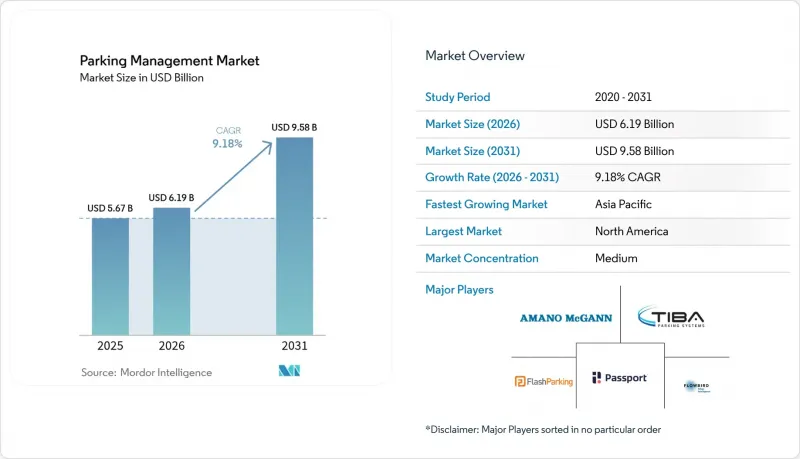
에 의하면, 주차 관리 시장 규모는 2025년에 56억 7,000만 달러로 평가되었고, 2026년에는 61억 9,000만 달러로 추정되고, 2031년까지 95억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.18%를 나타낼 전망입니다.
본 보고서는 도입 모델별(온프레미스 및 클라우드 기반), 주차장 유형별(노외 주차장, 노상 주차장), 솔루션 구성 요소별(하드웨어, 소프트웨어 플랫폼, 서비스), 최종 사용자 업종별(지자체·정부 기관, 상업용 노외 주차장 운영 사업자 등), 기술별(센서 기반, 카메라/LPR 기반 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 주차 관리 시장 동향 및 인사이트
도시 지역 교통 정체 완화
동적인 노상 관리 프로그램은 주차 관리가 차량의 배회 및 온실가스 배출을 어떻게 줄일 수 있는지 보여줍니다. 샌프란시스코의 ‘SF Park’는 85%의 가동률을 유지하기 위해 6주마다 요금을 재조정하고 있으며, 시범 구역 내에서 주차 공간을 찾는 차량으로 인한 교통량이 30% 감소한 것으로 입증되었습니다. 포틀랜드와 호보켄의 유사한 센서 기반 도입 사례는 독자적인 조사를 수행할 자원이 부족한 중규모 도시에 적용 가능한 성공 사례를 보여주고 있습니다. 지자체 기관은 현재 대중교통 운행 정보와 함께 주차 API를 활용하고 있으며, 이를 통해 내비게이션 앱이 운전자를 실시간으로 가장 저렴한 주차 공간으로 안내할 수 있게 되었습니다. 이러한 접근 방식을 통해 주차 요금은 단순한 고정 세금에서 피크 시간대의 교통 부하를 재조정하는 행동 변화를 유도하는 수단으로 그 위상이 재정의되고 있습니다. 로스앤젤레스와 싱가포르에서 제기되고 있는 혼잡통행료 제도 제안은 주차 데이터를 규제 집행의 기반으로 삼아 그 역할을 더욱 중요하게 만들고 있습니다.
지능형 교통 시스템(ITS)을 위한 스마트 시티 자금
연방 정부 및 초국가적 기관의 전용 보조금을 통해 자금 조달에 어려움을 겪는 지자체의 도입 위험이 완화되고 있습니다. 미국에서는 연방 고속도로청이 2026년까지 23억 달러를 5G 지원 도로 및 주차 시스템에 배정하고 있으며, 이 자금의 지급은 개방형 아키텍처와 사이버 보안 기준 준수를 조건으로 하고 있습니다. 유럽의 도시들에서는 ‘호라이즌 유럽(Horizon Europe)’ 자금을 활용하여, 도로변 전기차 충전과 자동 주차 유도를 결합한 실증 실험을 진행하고 있습니다. 장기적인 자금 조달을 통해 주차장의 가동 상황, 신호등 타이밍, 대중교통 도착 시각 등의 데이터를 단일 도시 모빌리티 대시보드에 통합하는 여러 기관에 걸친 프로젝트가 실현되고 있습니다. 적격 기준으로 상호 운용성이 요구되므로, 표준화된 API를 지원하는 공급업체는 입찰 평가에서 구조적인 우위를 점할 수 있습니다.
사이버 보안 및 데이터 개인정보 보호의 취약점
2024년 4월 이후 PCI-DSS 4.0으로의 전환이 의무화됨에 따라, 10년 전의 컨트롤러를 여전히 가동하고 있는 시설의 보안 취약점이 드러났습니다. 캘리포니아주와 네덜란드에서 발생한 차량 번호판 데이터베이스 무단 접근 사건은 대중의 감시를 강화시켰고, 규제 당국이 감사 범위를 확대하여 익명화 프로토콜을 포함하도록 촉구했습니다. 대형 플랫폼들은 제로 트러스트 아키텍처 도입 및 전문 보안 기업과의 제휴를 통해 이에 대응했으나, 소규모 주차장 운영사들은 지속적인 침투 테스트 비용을 마련하는 데 어려움을 겪고 있습니다. EU가 제안한 도로변 관리 데이터를 ‘고위험 AI 처리’로 분류하는 안건이 통과되면, 알고리즘 투명성에 관한 요건이 추가되어 규정 준수 예산에 추가적인 부담이 가중될 가능성이 있습니다.
부문 분석
온프레미스형 시스템을 활용한 주차 관리 시장 규모는 2025년에 32억 9,000만 달러에 달하여 매출 점유율의 58.02%를 차지했습니다. 사업자들은 지하 깊은 곳에서는 휴대전화 신호가 불안정하기 때문에 미션 크리티컬한 게이트웨이에서 온프레미스형 제어를 중시하고 있습니다. 그럼에도 불구하고, 대도시권의 Wi-Fi 및 프라이빗 LTE 백본이 성숙해짐에 따라 클라우드 네이티브형 서비스 시장은 연평균 성장률(CAGR) 11.12%로 확대되고 있습니다. 사이트 간 통합 대시보드를 통해 포트폴리오 소유자는 단일 규칙 세트로 요금 체계를 일원화하여 조정할 수 있으며, 자동화된 재해 복구 프로토콜을 통해 다운타임 위험을 최소화할 수 있습니다.
클라우드 도입을 통해 벤더에게는 지속적인 수익 전망이 명확해지고, 자산 소유자에게는 불규칙한 CAPEX(자본 지출) 대신 구독 형태의 OPEX(운영 지출)를 통해 현금 흐름이 안정화됩니다. 소프트웨어 패치는 일원적으로 배포되므로 취약점이 존재하는 기간이 단축되어 PCI-DSS 4.0의 감사 주기를 준수할 수 있습니다. 또한 클라우드 아키텍처는 MaaS(Mobility as a Service)와의 통합을 간소화하여, 타사 앱이 주차장 네트워크를 공개하지 않고도 토큰화된 예약 처리를 수행할 수 있도록 합니다. 그 결과, 주차 관리 시장에서는 로컬 게이트웨이가 트랜잭션을 캐싱하면서 클라우드 분석 기능과 동기화하는 하이브리드형 도입이 점차 보급되고 있습니다.
2025년, 공항, 병원, 다중 임차인형 소매 복합 시설의 안정적인 수요에 힘입어 노외 주차 시설의 수익은 34억 9,000만 달러에 달했습니다. 이는 주차 관리 시장 점유율의 61.57%를 차지했습니다. 한편, 노상 주차 시설은 버밍엄이나 겔프와 같은 도시의 디지털 커브 관리 조례를 배경으로 연평균 성장률(CAGR) 11.28%를 기록하며 뛰어난 성장세를 보이고 있습니다.
노상 주차 관리의 발전은 갓길 공간을 다중 모드 자산으로 취급하는 정책 전환을 반영하고 있습니다. 실시간 대시보드를 통해 센서가 주차 시간 초과를 감지한 경우에만 단속 순찰대가 파견되므로, 초과 근무 비용을 18% 절감할 수 있습니다. 비접촉식 주차 미터기나 번호판을 이용한 결제 앱은 현금 취급에 따른 보안 위험을 줄여주는 한편, 변동 요금제는 주차 공간 회전율을 높여 주변 소매점의 고객 유입을 촉진합니다. 통합된 위반 딱지 발급 워크플로우와 오픈 데이터 피드를 제공하는 벤더는 종단 간 투명성을 추구하는 기획 담당자들로부터 지지를 얻고 있습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 38.96%를 차지한 것으로 평가되었으며, 이는 디지털화 추진이 성숙 단계에 접어들었고 동적 가격 책정이 조기에 도입된 점이 반영된 결과입니다. 지자체는 공급업체에 주차 현황 API 공개를 의무화하는 오픈 데이터 정책을 활용하고 있으며, 이를 통해 내비게이션 및 갓길 배송 경로 최적화 분야에서 제3자 혁신이 촉진되고 있습니다. PCI-DSS 4.0의 시행 및 캘리포니아주 소비자 개인정보 보호법(CCPA)의 개정에 따라, 변조 방지 아키텍처에 대한 수요가 증가하고 있습니다. 사업자들은 AI 비전을 도입하여 게이트를 철거함으로써 평균 진입 시간을 40% 단축하는 동시에 사용자 만족도 점수를 향상시키고 있습니다.
아시아태평양은 다른 궤적을 따라가며, 9.78%라는 지역 내 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 중국, 일본, 한국의 급속한 도시화로 인해 토지 이용에 심각한 압박이 발생하고 있으며, 효율적인 노상 주차 공간 배정이 정책상의 시급한 과제가 되고 있습니다. 각국의 스마트 시티 구상에 따라 센서 네트워크 및 5G 백본에 자금이 투입되어, 클라우드를 통한 유도 지연이 감소하고 있습니다. 자동차 제조업체들은 Parkopedia의 정보를 대시보드에 통합하고 있으며, 슈퍼 앱에 내장된 QR 코드 결제를 통해 3선 도시에서도 비접촉식 주차가 일반화되고 있습니다. 이 지역 소비자들의 높은 기술 이해도가 도입 곡선을 가속화하여, 시범 솔루션의 본격적인 확대까지 걸리는 시간을 단축시키고 있습니다.
유럽에서는 데이터 개인정보 보호의 엄격함과 지속가능성 목표 간의 균형을 모색하고 있습니다. 2025년에 개정될 GDPR(EU 개인정보보호규정)의 국경 간 데이터 이전 조항에서는 데이터의 현지화 또는 승인된 계약상 메커니즘이 요구되므로, 많은 사업자가 지역별 클라우드 존을 선택하고 있습니다. EU 그린딜의 법규는 노상 주차 정책을 모달 시프트 목표와 연계하여, 마이크로모빌리티 도크 및 전기차 충전을 위해 확보된 공간을 장려하고 있습니다. 스톡홀름과 마드리드에서 진행 중인 동적 요금제 시범 사업에서는 요금을 배기가스 등급에 연동시켜 차량 군을 더 친환경적인 차량으로 유도하고 있습니다. 시장 성장세는 완만하지만, 규제의 명확성이 공급업체의 투자에 대한 확실성을 뒷받침하고 있습니다.
남미, 중동 및 아프리카는 여전히 신흥 시장이지만, 사업 확장 로드맵에서 그 존재감이 점점 더 커지고 있습니다. 상파울루에서는 주차 센서와 홍수 경보 네트워크를 연동하여 몬순 시즌에 교통 흐름을 우회시키고 있습니다. 한편, 두바이에서는 ‘종이 없는 정부’ 전략의 일환으로 스마트 주차 운영권을 도입하고 있습니다. 프로젝트 수는 적지만, 그린필드 개발을 통해 기존 시스템의 제약 없이 클라우드 아키텍처로 도약적인 전환이 가능해집니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the parking management market size was valued at USD 5.67 billion in 2025 and estimated to grow from USD 6.19 billion in 2026 to reach USD 9.58 billion by 2031, at a CAGR of 9.18% during the forecast period (2026-2031).
This report is Segmented by Deployment Model (On-Premises and Cloud-Based), Parking Site (Off-Street, On-Street), Solution Component (Hardware, Software Platform, Services), End-User Vertical (Municipal and Government, Commercial Off-Street Operators, and More), Technology (Sensor-Based, Camera/LPR-based, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Parking Management Market Trends and Insights
Urban Traffic Congestion Mitigation
Dynamic curb management programs demonstrate how parking can reduce vehicle circling and greenhouse-gas emissions. San Francisco's SF Park recalibrates rates every six weeks to maintain 85% occupancy, producing documented 30% reductions in search traffic within pilot zones. Similar sensor-based deployments in Portland and Hoboken showcase transferable playbooks for mid-sized cities that lack the resources for bespoke research. Municipal agencies now position parking APIs alongside transit feeds, allowing navigation apps to direct drivers to the lowest-cost bay in real time. The approach reframes parking fees from static taxes to behavior-modifying levers that re-balance peak-hour loads. Emerging congestion-pricing proposals in Los Angeles and Singapore further elevate the role of parking data as an enforcement backbone.
Smart-City Funding for Intelligent Transport Systems
Dedicated federal and supra-national grants are lowering adoption risk for cash-strapped municipalities. In the United States, the Federal Highway Administration earmarked USD 2.3 billion through 2026 for 5G-enabled roadway and parking systems, with disbursements contingent on open-architecture and cybersecurity compliance. European cities tap into Horizon Europe funds to pilot curb-side EV-charging combined with automated parking guidance. Long-cycle capital unlocks multi-agency projects that fuse parking occupancy, traffic-signal timing, and public-transit arrival data into a single urban-mobility dashboard. Because eligibility criteria require interoperability, vendors that support standardized APIs gain a structural advantage when bids are scored.
Cyber-Security and Data-Privacy Vulnerabilities
Mandatory migration to PCI-DSS 4.0 after April 2024 exposed security gaps at facilities still running decade-old controllers. Breaches of license-plate databases in California and the Netherlands amplified public scrutiny, prompting regulators to widen audit scopes to include anonymization protocols. Large platforms responded by embedding zero-trust architectures and partnering with specialist security firms, but smaller garages struggle to fund continual penetration testing. EU proposals to classify curb-management data as "high-risk AI processing" may add algorithmic-transparency requirements that further stretch compliance budgets.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-Native Parking-as-a-Service Adoption
- Mobile Payment and Digital Ticketing Penetration
- High CAPEX and Legacy-System Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The parking management market size for on-premise systems reached USD 3.29 billion in 2025, translating into a 58.02% revenue share. Operators value on-premise control for mission-critical gateways where sub-basement cellular signals remain unreliable. Even so, cloud-native offerings are expanding at an 11.12% CAGR as metropolitan Wi-Fi and private-LTE backbones mature. Cross-site dashboards allow portfolio owners to adjust tariffs globally with a single rule set, and automated disaster-recovery protocols minimize downtime risk.
Cloud adoption strengthens recurring-revenue visibility for vendors and stabilizes cash flows for asset owners via subscription OPEX rather than lumpy CAPEX. Because software patches roll out centrally, vulnerability windows shrink, aligning with PCI-DSS 4.0 audit cycles. Cloud architectures also simplify MaaS integrations, letting third-party apps conduct tokenized reservations without exposing garage networks. As a result, the parking management market sees a progressive blending of hybrid deployments where local gateways cache transactions but sync to cloud analytics.
Off-street facilities generated USD 3.49 billion in revenue in 2025, underpinned by stable demand at airports, hospitals, and multi-tenant retail complexes. This accounted for 61.57% of the parking management market share. Yet on-street deployments show superior expansion, rising at an 11.28% CAGR on the back of digital curb-management ordinances in cities such as Birmingham and Guelph.
The on-street advance reflects a policy pivot that treats curb space as a multimodal asset. Real-time dashboards dispatch enforcement patrols only when sensors flag overstays, cutting overtime costs by 18%. Contactless meters and pay-by-plate apps lower cash-handling security risks, while variable rates raise turnover, boosting surrounding retail footfall. Vendors that offer integrated citation workflows and open-data feeds gain mindshare among planners seeking end-to-end transparency.
Complete Report Scope:
- By Deployment Model
- On-premises
- Cloud-based
- By Parking Site
- Off-street
- On-street
- By Solution Component
- Hardware (Meters, Sensors, Cameras, LPR, Kiosks)
- Software Platform
- Services (Installation, Managed, Consulting)
- By End-User Vertical
- Municipal and Government
- Commercial Off-street Operators
- Transit and Airports
- Hospitality and Retail
- Healthcare and Universities
- Other End-User Verticals
- By Technology
- Sensor-based (ultrasonic, magnetometer)
- Camera / LPR-based
- Mobile-app and Bluetooth
- RFID and NFC
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 38.96% of global revenue in 2025, reflecting mature digitization mandates and early adoption of dynamic pricing. Municipalities leverage open-data policies that compel vendors to expose occupancy APIs, spurring third-party innovation in navigation and curb-delivery routing. PCI-DSS 4.0 enforcement and California Consumer Privacy Act amendments drive demand for tamper-resistant architectures. Operators deploy AI vision to remove gates, cutting average ingress times by 40% and elevating user satisfaction scores.
Asia Pacific follows a different trajectory, posting the fastest regional CAGR at 9.78%. Rapid urbanization in China, Japan, and South Korea creates acute land-use pressures, making efficient curb allocation a policy imperative. National smart-city blueprints fund sensor grids and 5G backbones that lower latency for cloud guidance. Automakers integrate Parkopedia feeds into dashboards, and QR payments embedded in super-apps normalize contactless parking even in tier-three cities. The region's consumer tech literacy accelerates adoption curves, compressing time-to-scale for pilot solutions.
Europe balances data-privacy rigor with sustainability objectives. Revised GDPR cross-border transfer clauses in 2025 require data-localization or approved contractual mechanisms, leading many operators to choose regional cloud zones. EU Green Deal legislation links curb policy to modal-shift targets, incentivizing spaces reserved for micro-mobility docks and EV charging. Dynamic-pricing pilots in Stockholm and Madrid tie tariffs to emission classes, nudging fleets toward cleaner vehicles. While market growth is moderate, regulatory clarity supports vendor investment certainty.
South America and the Middle East and Africa remain emergent but increasingly visible in expansion roadmaps. Sao Paulo integrates parking sensors with flood-alert networks to reroute traffic during monsoon events, while Dubai positions smart-parking concessions as part of a "paperless government" strategy. Although project counts are lower, greenfield builds allow leapfrogging directly to cloud architectures without legacy constraints.
- Amano McGann Inc.
- Conduent Transportation Solutions Inc.
- SKIDATA GmbH
- Flowbird Group SAS
- TIBA Parking Systems (FAAC SpA)
- FlashParking Inc.
- Passport Labs Inc.
- Q-Free ASA
- Siemens AG (Intelligent Traffic Systems)
- Bosch Security and Safety Systems (Robert Bosch GmbH)
- Indigo Park Services UK Ltd.
- LAZ Parking Ltd. LLC
- Cleverciti Systems GmbH
- IPS Group Inc.
- ParkMobile LLC
- EasyPark Group AB
- SenSen Networks Ltd.
- Parkopedia Ltd.
- Streetline Inc.
- ParkHelp Technologies S.L.
- ParkPlus Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Urban traffic congestion mitigation
- 4.2.2 Smart-city funding for intelligent transport systems
- 4.2.3 Cloud-native parking-as-a-service adoption
- 4.2.4 Mobile payment and digital ticketing penetration
- 4.2.5 MaaS-driven dynamic curb-pricing integration
- 4.2.6 Real-estate REIT monetisation of parking assets
- 4.3 Market Restraints
- 4.3.1 Cyber-security and data-privacy vulnerabilities
- 4.3.2 High CAPEX and legacy-system integration complexity
- 4.3.3 Equity backlash against dynamic pricing
- 4.3.4 Lack of interoperability standards (vendor lock-in)
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 On-premises
- 5.1.2 Cloud-based
- 5.2 By Parking Site
- 5.2.1 Off-street
- 5.2.2 On-street
- 5.3 By Solution Component
- 5.3.1 Hardware (Meters, Sensors, Cameras, LPR, Kiosks)
- 5.3.2 Software Platform
- 5.3.3 Services (Installation, Managed, Consulting)
- 5.4 By End-User Vertical
- 5.4.1 Municipal and Government
- 5.4.2 Commercial Off-street Operators
- 5.4.3 Transit and Airports
- 5.4.4 Hospitality and Retail
- 5.4.5 Healthcare and Universities
- 5.4.6 Other End-User Verticals
- 5.5 By Technology
- 5.5.1 Sensor-based (ultrasonic, magnetometer)
- 5.5.2 Camera / LPR-based
- 5.5.3 Mobile-app and Bluetooth
- 5.5.4 RFID and NFC
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amano McGann Inc.
- 6.4.2 Conduent Transportation Solutions Inc.
- 6.4.3 SKIDATA GmbH
- 6.4.4 Flowbird Group SAS
- 6.4.5 TIBA Parking Systems (FAAC SpA)
- 6.4.6 FlashParking Inc.
- 6.4.7 Passport Labs Inc.
- 6.4.8 Q-Free ASA
- 6.4.9 Siemens AG (Intelligent Traffic Systems)
- 6.4.10 Bosch Security and Safety Systems (Robert Bosch GmbH)
- 6.4.11 Indigo Park Services UK Ltd.
- 6.4.12 LAZ Parking Ltd. LLC
- 6.4.13 Cleverciti Systems GmbH
- 6.4.14 IPS Group Inc.
- 6.4.15 ParkMobile LLC
- 6.4.16 EasyPark Group AB
- 6.4.17 SenSen Networks Ltd.
- 6.4.18 Parkopedia Ltd.
- 6.4.19 Streetline Inc.
- 6.4.20 ParkHelp Technologies S.L.
- 6.4.21 ParkPlus Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment