

|
시장보고서
상품코드
2122849
암 지지요법 약물 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cancer Supportive Care Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
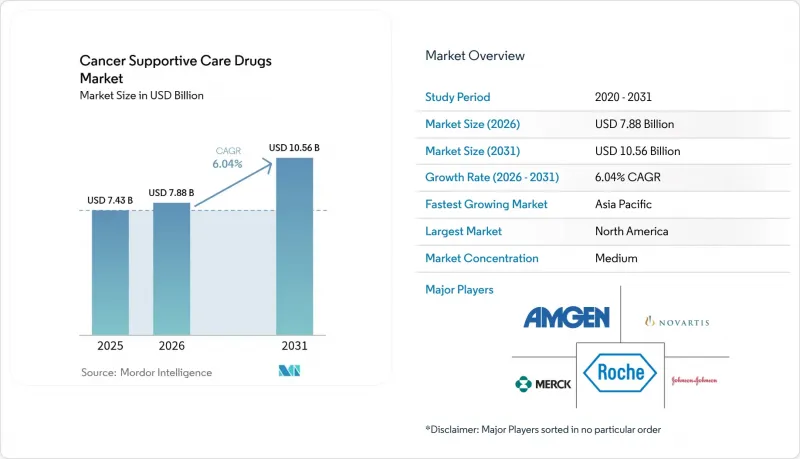
암 지지요법 약물 시장 규모는 2026년에 78억 8,000만 달러로 추정되고 2025년 74억 3,000만 달러에서 확대해, 2031년에는 105억 6,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 6.04%로 성장할 것으로 전망됩니다.

본 보고서는 약물 분류별(G-CSF, ESA, 구토 억제제 등), 적응증별(화학요법 유발성 호중구 감소증 등), 유통 채널별(병원 약국 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 암 지지요법 약물 시장 동향 및 인사이트
전 세계적으로 증가하는 암의 부담
신규 환자 수가 급증하고 있습니다. 국제암연구소(IARC)의 예측에 따르면, 2040년까지 연간 진단 건수는 2,840만 건에 달하여 2020년 대비 55% 증가할 것으로 전망됩니다. 50세 미만의 젊은 환자층에서 암 발생률은 1990년부터 2019년 사이 79% 급증하여, 생존 기간 연장 및 치료 주기의 반복으로 이어졌습니다. 이러한 인구 통계학적 변화로 인해 골수 억제 요법에 노출되는 기간이 길어지면서, 암 지지 요법 약물 시장 전체에서 G-CSF, 구토 억제제, 빈혈 치료제에 대한 수요가 증가하고 있습니다. 경제적 압박 또한 마찬가지로 심각합니다. 2018년에는 유럽에서만 암 관련 비용으로 1,990억 유로가 지출되었으며, 그중 320억 유로가 항암제에 사용되었습니다. 아시아태평양의 성장은 두드러지며, 2026년까지 중국의 암 관련 지출이 127억 달러에 달할 것으로 예측된다는 점이 그 좋은 예입니다. 이로 인해 지지 요법의 보급을 위한 큰 성장 여지가 더욱 강화되고 있습니다.
화학요법 및 병용 요법의 도입 확대
현재 고형암 및 혈액 악성 종양의 1차 치료에서는 병용 요법이 주류를 이루고 있으며, 단일 요법과 비교하여 3-4등급의 혈액학적 독성이 40-60% 증가하고 있습니다. 그 결과, 예방적 G-CSF, 적혈구 조혈 자극 인자 및 차세대 구토 억제제의 사용이 꾸준히 증가하고 있습니다. 트라스투주맙-델크스테칸과 같은 새로운 항체-약물 복합체(ADC)는 기존의 이상반응 프로파일에 특유한 폐 및 소화기계 독성을 더함으로써, 암 지지요법 약물 시장의 임상적 적용 범위를 확대되고 있습니다. 종양 전문의들이 표적 치료제를 주 화학요법과 통합함에 따라, 지지 요법 프로토콜은 세포 독성에 의한 부작용과 면역 매개성 부작용 모두를 예방하도록 확대되고 있습니다.
독성이 낮은 표적 치료 및 면역종양학 치료의 부상
면역관문억제제나 정밀한 저분자 억제제는 골수에 미치는 영향이 적은 경우가 많아, 기존 화학요법에 비해 호중구 감소증 발생률이 60-70% 낮습니다. 그 결과, 이러한 치료법이 1차 선택 표준이 되는 지역에서는 G-CSF 사용량이 감소할 가능성이 있습니다. 그렇다고 해서 지지 요법의 필요성이 사라지는 것은 아니며, 오히려 그 형태가 변화하고 있습니다. 면역 관련 이상반응에는 코르티코스테로이드, 내분비 보충 요법 및 피부과용 약제가 필요하지만, 이들은 암 지지요법 약물 시장에서 인접한 치료 영역을 차지하고 있습니다. 이러한 새로운 수요에 맞추어 파이프라인을 전환하는 제약 기업은 기존 카테고리에서의 매출 감소를 상쇄할 수 있을 것입니다.
부문별 분석
2025년, G-CSF는 암 지지요법 약물 시장 점유율의 34.62%를 차지하며, 호중구 감소증 예방에 있어 그 매우 중요한 역할을 입증했습니다. 이 부문의 견고한 성장세는 모든 종양 유형에서 예측 가능한 화학요법에 의한 골수 억제가 발생한다는 점과 임상 지침에서의 강력한 권고에 기인합니다. 바이오시밀러의 급속한 보급으로 단가는 압박받고 있지만, 치료에 대한 보급률은 확대되고 있어 매출은 상승 추세를 유지하고 있습니다. 스테로이드계 가글제나 점막염용 배리어 젤 등의 외용제는 생존 기간 연장에 따라 표면화되는 독성에 대처함으로써, 2031년까지 연평균 성장률(CAGR) 8.28%를 나타낼 것으로 전망됩니다. ESA(적혈구 생성 자극 인자)는 수혈에 반응하지 않는 빈혈 치료에 여전히 필수적이지만, 안전성 관련 표시로 인해 어느 정도 역풍을 맞고 있습니다. 구토 억제제는 지연성 구토를 대상으로 한 고정 용량 복합제의 출시에 힘입어 점진적인 성장세를 유지하고 있습니다. 비스포스포네이트 계열 약물 및 데노스맙의 바이오시밀러는 고령화에 따른 골격 관련 사건의 위험 증가에 따라 꾸준히 성장하고 있습니다. 한편, 오피오이드 수요는 통증 관리 패러다임의 변화를 반영하여 둔화되고 있습니다. 이러한 동향은 전반적으로 임상 실무의 진화와 보험 급여 제도의 변화가 암 지지요법 약물 시장 내 약물 군의 구도를 어떻게 지속적으로 재편하고 있는지를 보여줍니다.
매출 측면에서 볼 때, G-CSF(조혈모세포 콜로니 자극 인자)를 포함한 암 지지요법 약물 시장 규모는 가격 경쟁이 격화되는 상황에서도 예측 기간 동안 강력하게 확대될 것으로 전망됩니다. 대조적으로, 오피오이드의 매출액은 환자 수가 안정적임에도 불구하고 1일 평균 투여량의 감소로 인해 축소되고 있으며, 이는 지불 주체가 위험 감소로 이어지는 대체 요법을 중시하고 있음을 뒷받침합니다. 외용제 및 피하 투여제 분야의 지속적인 혁신은 제조업체들이 상품화된 주사제 이외의 분야로 사업을 다각화하도록 뒷받침하며, 새로운 하위 분류에서 지속적인 두 자릿수 성장을 위한 기반이 되고 있습니다.
지역별 분석
북미는 2025년 전 세계 매출의 42.61%를 차지했습니다. 이는 첨단 종양학 인프라와 고가의 생물학적 제제를 보상하는 광범위한 보험 적용에 힘입은 결과입니다. ‘Enhancing Oncology Model’과 같은 가치 기반 시범 사업은 측정 가능한 비용 절감 효과를 보여주고 있으며, 민간 보험사 간의 도입을 촉진함과 동시에 진료 지침에 따른 지지 요법의 보급을 뒷받침하고 있습니다.
유럽은 지역별 시장 중 2위의 규모를 자랑합니다. 적극적인 바이오시밀러 조달을 통해 일부 국가에서는 항암제 가격이 최대 97.8% 인하되어 접근성이 확대됨과 동시에 예산에 미치는 영향이 억제되고 있습니다. 각국의 의료 제도는 항암제에 막대한 지출(2018년 기준 320억 유로)을 하고 있으며, 지지 요법에 대한 보험 적용에 대한 강력한 정치적 의지가 드러나고 있습니다. 회원국 간의 환급 제도 차이로 인해 제약사들은 가격 전략을 조정할 수밖에 없지만, 널리 보급된 의료 기술 평가(HTA) 체계를 통해 비용 대비 효과는 항상 최우선 고려 사항으로 다뤄지고 있습니다.
아시아태평양은 인구 고령화, 중산층 확대, 그리고 보험 가입률 향상에 힘입어 연평균 성장률(CAGR) 7.31%로 가장 빠르게 성장하고 있는 지역입니다. 중국의 암 치료비는 2026년까지 127억 달러에 달할 것으로 예상되는 반면, 인도는 국내 바이오의약품 생산을 촉진하기 위해 외국인 직접 투자(FDI) 규제를 완화하고 있습니다. 정부의 검진 프로그램과 진단에 대한 이해도 향상으로 조기 발견률이 상승하고 있으며, 그 결과 치료 대상 환자 수가 증가하여 암 지지요법 약물 시장 수요가 지속되고 있습니다.
라틴아메리카와 중동 및 아프리카는 규모는 작지만 꾸준히 성장하고 있는 시장입니다. 브라질과 멕시코의 조달 컨소시엄은 바이오시밀러 시장 진입 일정에 맞추어 구매 수량에 따른 할인 협상을 진행하고 있습니다. 한편, 걸프협력회의(GCC) 회원국들은 보다 광범위한 의료 관광 구상의 일환으로, 프로토콜에 기반한 지지 요법을 도입하기 위해 3차 암 센터에 투자하고 있습니다. 이러한 지역들이 종합적으로 전 세계 성장세를 뒷받침하는 추가적인 수요를 창출하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the cancer supportive care drugs market size in 2026 is estimated at USD 7.88 billion, growing from 2025 value of USD 7.43 billion with 2031 projections showing USD 10.56 billion, growing at 6.04% CAGR over 2026-2031.
This report is Segmented by Drug Class (G-CSFs, Esas, Antiemetics, and More), Indication (Chemotherapy-Induced Neutropenia, and More), Distribution Channel (Hospital Pharmacies, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Cancer Supportive Care Drugs Market Trends and Insights
Growing Burden of Cancer Worldwide
New cases are rising sharply: IARC projects 28.4 million annual diagnoses by 2040, a 55% jump from 2020. Younger patients-those under 50-saw a 79% surge in cancer incidence between 1990 and 2019, leading to longer survival horizons and repeated treatment cycles. These demographic shifts lengthen exposure to myelosuppressive regimens, elevating demand for G-CSFs, antiemetics, and anemia therapies across the cancer supportive care drugs market. Economic pressure is equally significant; Europe alone spent EUR 199 billion on cancer in 2018, with EUR 32 billion earmarked for oncology medicines. Asia-Pacific growth is pronounced, exemplified by China's projected USD 12.7 billion oncology spend by 2026, reinforcing a sizeable runway for supportive care uptake.
Rising Adoption of Chemotherapy and Combination Regimens
Combination protocols now dominate frontline therapy for solid tumors and hematologic malignancies, raising grade 3-4 hematologic toxicities by 40-60% versus monotherapy. The result is steady utilization of prophylactic G-CSFs, erythropoiesis-stimulating agents, and next-generation antiemetics. Emerging antibody-drug conjugates, such as trastuzumab deruxtecan, layer unique pulmonary and gastrointestinal toxicities onto conventional adverse-event profiles, widening the clinical remit of the cancer supportive care drugs market. As oncologists integrate targeted agents with backbone chemotherapy, supportive care protocols broaden to encompass both cytotoxic and immune-mediated side-effect prevention.
Emergence of Targeted and Immuno-Oncology Therapies with Lower Toxicity
Immune checkpoint inhibitors and precision small-molecule inhibitors frequently spare bone marrow, leading to 60-70% lower neutropenia rates compared with traditional chemotherapy. Consequently, G-CSF volumes may moderate in regions where these modalities become first-line standards. Nonetheless, the supportive care mandate evolves rather than disappears: immune-related adverse events demand corticosteroids, endocrine replacement, and dermatologic agents that occupy adjacent therapeutic niches within the cancer supportive care drugs market. Manufacturers that pivot pipelines toward these emerging needs can offset erosion in legacy categories.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Value-Based Oncology Care Models
- Expansion of Oral and Subcutaneous Formulations Enabling Home Care
- Safety Concerns Around Opioid Misuse and ESA-Linked Thrombotic Events
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
G-CSFs represented 34.62% of the cancer supportive care drugs market in 2025, underscoring their pivotal role in neutropenia prophylaxis. The segment's resilience stems from predictable chemotherapy-induced marrow suppression across tumor types and strong endorsement in clinical guidelines. Rapid biosimilar uptake compresses unit prices but expands treatment penetration, keeping revenue on an upward trajectory. Topical agents, including steroid mouthwashes and barrier gels for mucositis, post an 8.28% CAGR to 2031 by addressing toxicities that gain visibility as survival lengthens. ESAs remain essential for anemia unresponsive to transfusion yet face moderate headwinds from safety labeling. Antiemetics sustain incremental gains, supported by fixed-dose combination launches targeting delayed emesis. Bisphosphonates and denosumab biosimilars grow steadily alongside rising skeletal-related-event risk in aging populations. Meanwhile, opioid demand softens, mirroring changing pain-control paradigms. Collectively, these trends illustrate how clinical-practice evolution and reimbursement shifts continually reshape the drug-class landscape within the cancer supportive care drugs market.
In revenue terms, the cancer supportive care drugs market size for G-CSFs is projected to expand briskly through the forecast horizon, even as price competition intensifies. Conversely, opioid revenues diminish due to lower average daily doses despite stable patient counts, validating payer emphasis on risk-mitigating alternatives. Continuous innovation in topical and subcutaneous formats helps manufacturers diversify beyond commoditized injectables, anchoring sustainable double-digit growth in newer subclasses.
Complete Report Scope:
- By Drug Class
- G-CSFs
- ESAs
- Antiemetics
- Bisphosphonates
- Opioids
- NSAIDs
- Topical Agents
- Other Drug Classes
- By Indication
- Chemotherapy-induced Neutropenia
- Chemotherapy-induced Anemia
- Nausea & Vomiting
- Cancer-related Bone Loss
- Cancer Pain
- Oral & Dermal Mucositis
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 42.61% of global revenue in 2025, underpinned by advanced oncology infrastructure and widespread insurance coverage that reimburses high-cost biologics. Value-based pilots such as the Enhancing Oncology Model demonstrate measurable savings, encouraging replication across commercial payers and fortifying guideline-aligned supportive care uptake.
Europe stands as the second-largest regional market. Aggressive biosimilar procurement cut cancer-medicine prices by up to 97.8% in select countries, broadening access and curbing budget impact. National health systems devote substantial outlays-EUR 32 billion in 2018-for oncology drugs, evidencing strong political commitment to supportive therapy coverage. Reimbursement variability across member states prompts manufacturers to tailor pricing strategies, but widespread HTA frameworks ensure cost-effectiveness remains front-of-mind.
Asia-Pacific is the fastest-growing region with a 7.31% CAGR, energized by demographic aging, expanding middle classes, and broader insurance penetration. China's oncology expenditure is on course to reach USD 12.7 billion by 2026, while India liberalizes foreign-direct-investment norms to spur domestic biologics manufacture. Government screening programs and rising diagnostic literacy heighten early detection rates, translating into larger treated cohorts and sustained demand in the cancer supportive care drugs market.
Latin America and the Middle East & Africa constitute smaller but steadily advancing markets. Procurement consortia in Brazil and Mexico negotiate volume-based discounts that align with biosimilar entry timelines. Meanwhile, Gulf Cooperation Council members invest in tertiary cancer centers, importing protocol-driven supportive care as part of broader medical-tourism aspirations. Collectively, these geographies add incremental volume that bolsters global growth momentum.
- Amgen
- Johnson & Johnson
- Roche
- Novartis AG (Sandoz & Hexal)
- Teva Pharmaceutical Industries
- Pfizer
- Sanofi
- Helsinn Healthcare
- Heron Therapeutics Inc.
- Dr. Reddy's Laboratories
- Sun Pharmaceuticals Industries
- Ipsen
- Kyowa Kirin Co. Ltd.
- Otsuka
- Accord Healthcare
- Fresenius
- Lupin
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Burden Of Cancer Worldwide
- 4.2.2 Rising Adoption Of Chemotherapy And Combination Regimens
- 4.2.3 Introduction Of Cost-Effective Biosimilars
- 4.2.4 Shift Toward Value-Based Oncology Care Models
- 4.2.5 Expansion Of Oral And Subcutaneous Formulations Enabling Home Care
- 4.3 Market Restraints
- 4.3.1 Emergence Of Targeted And Immuno-Oncology Therapies With Lower Toxicity
- 4.3.2 Safety Concerns Around Opioid Misuse And ESA-Linked Thrombotic Events
- 4.3.3 Pricing Pressures From Reference-Pricing And Tender Systems
- 4.3.4 Growing Use Of Digital Symptom Management Reducing Pharmacologic Demand
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Drug Class
- 5.1.1 G-CSFs
- 5.1.2 ESAs
- 5.1.3 Antiemetics
- 5.1.4 Bisphosphonates
- 5.1.5 Opioids
- 5.1.6 NSAIDs
- 5.1.7 Topical Agents
- 5.1.8 Other Drug Classes
- 5.2 By Indication
- 5.2.1 Chemotherapy-induced Neutropenia
- 5.2.2 Chemotherapy-induced Anemia
- 5.2.3 Nausea & Vomiting
- 5.2.4 Cancer-related Bone Loss
- 5.2.5 Cancer Pain
- 5.2.6 Oral & Dermal Mucositis
- 5.3 By Distribution Channel
- 5.3.1 Hospital Pharmacies
- 5.3.2 Retail Pharmacies
- 5.3.3 Online Pharmacies
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Amgen Inc.
- 6.3.2 Johnson & Johnson (Janssen)
- 6.3.3 F. Hoffmann-La Roche AG
- 6.3.4 Novartis AG (Sandoz & Hexal)
- 6.3.5 Teva Pharmaceutical Industries Ltd.
- 6.3.6 Pfizer Inc.
- 6.3.7 Sanofi
- 6.3.8 Helsinn Healthcare SA
- 6.3.9 Heron Therapeutics Inc.
- 6.3.10 Dr. Reddy's Laboratories
- 6.3.11 Sun Pharmaceutical Industries Ltd.
- 6.3.12 Ipsen Pharma
- 6.3.13 Kyowa Kirin Co. Ltd.
- 6.3.14 Otsuka Holdings Co. Ltd.
- 6.3.15 Accord Healthcare
- 6.3.16 Fresenius Kabi
- 6.3.17 Lupin Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


