

|
시장보고서
상품코드
2122880
선박 스티어링 시스템 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Marine Steering System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
선박 스티어링 시스템 시장 규모는 2025년 35억 2,000만 달러로 평가되었고, 2026년에는 36억 9,000만 달러로 추정되고, 2026-2031년 CAGR 4.94%로 성장을 지속할 전망이며, 2031년에는 47억 달러에 이를 것으로 예측됩니다.
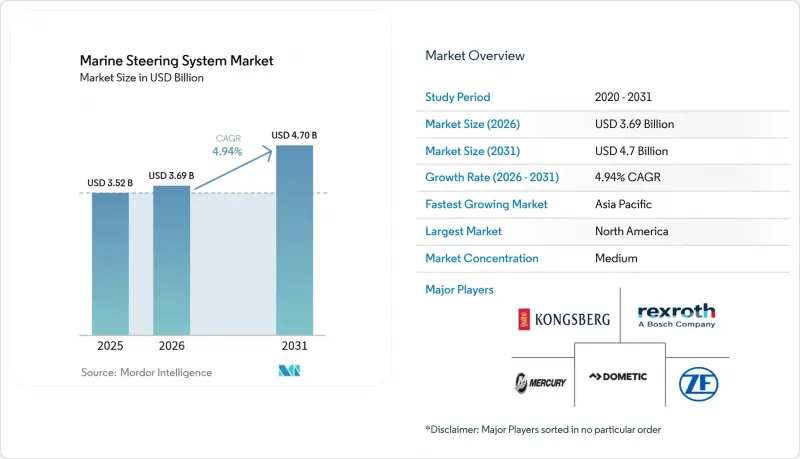
본 보고서는 제품 유형별(로터리 베인식, 램식 등), 구동 기술별(기존 유압식, 전기유압식 등), 제어 모드별(수동식 등), 선박 유형별(여객선 등), 추진 구성별(인보드식 등), 판매 채널별(OEM 순정 장비 및 애프터마켓용 개조), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 선박 스티어링 시스템 시장 동향 및 인사이트
아시아 및 유럽의 해군 현대화 프로그램
방위 예산 증가에 따라 중국, 한국, 일본, 독일, 네덜란드에서 다목적 호위함, 강습상륙함, 잠수함의 꾸준한 조달이 추진되고 있습니다. 각 함정에는 통합 브리지 및 전투 관리 시스템과 연동 가능한 사이버 보안 대책이 마련되어 있으며, 중복성을 높인 조타 시스템이 요구되고 있습니다. 2024년 현재, 중국 인민해방군 해군은 234척의 주요 수상 전투함을 운용하고 있으며, 이는 미 해군이 배치한 219척을 웃도는 수치입니다. 이러한 함대 확대로 인해 국내 조선소는 풀가동 상태를 유지하고 있으며, 지역 공급망 전반에 걸친 조타 시스템 하청업체들도 활용되고 있습니다. 유럽의 NATO 병행 프로그램은 음향 시그니처를 최소화하고, 동적 위치 유지를 지원하며, 무인 윙맨 보트를 지원하는 전동 또는 전기유압식 액추에이터에 대한 수요를 더욱 높이고 있습니다.
전 세계 레저용 보트 함대의 성장
2024년, 미국의 파워보트 및 제트스키 판매 대수는 23만-24만 대를 기록했습니다. 이는 구매자들이 조이스틱을 이용한 접안 조작, 무선 조타 제어, 그리고 초보 소유자도 쉽게 조종할 수 있게 해주는 통합형 오토파일럿을 원했기 때문입니다. 각 OEM 업체들은 스마트 스티어링과 추진 시스템 업그레이드를 세트로 판매하고 있으며, 이를 통해 구형 선체를 대상으로 매력적인 애프터마켓 수요가 창출되고 있습니다. 이 부문이 국내 경제에 미치는 영향으로 인해 부품, 서비스, 전자기기 매출이 뒷받침되고 있으며, 신규 선박 등록 수의 경기 변동에 따른 영향을 완화하고 있습니다.
상선 건조 분야의 경기 침체
컨테이너선 신조선 수주는 여전히 역사적으로 높은 수준을 유지하고 있지만, 운항사들이 설비 투자를 미루면서 2024년 한 해 동안 유조선, 벌크선, 일반 화물선의 계약은 주춤했습니다. 아시아의 조선소들은 이러한 구성 변화에 맞추어 생산량을 조정하고 있으며, 생산 능력의 변동을 상쇄하기 위해 개조 공사는 증가하고 있지만, 표준 조타 장치 세트에 대한 기초적인 수요는 감소하고 있습니다.
부문 분석
로터리 베인 방식은 신뢰성과 간편한 유지보수 절차를 강점으로 삼아 2025년 선박 조타 시스템 시장에서 42.41%의 점유율을 유지했습니다. 그러나 조선소들이 정밀 제어, 소음 저감 및 내장형 진단 기능을 사양으로 요구하게 되면서, 전기-기계 일체형 유닛이 2031년까지 연평균 성장률(CAGR) 8.86%로 성장을 주도하고 있습니다. 램 실린더는 극도의 토크와 중복성이 필수적인 중량물 운반용 해군 함정 및 해양 지원선에서 계속해서 채택되고 있습니다. 랙 앤 피니언 방식 어셈블리는 콤팩트한 설치 면적이 요구되는 내륙 수역이나 소형 선박과 같은 틈새 시장에서 활용되고 있습니다.
수요는 자가 보정 기능을 갖추고 충돌 회피 알고리즘과 연동되는 소프트웨어 정의형 액추에이터로 이동하고 있습니다. 선급협회는 현재 사이버 보안 대책이 적용된 펌웨어를 인증하고 있으며, 이에 따라 운항 사업자는 기존의 유압 장치를 개조하는 대신 차세대 전동 또는 하이브리드 제품으로의 전환을 촉진받고 있습니다. 그 결과, 선박 스티어링 시스템 시장에서는 모든 선종에 적용 가능한 모듈식 전기 기계식 카트리지로 제품 로드맵이 수렴되고 있습니다.
2025년 도입 실적에서 유압 회로는 여전히 51.86%를 차지했지만, 완전 전동식 파워 스티어링은 연평균 15.9%의 속도로 확대되고 있습니다. 하이브리드형 전기유압 패키지는 이러한 전환기를 가교하는 역할을 수행하고 있으며, 명령이 있을 때만 작동하는 온디맨드 펌프를 제공함으로써 공회전 시 손실을 줄이고, 엔진이 정지된 상태에서도 선박 조종이 가능하게 합니다. 기계식 케이블 시스템은 저마력 선박에서는 여전히 사용되고 있지만, 조이스틱이나 오토파일럿 기능이 저가형 선박에도 보급됨에 따라 점차 대체되고 있습니다.
전동 액추에이터는 1밀리초 미만의 지연 시간을 실현하고, 회생 제동을 통합함으로써 하이브리드 선박의 호텔 부하 부담을 경감시킵니다. 각국 해사 당국이 유분 혼입 배수 배출 제한을 강화하는 가운데, 운항사는 유체를 사용하지 않는 아키텍처를 규제 준수를 촉진하는 수단이자 동시에 수명 주기 비용을 절감하는 수단으로 간주하고 있습니다. 이러한 성능과 지속가능성을 겸비한 조합을 통해 전기 기술은 선박 조타 시스템 시장에서 가장 혁신적인 동향으로서의 입지를 확고히 하고 있습니다.
지역별 분석
북미는 2025년 선박 조타 시스템 시장의 45.98%를 차지했으며, 견조한 재량 지출과 8,500만 명의 보트 애호가들에 의한 모터보트 재고의 높은 회전율을 배경으로 추가적인 성장이 예상됩니다. 한편, 미국 해안경비대의 사이버 보안 지침에 따라 상업 선단 전반에 걸쳐 암호화된 디지털 조타 장치의 도입이 가속화되고 있습니다. 캐나다의 북극권 순찰 프로그램은 빙해용 선체에 대한 첨단 조타 기능에 대한 수요를 더욱 부추기고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.27%로 성장을 주도하고 있습니다. 현역 주요 군함 234척으로 상징되는 중국의 해군 확장 정책은 조선소가 핵심 하위 시스템의 자급자족을 목표로 하는 가운데, 국내 조선 생산을 뒷받침하고 있습니다. 일본, 한국, 싱가포르는 자율형 수상함 연구를 주도하며, AI 지원 조타 액추에이터에 대한 수요를 창출하고 있습니다. 지역의 전기화 정책도 호재로 작용하고 있으며, 특히 제로 배출 의무화가 진행 중인 연안 관광 및 도서 물류 선단에서 이러한 경향이 두드러집니다.
유럽에서는 NATO의 프리깃함 프로그램과 엄격한 환경 규제를 기반으로 성장이 예상됩니다. 유럽해상안전청(EMSA)의 STEERSAFE 권고에 따라 조타각, 부하, 응답 시간을 지속적으로 모니터링해야 할 의무가 부과됨에 따라, 운항 사업자들은 다수의 센서가 탑재된 조타 장치를 지정하고 있습니다. 노르웨이에서 진행되고 있는 자율형 여객 페리 실증 실험은 디지털 조타 솔루션의 실용적 준비가 완료되었음을 입증하고 있으며, 유럽 전역에서 지자체에 의한 도입 확대를 뒷받침하고 있습니다. 동시에, EU의 AI법은 조타용 펌웨어에 통합된 머신러닝 기능에 대해 법적 명확성을 제공함으로써 공급업체의 투자를 촉진하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the marine steering systems market size is expected to grow from USD 3.52 billion in 2025 to USD 3.69 billion in 2026 and is forecast to reach USD 4.7 billion by 2031 at 4.94% CAGR over 2026-2031.
This report is Segmented by Product Type (Rotary Vane Type, Ram Type, and More), Actuation Technology (Conventional Hydraulic, Electro-Hydraulic, and More), Control Mode (Manual, and More), Vessel Type (Passenger and More), Propulsion Configuration (Inboard and More), Distribution Channel (OEM Fitment and Aftermarket Retrofit), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Marine Steering System Market Trends and Insights
Naval Modernization Programmes in Asia and Europe
Rising defense budgets propel steady procurement of multi-role frigates, amphibious carriers, and submarines across China, South Korea, Japan, Germany, and the Netherlands. Each hull specifies cyber-secure, redundancy-rich steering systems capable of mating with integrated bridge and combat-management suites. China's People's Liberation Army Navy operated 234 major surface combatants in 2024, outnumbering the 219 units fielded by the U.S. Navy, a fleet expansion that keeps domestic yards at full tilt and draws on steering subcontractors throughout regional supply chains. Parallel NATO programs in Europe reinforce demand for electric or electro-hydraulic actuators that minimize acoustic signatures, accommodate dynamic-positioning holds, and support unmanned wingman craft.
Growth in Global Recreational Boating Fleet
Powerboat and personal-watercraft sales recorded 230,000-240,000 units in the United States during 2024 as buyers sought joystick docking, wireless helm controls, and integrated autopilots that simplify skippering for novice owners. OEMs bundle smart steering with propulsion upgrades, creating a compelling aftermarket funnel for older hulls. The segment's domestic economic footprint sustains parts, service, and electronics revenues that cushion cyclical swings in new-boat registrations.
Cyclical Downturn in Commercial Shipbuilding
Container-ship new-build bookings remain historically elevated, yet tanker, bulk, and general-cargo contracts softened through 2024 as operators delayed capital expenditures. Asian yards adjust output to match this mix, reducing baseline demand for standard helm sets even as retrofit work rises to offset capacity fluctuations.
Other drivers and restraints analyzed in the detailed report include:
- Retrofitting Demand Driven by IMO Mandates
- OEM Push Toward Electric-Power Steering for Outboards
- High Upfront Cost of Electric Steering Conversions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rotary-vane designs retained 42.41% of the marine steering systems market share in 2025, anchored by reliability and simple service protocols. Yet electro-mechanical integrated units headline growth with a 8.86% CAGR through 2031 as shipyards specify precision control, noise reduction, and embedded diagnostics. Ram cylinders continue in heavy-lift naval and offshore support craft where extreme torque and redundancy are mandatory. Rack-and-pinion assemblies serve niche inland and small-craft segments needing compact footprints.
Demand tilts toward software-defined actuators that self-calibrate and interface with collision-avoidance algorithms. Classification societies now certify cyber-secure firmware, nudging operators toward new-generation electric or hybrid products rather than refurbishing legacy hydraulics. Consequently, the marine steering systems market sees product road-maps converge on modular electro-mechanical cartridges deployable across vessel classes.
Hydraulic circuits still delivered 51.86% of 2025 installations, yet fully electric power steering is accelerating at 15.9% annually. Hybrid electro-hydraulic packages bridge the transition, offering on-demand pumps that spin only when commanded, trimming idle losses, and enabling engine-off maneuvering. Mechanical cable systems persist in low-horsepower craft but face gradual replacement as joystick and autopilot features move down-market.
Electric actuators achieve sub-millisecond lag and integrate regenerative braking that eases hotel-load demands on hybrid vessels. As flag administrations tighten oil-to-water discharge limits, operators view fluid-free architectures as both compliance facilitators and lifecycle cost reducers. This performance-plus-sustainability mix cements electric technology as the marine steering systems market's most disruptive trend.
Complete Report Scope:
- By Product Type
- Rotary Vane
- Ram-Type
- Rack-and-Pinion
- Electro-Mechanical (Integrated)
- By Actuation Technology
- Conventional Hydraulic
- Electro-Hydraulic
- Fully Electric Power Steering (EPS)
- Mechanical/Cable
- By Control Mode
- Manual
- Auto-Pilot
- DP/Autonomous Integration
- By Vessel Type
- Passenger (Cruise, Ferry, Yacht)
- Commercial Cargo and Workboats
- Naval and Coast-Guard
- Offshore Energy Support
- By Propulsion Configuration
- Inboard
- Outboard
- Sterndrive
- By Distribution Channel
- OEM Fitment
- Aftermarket Retrofit
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Egypt
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 45.98% of the marine steering system market in 2025 and is forecast to grow on robust discretionary spending and 85 million boating participants maintain high turnover in powerboat inventories, while U.S. Coast Guard cybersecurity directives accelerate the adoption of encrypted digital helms across commercial fleets. Canadian Arctic patrol programs further support the sophisticated steering demand for ice-classified hulls.
Asia-Pacific leads growth with an 8.27% CAGR to 2031. Chinese naval expansion, underscored by 234 major warships in active service, fuels domestic shipbuilding production as yards aim for self-reliance in critical subsystems. Japan, South Korea, and Singapore pioneer autonomous surface research, seeding demand for AI-compatible helm actuators. Regional electrification policies add momentum, particularly in coastal tourism and island logistics fleets where zero-emission mandates emerge.
Europe records growth, anchored by NATO frigate programs and stringent environmental statutes. The European Maritime Safety Agency's STEERSAFE recommendations obligate continuous monitoring of rudder angle, load, and response times, leading operators to specify sensor-rich steering gear. Norway's operational autonomous passenger ferry pilot validates real-world readiness of digital helm solutions, encouraging wider municipal deployments across the continent. Concurrently, the EU AI Act provides legal clarity for machine-learning functions embedded in steering firmware, spurring vendor investments.
- Dometic Marine
- Mercury Marine
- ZF Friedrichshafen AG
- Bosch Rexroth
- Kongsberg Maritime
- Kobelt Manufacturing
- Damen Marine Components
- Wills Ridley Ltd
- HyDrive Engineering Pty Ltd
- Hypro Marine
- Techno Italia Kft
- Dometic Group
- Yamaha Motor Co.
- Uflex SRL
- Lecomble and Schmitt
- Vetus B.V.
- Jastram Engineering
- Glendinning Products
- Engine Monitor Inc. (EMI)
- Multisteer (India)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Naval modernisation programmes in Asia and Europe
- 4.2.2 Growth in global recreational boating fleet
- 4.2.3 Retrofitting demand driven by IMO steering gear testing mandates
- 4.2.4 OEM push toward electric-power steering for outboards
- 4.2.5 Surge in autonomous-ready 'fly-by-wire' rudder actuators
- 4.2.6 Demand for low-sulphur-fuel compatible electro-hydraulic fluids
- 4.3 Market Restraints
- 4.3.1 Cyclical downturn in commercial shipbuilding
- 4.3.2 High upfront cost of electric steering conversions
- 4.3.3 Shortage of marine-grade semiconductor chips for steering controllers
- 4.3.4 Class-society cyber-resilience rules delaying digital steering roll-outs
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD))
- 5.1 By Product Type
- 5.1.1 Rotary Vane
- 5.1.2 Ram-Type
- 5.1.3 Rack-and-Pinion
- 5.1.4 Electro-Mechanical (Integrated)
- 5.2 By Actuation Technology
- 5.2.1 Conventional Hydraulic
- 5.2.2 Electro-Hydraulic
- 5.2.3 Fully Electric Power Steering (EPS)
- 5.2.4 Mechanical/Cable
- 5.3 By Control Mode
- 5.3.1 Manual
- 5.3.2 Auto-Pilot
- 5.3.3 DP/Autonomous Integration
- 5.4 By Vessel Type
- 5.4.1 Passenger (Cruise, Ferry, Yacht)
- 5.4.2 Commercial Cargo and Workboats
- 5.4.3 Naval and Coast-Guard
- 5.4.4 Offshore Energy Support
- 5.5 By Propulsion Configuration
- 5.5.1 Inboard
- 5.5.2 Outboard
- 5.5.3 Sterndrive
- 5.6 By Distribution Channel
- 5.6.1 OEM Fitment
- 5.6.2 Aftermarket Retrofit
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Spain
- 5.7.3.5 Russia
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 South Korea
- 5.7.4.4 India
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 United Arab Emirates
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 Egypt
- 5.7.5.4 Turkey
- 5.7.5.5 South Africa
- 5.7.5.6 Rest of Middle East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Dometic Marine
- 6.4.2 Mercury Marine
- 6.4.3 ZF Friedrichshafen AG
- 6.4.4 Bosch Rexroth
- 6.4.5 Kongsberg Maritime
- 6.4.6 Kobelt Manufacturing
- 6.4.7 Damen Marine Components
- 6.4.8 Wills Ridley Ltd
- 6.4.9 HyDrive Engineering Pty Ltd
- 6.4.10 Hypro Marine
- 6.4.11 Techno Italia Kft
- 6.4.12 Dometic Group
- 6.4.13 Yamaha Motor Co.
- 6.4.14 Uflex SRL
- 6.4.15 Lecomble and Schmitt
- 6.4.16 Vetus B.V.
- 6.4.17 Jastram Engineering
- 6.4.18 Glendinning Products
- 6.4.19 Engine Monitor Inc. (EMI)
- 6.4.20 Multisteer (India)


