

|
시장보고서
상품코드
2122910
반도체 레이저 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Semiconductor Laser - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
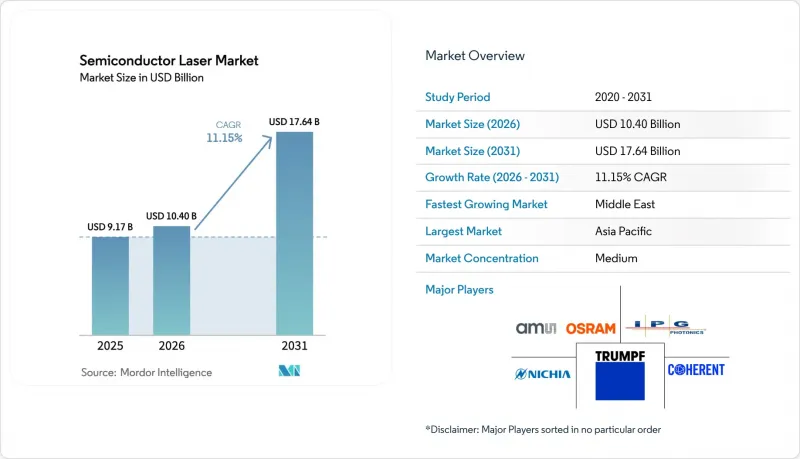
에 의하면, 반도체 레이저 시장 규모는 2025년 91억 7,000만 달러로 평가되었습니다. 2026년에는 104억 달러로 확대되어 2031년까지 176억 4,000만 달러에 이를 것으로 예상되고 2026-2031년에 걸쳐 CAGR 11.15%로 성장할 전망입니다.

본 보고서는 파장(적외선 레이저, 적색 레이저, 녹색 레이저, 청색 레이저, 자외선 레이저), 레이저 유형(에지 에미팅 레이저(EEL), 수직 공진기 면방출 레이저(VCSEL), 양자 캐스케이드 레이저, 파이버 레이저),용도(통신, 의료 분야, 군 및 방위, 산업, 계측 기기·센서, 자동차), 출력(100mW 이하, 100mW-1W, 1W-5W, 5W 이상), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 반도체 레이저 시장 동향 및 인사이트
가전제품 분야의 3D 센싱 기술 급속한 확대
스마트폰 제조업체들이 얼굴 인식 및 증강현실(AR) 기능을 확충함에 따라, 비행 시간법(ToF) 및 구조화된 광 모듈용 VCSEL 어레이의 출하 대수가 급증했습니다. 이 제품들은 벽면 콘센트 효율이 45%를 초과하며, 능동 냉각 없이 최대 150°C의 환경에서도 신뢰성 높은 작동을 실현하고 있습니다. 소니는 후면 조사형 센서의 노하우를 활용하여 VCSEL 다이와 CMOS 검출기를 공동 패키징함으로써 모듈의 실적를 30% 줄였을 뿐만 아니라, 대량 주문 시 단가를 2달러 이하로 낮췄습니다. 각 제조업체가 결제 기능 확보와 제품 차별화를 꾀하는 가운데, 안드로이드 플래그십 모델에 대한 채택률은 2023년 18%에서 2025년에는 추정 42%로 증가했습니다. Euro NCAP의 차량 실내 모니터링 관련 규제를 계기로, -40°C에서 +85°C의 온도 범위를 견디는 듀얼 존 VCSEL 일루미네이터가 도입되었으며, 에피택셜 균일성에 대한 요구 사항이 엄격해졌습니다. 웨어러블 기기도 추가적인 성장 동력이 되고 있으며, 5mm 이하의 VCSEL 모듈이 제스처 인식 및 비접촉 심박수 측정을 가능하게 함에 따라, 스마트 글래스와 건강 모니터의 연간 출하 대수는 2028년까지 5,000만 대를 넘어설 것으로 예측됩니다.
실리콘 포토닉스 상호 연결 부문의 새로운 수요
하이퍼스케일 사업자들은 2024-2025년에 걸쳐 400G 이더넷에서 800G 이더넷으로 전환하고, 실리콘 위에 헤테로접합된 III-V계 레이저를 통합함으로써 레인당 소비 전력을 3W 이하로 억제하고,결합 손실을 0.5dB 이하로 줄였습니다. 코패키징 옵틱스에서는 레이저 어레이를 스위치 ASIC 위에 직접 배치함으로써 SerDes의 병목 현상을 해소하고, 레이턴시를 40ns 단축합니다. 이는 AI 훈련 클러스터에서 높이 평가되는 장점입니다. DARPA는 2025년까지 이종 집적 수율을 95%로 향상시키기 위해 2억 300만 달러를 지원했습니다. 현재월플러그 효율은 10% 전후로 유지되고 있어, 공랭식 랙용 20%라는 열적 허용 범위에 미치지 못하고 있습니다. 이러한 상황을 감안하여 2027년까지 15%를 달성하는 것을 목표로, 양자점 이득 매체 및 포토닉 결정 공진기에 대한 연구가 활발히 진행되고 있습니다. 카 주파수 콤은 디스크리트 어레이를 대체하고 있으며, 단일 마이크로 공진기로 80개의 채널을 제공하여 메트로 네트워크에서 트랜시버의 부품 비용을 35% 절감하고 있습니다.
화합물 반도체 웨이퍼 공급망의 변동성
4개 공급업체가 전 세계 갈륨 비소 웨이퍼 생산 능력의 78%를 장악하고 있어, 반도체 레이저 시장은 수요의 급격한 변동에 민감한 상황에 놓여 있습니다. 2023년 8월 중국이 갈륨과 게르마늄에 대한 수출 규제를 시행함에 따라 6인치 기판의 리드타임은 12주에서 26주로 늘어났고, 2024년 초까지 현물 가격은 40% 상승했습니다. 하이퍼스케일 기업의 구매자들은 인듐 인화물(InP)에 대한 장기 계약을 체결했기 때문에 중소 다이오드 제조업체들은 유연성이 낮은 갈륨 비소 대체재로 밀려나고 있습니다. 이중 조달(dual sourcing)에는 AEC-Q100 및 Telcordia GR-468-CORE 규격에 따른 18-24개월의 검사가 필요하며, 이로 인해 다각화가 지연되고 있습니다. 4인치 웨이퍼에서 6인치 웨이퍼로 규모를 확대하려면 여전히 막대한 설비 투자가 필요하며, MOCVD 반응기 1대의 가격은 400만 달러로, 5년 내에 투자금을 회수하려면 95%의 가동률이 필요합니다.
부문별 분석
적외선 레이저는 2025년 매출의 42.5%를 차지하며, 소비자용 3D 센싱 및 장거리 광섬유 링크를 지배하는 850nm 및 1,550nm 디바이스를 통해 반도체 레이저 시장을 뒷받침했습니다. 자외선(UV) 제품은 절대 금액으로는 작지만, EUV 리소그래피 출하 및 의료용 UV 경화형 프로토타이핑을 배경으로 2031년까지 연평균 성장률(CAGR) 14.8%로 확대되어, 첨단 제조 도구를 통한 반도체 레이저 시장 규모에 대한 기여도가 높아질 것으로 예측됩니다.
VCSEL 기반 적외선 모듈은 결합을 단순화하는 원형 빔을 제공하는 반면, QCL 기반 중적외선 광원은 가스 감지용 파장 조정 기능을 갖추고 있습니다. 자외선 부문의 보급은 여전히 비용에 좌우되지만, 새롭게 등장한 266nm 다이오드는 더 높은 수율과 더 긴 수명을 약속합니다. 규제 기준인 IEC 60825의 클래스 3B 및 클래스 4 제한에 따라, 5mW를 초과하는 출력에서는 고도의 인터록이 필요하게 되어 설계 예산 및 시장 출시 기간에 영향을 미치고 있습니다. 고급 로직 노드가 3nm 이하로 전환됨에 따라, 리소그래피 장비 공급업체들이 자외선 수요를 주도하여 반도체 레이저 시장의 두 자릿수 성장을 뒷받침할 것으로 보입니다.
VCSEL은 웨이퍼 스케일 검사를 통해 다이 비용을 0.50달러 이하로 억제하는 데 성공하여 37.8%의 시장 점유율을 확보했습니다. 이를 통해 반도체 레이저 시장에서 주도적인 입지를 공고히 하고 있습니다. 한편, QCL은 중적외선 분광법이 규제 측면에서 호재를 타고 있어 2031년까지 연평균 성장률(CAGR) 16.3%로 급성장하고 있으며, 이는 환경 및 방위 프로그램이 반도체 레이저 시장 규모에 미치는 영향이 확대되고 있음을 시사합니다.
엣지 에미팅 바는 수 kW급 산업용 절단 부문에서 여전히 중요한 위치를 차지하고 있지만, 연평균 성장률(CAGR)은 6%에 그치며 성장세가 주춤하고 있습니다. 파이버 레이저는 기술적으로 순수한 반도체 레이저 분류에는 포함되지 않지만, 다이오드 펌핑에 의존하고 있으며 9%의 성장 궤도를 유지하고 있습니다. 협선폭 외부 공진기 다이오드(VCSEL)는 1MHz 이하의 선폭이 필요한 계측 부문의 틈새 시장을 충족시키고 있습니다. 예측 기간 동안, 자동차용 LiDAR 및 가스 모니터링 부문에서의 채택 확대에 따라 QCL이 VCSEL의 우위를 서서히 잠식하며, 반도체 레이저 시장의 수익원 다각화가 진행될 전망입니다.
지역별 분석
아시아태평양은 2025년 매출의 48.2%를 차지했으며, 이는 전 세계 VCSEL 에피택셜 웨이퍼의 60%를 중국이 차지하고, 일본이 연간 2억 개의 다이오드를 생산하고 있음을 반영합니다. 삼성의 파운드리 규모의 갈륨 비소 서비스 덕분에 웨이퍼 비용은 20% 절감되었으며, 한편 인도의 25% 보조금 제도는 새로운 조립 라인 유치를 이끌고 있습니다. 800Gbit 트랜시버가 필요한 싱가포르, 홍콩, 도쿄의 데이터센터 확장으로 인해 해당 지역의 연평균 성장률(CAGR)은 10.8%를 나타낼 것으로 예측되며, 아시아태평양은 계속해서 반도체 레이저 시장의 중심적인 위치를 차지할 전망입니다.
북미는 전 세계 실리콘 포토닉스 출하량의 40%를 차지하는 하이퍼스케일 클라우드 수요에 힘입어 2025년 매출에서 계속해서 중요한 기여 요인이 되었습니다. ‘CHIPS 법’에 따라 국내 에피택셜 웨이퍼에 자금이 지원되지만, 신규 팹의 양산 개시에는 일반적으로 36-48개월이 소요됩니다. 캐나다의 1억 캐나다 달러 규모의 포토닉스 클러스터와 USMCA에 따른 멕시코의 장비 수입 관세 면제 조치는 북미 대륙의 회복력을 강화하고 있습니다.
유럽은 독일의 TRUMPF와 ams-OSRAM, 그리고 프라운호퍼 연구소의 연구 개발을 중심으로 계속해서 중요한 수익원이 되었습니다. 호라이즌 기금과 영국의 파일럿 라인은 이종 집적 기술을 강화하고 있지만, RoHS 및 REACH 준수로 인해 6-12개월의 인증에 따른 추가 부담이 발생하고 있습니다. 중동의 연평균 성장률(CAGR) 12.9%는 LiDAR를 모빌리티 인프라에 통합하는 NEOM의 5,000억 달러 투자에 의해 견인되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the semiconductor laser market size is expected to increase from USD 9.17 billion in 2025 to USD 10.40 billion in 2026 and reach USD 17.64 billion by 2031, growing at a CAGR of 11.15% over 2026-2031.
This report is Segmented by Wavelength (Infrared, Red, Green, Blue, and Ultraviolet), Laser Type (Edge-Emitting, VCSEL, Quantum Cascade, and Fiber), Application (Communication, Medical, Military and Defense, Industrial, Instrumentation and Sensor, and Automotive), Power Output (Below 100 MW, 100 MW To 1 W, 1 W To 5 W, and Above 5 W), and Geography. Market Forecasts are in Value (USD).
Global Semiconductor Laser Market Trends and Insights
Rapid Expansion of 3D Sensing in Consumer Electronics
VCSEL array shipments for time-of-flight and structured-light modules surged as smartphone vendors broadened facial authentication and augmented-reality features, with wall-plug efficiencies topping 45% and reliable operation up to 150 °C without active cooling . Sony leveraged its back-illuminated sensor expertise to co-package VCSEL dies and CMOS detectors, reducing module footprints by 30% and lowering unit costs to below USD 2 in high-volume orders. Android flagship adoption increased from 18% in 2023 to an estimated 42% in 2025, as manufacturers sought to secure payments and differentiate their products. Euro NCAP cabin-monitoring rules triggered dual-zone VCSEL illuminators that withstand temperatures ranging from -40 °C to +85 °C, thereby tightening epitaxial uniformity requirements. Wearables add another growth vector, with smart glasses and health monitors forecast to exceed 50 million units annually by 2028 as sub-5 mm VCSEL modules enable gesture recognition and non-contact heart-rate sensing.
Emerging Demand from Silicon Photonics Interconnects
Hyperscale operators transitioned from 400G to 800G Ethernet between 2024 and 2025, integrating heterogeneously bonded III-V lasers on silicon to achieve sub-3W lane power and coupling losses of below 0.5 dB. Co-packaged optics place laser arrays directly on switch ASICs, eliminating SerDes bottlenecks and cutting latency by 40 ns, an edge prized for AI training clusters. DARPA committed USD 203 million in 2025 to lift heterogeneous integration yields toward 95%. The current wall-plug efficiency hovers near 10%, falling short of the 20% thermal envelope for air-cooled racks, which has spurred research on quantum-dot gain media and photonic-crystal cavities aimed at achieving 15% by 2027. Kerr frequency combs are displacing discrete arrays, providing 80 channels from one micro-resonator and reducing transceiver bills of materials by 35% in metro networks.
Supply Chain Volatility of Compound Semiconductor Wafers
Four suppliers control 78% of global gallium-arsenide wafer capacity, leaving the semiconductor laser market exposed to sudden demand swings. China's August 2023 curbs on gallium and germanium stretched 6-inch substrate lead times from 12 to 26 weeks and pushed spot prices 40% higher by early 2024. Hyperscale buyers locked long-term indium-phosphide contracts, crowding smaller diode makers toward less flexible gallium-arsenide alternatives. Dual-sourcing requires 18-24 months of AEC-Q100 and Telcordia GR-468-CORE testing, which delays diversification. Scaling from 4- to 6-inch wafers remains capital-intensive; a single MOCVD reactor costs USD 4 million and needs 95% utilization for a 5-year payback.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Semiconductor Laser Applications
- Government-Backed Photonics Manufacturing Initiatives
- Thermal Management Challenges at High Power Outputs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Infrared lasers accounted for 42.5% of 2025 revenue, underpinning the semiconductor laser market through 850 nm and 1,550 nm devices that dominate consumer 3D sensing and long-haul fiber links . Ultraviolet variants, although smaller in absolute dollars, will climb at a 14.8% CAGR to 2031 on EUV lithography shipments and medical UV-curable prototyping, pointing to a rising semiconductor laser market size contribution from advanced manufacturing tools.
VCSEL-based infrared modules deliver circular beams that simplify coupling, while QCL-based mid-infrared sources provide tunability for gas sensing. Ultraviolet penetration remains cost-sensitive but emerging 266 nm diodes promise higher yields and longer lifetimes. Regulatory IEC 60825 Class 3B and Class 4 limits demand sophisticated interlocks above 5 mW, influencing design budgets and time to market. As advanced logic nodes migrate below 3 nm, lithography tool vendors will propel ultraviolet demand, reinforcing its double-digit climb within the semiconductor laser market.
VCSELs captured a 37.8% share, thanks to wafer-scale testing that reduces die cost below USD 0.50, thereby safeguarding their leadership in the semiconductor laser market. QCLs, however, are racing ahead at a 16.3% CAGR through 2031, as mid-infrared spectroscopy gains regulatory tailwinds, suggesting a growing impact on the semiconductor laser market size from environmental and defense programs.
Edge-emitting bars retain relevance for multi-kilowatt industrial cutting, yet their 6% CAGR lags. Fiber lasers, although technically outside the pure semiconductor classification, depend on diode pumping and maintain a 9% trajectory. Narrow-linewidth external-cavity diodes fill metrology niches requiring <1 MHz linewidth. Over the forecast period, design wins in automotive LiDAR and gas monitoring will help QCLs erode VCSEL dominance, diversifying revenue streams within the semiconductor laser market.
Complete Report Scope:
- By Wavelength
- Infrared Lasers
- Red Lasers
- Green Lasers
- Blue Lasers
- Ultraviolet Lasers
- By Laser Type
- Edge-Emitting Lasers (EEL)
- Vertical-Cavity Surface-Emitting Lasers (VCSEL)
- Quantum Cascade Lasers
- Fiber Lasers
- Other Types
- By Application
- Communication
- Medical
- Military and Defense
- Industrial
- Instrumentation and Sensor
- Automotive
- Other Applications
- By Power Output
- Below 100 mW
- 100 mW - 1 W
- 1 W - 5 W
- Above 5 W
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
The Asia-Pacific region generated 48.2% of 2025 revenue, reflecting China's 60% share of global VCSEL epitaxial wafers and Japan's 200 million-unit annual diode output. Samsung's foundry-scale gallium-arsenide services trim wafer costs by 20%, while India's 25% subsidy attracts new assembly lines. Singapore, Hong Kong, and Tokyo data center expansions, which require 800 Gbit transceivers, are expected to support a 10.8% regional CAGR, keeping the Asia-Pacific region central to the semiconductor laser market.
North America remained a significant contributor to 2025 sales, driven by hyperscale cloud consumption, which comprises 40% of global silicon photonics shipments. The CHIPS Act will fund domestic epitaxial wafers; however, new fabs typically require 36 to 48 months to reach volume production. Canada's CAD 100 million photonics cluster and Mexico's duty-free equipment imports under USMCA strengthen continental resilience.
Europe remained a significant revenue contributor, anchored by Germany's TRUMPF and ams-OSRAM plus Fraunhofer R&D. Horizon funds and UK pilot lines enhance heterogeneous integration, while RoHS and REACH compliance add six-to-twelve-month qualification overhead. The Middle East's 12.9% CAGR is driven by NEOM's USD 500 billion investment, which incorporates LiDAR into mobility infrastructure. South America and Africa together supply 6% of the revenue, with Brazil's.
- Coherent Corp.
- Sharp Corporation
- Nichia Corporation
- IPG Photonics Corporation
- TT Electronics plc
- Sumitomo Electric Industries Ltd.
- Sheaumann Laser Inc.
- Newport Corporation (MKS Instruments Inc.)
- Panasonic Industry Co. Ltd.
- Rohm Co. Ltd.
- Hamamatsu Photonics K.K.
- Jenoptik AG
- TRUMPF Group
- ams-OSRAM AG
- Lumentum Holdings Inc.
- Broadcom Inc.
- Furukawa Electric Co. Ltd.
- Innolume GmbH
- MACOM Technology Solutions Holdings Inc.
- II-VI Incorporated (now part of Coherent)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Semiconductor Laser Applications
- 4.2.2 Growth in Fiber Laser Adoption
- 4.2.3 Preference for Semiconductor Lasers over Other Light Sources
- 4.2.4 Rapid Expansion of 3D Sensing in Consumer Electronics
- 4.2.5 Emerging Demand from Silicon Photonics Interconnects
- 4.2.6 Government-Backed Photonics Manufacturing Initiatives
- 4.3 Market Restraints
- 4.3.1 Difficulties Regarding Reliability and Testing
- 4.3.2 Supply Chain Volatility of Compound Semiconductor Wafers
- 4.3.3 Thermal Management Challenges at High Power Outputs
- 4.3.4 Stringent Export Controls on Advanced Photonics
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Wavelength
- 5.1.1 Infrared Lasers
- 5.1.2 Red Lasers
- 5.1.3 Green Lasers
- 5.1.4 Blue Lasers
- 5.1.5 Ultraviolet Lasers
- 5.2 By Laser Type
- 5.2.1 Edge-Emitting Lasers (EEL)
- 5.2.2 Vertical-Cavity Surface-Emitting Lasers (VCSEL)
- 5.2.3 Quantum Cascade Lasers
- 5.2.4 Fiber Lasers
- 5.2.5 Other Types
- 5.3 By Application
- 5.3.1 Communication
- 5.3.2 Medical
- 5.3.3 Military and Defense
- 5.3.4 Industrial
- 5.3.5 Instrumentation and Sensor
- 5.3.6 Automotive
- 5.3.7 Other Applications
- 5.4 By Power Output
- 5.4.1 Below 100 mW
- 5.4.2 100 mW - 1 W
- 5.4.3 1 W - 5 W
- 5.4.4 Above 5 W
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 United Arab Emirates
- 5.5.4.3 Turkey
- 5.5.4.4 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Nigeria
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Coherent Corp.
- 6.4.2 Sharp Corporation
- 6.4.3 Nichia Corporation
- 6.4.4 IPG Photonics Corporation
- 6.4.5 TT Electronics plc
- 6.4.6 Sumitomo Electric Industries Ltd.
- 6.4.7 Sheaumann Laser Inc.
- 6.4.8 Newport Corporation (MKS Instruments Inc.)
- 6.4.9 Panasonic Industry Co. Ltd.
- 6.4.10 Rohm Co. Ltd.
- 6.4.11 Hamamatsu Photonics K.K.
- 6.4.12 Jenoptik AG
- 6.4.13 TRUMPF Group
- 6.4.14 ams-OSRAM AG
- 6.4.15 Lumentum Holdings Inc.
- 6.4.16 Broadcom Inc.
- 6.4.17 Furukawa Electric Co. Ltd.
- 6.4.18 Innolume GmbH
- 6.4.19 MACOM Technology Solutions Holdings Inc.
- 6.4.20 II-VI Incorporated (now part of Coherent)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


