

|
시장보고서
상품코드
2122937
DWaaS(Data Warehouse-as-a-Service) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Data Warehouse As A Service - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 DWaaS(Data Warehouse-as-a-Service) 시장 규모는 74억 2,000만 달러로 추정되고 2025년 60억 9,000만 달러에서 확대해, 2031년에는 199억 4,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 21.85%를 나타낼 전망입니다.

본 보고서는 배포 모델별(퍼블릭 클라우드, 프라이빗 클라우드, 하이브리드·멀티 클라우드), 최종 사용자 기업 규모별(대기업, 중소기업), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 정부·공공 부문, 기타),서비스 유형별(엔터프라이즈 DWaaS, ODSaaS(Operational Data-Store-as-a-Service), 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 DWaaS(Data Warehouse-as-a-Service) 시장 동향 및 인사이트
클라우드 전환 및 실시간 분석의 급속한 성장
기업들은 정기적인 배치 보고에서 1초 이내에 대시보드나 예측 모델에 데이터를 공급하는 스트리밍 아키텍처로 전환하고 있습니다. ABB는 40개의 서로 다른 ERP 시스템에서 나오는 데이터를 단일 Snowflake 인스턴스로 통합하여, 생산 현황의 실시간 가시화를 통해 수백만 달러 규모의 비용 절감을 실현했습니다. 엣지 게이트웨이는 현재 생산 라인 근처에서 시간 제약이 있는 텔레메트리 데이터를 필터링하는 한편, 클라우드 데이터 웨어하우스는 용량 병목 현상 없이 복잡한 조인 처리 및 과거 동향 분석을 수행하고 있습니다. 이러한 저지연 파이프라인은 자율형 설비의 최적화, 동적 가격 책정, 즉각적인 부정 방지 대책을 지원합니다. 연결된 기기의 보급이 확대됨에 따라 실시간 분석은 계속해서 투자의 최우선 과제로 남아, 고정 노드가 아닌 데이터 수집 속도에 따라 확장 가능한 탄력적인 DWaaS 용량에 대한 수요를 뒷받침할 것입니다.
AI/ML 주도형 데이터 웨어하우스 수요
최신 데이터 웨어하우스 계층에서는 구조화된 테이블과 비구조화된 파일이 융합되어, 스토리지 계층 내에서 모델 훈련이 가능해졌습니다. Snowflake와 NVIDIA의 제휴를 통해 전용 GPU가 컴퓨팅 클러스터에 통합되어, 추론 속도를 높일 때도 데이터가 보안 경계를 벗어나지 않습니다. Databricks는 데이터 사이언스자가 대시보드를 구동하는 것과 똑같은 SQL 엔드포인트를 사용하여 페타바이트 규모의 로그에서 특징량을 구축할 수 있는 ‘레이크하우스’ 스토리지 형태를 통합하고 있습니다. 대규모 언어 모델을 활용한 자연어 쿼리 어시스턴트는 비즈니스 사용자의 분석 접근을 민주화하고 조직 전체의 도입을 촉진하는 동시에, DWaaS(Data Warehouse-as-a-Service) 시장 전체의 컴퓨팅 소비량 증가를 가져오고 있습니다.
사이버 보안 및 개인정보 보호 위험
유럽의 일반 데이터 보호 규정(GDPR(EU 개인정보보호규정)) 요건과 아시아의 새로운 현지화 관련 법규는 국경을 넘는 데이터 마이그레이션을 제한하고 있어 다국적 기업의 클라우드 전략을 복잡하게 만들고 있습니다. 기밀 자산을 제3자 클라우드에 집약하는 것은 위협 행위자들에게 더 매력적인 표적이 되므로, 기업은 전체 암호화, 제로 트러스트 액세스, 지속적인 보안 태세 모니터링을 도입할 수밖에 없습니다. 공동 책임형 보안 모델 그 자체가, 특히 전담 클라우드 보안 인력이 부족한 팀의 경우 책임 소재를 모호하게 만들 가능성이 있으며, 그 결과 조달 주기가 장기화되고 도입이 지연됩니다.
부문별 분석
2025년, 기업들이 턴키 방식에 의한 확장성과 전 세계적 가용성을 우선시한 결과, 퍼블릭 클라우드 플랫폼은 DWaaS(Data Warehouse-as-a-Service) 시장 규모의 64.80%를 차지했습니다. AWS는 서비스의 심층적인 통합을 통해 전 세계 매출의 약 34%를 확보한 반면, Microsoft Azure는 조달을 용이하게 한 Office 365의 확고한 도입 기반의 혜택을 누렸습니다. 주권 관련 규제로 인해 외부 호스팅이 금지된 지역에서는 프라이빗 클라우드 도입이 여전히 이어지고 있지만, 높은 운영 비용이 성장을 저해하고 있습니다.
기업들이 락인(lock-in)을 피하고, 지역별 비용 차이를 활용하며, 기밀성이 높은 데이터 세트를 우선적으로 주권 플랫폼에 배치하기 위해 여러 공급업체에 분석 기능을 분산함에 따라, 하이브리드 및 멀티 클라우드 도입은 2031년까지 연평균 성장률(CAGR) 23.90%를 나타낼 것으로 예측됩니다. Google Cloud의 BigQuery Omni는 물리적 데이터 마이그레이션 없이 크로스 클라우드에서 쿼리 실행을 가능하게 하여, 상호 운용성 기능이 아웃바운드 요금 및 지연 시간 증가를 어떻게 완화하는지 보여주고 있습니다. Snowflake의 개방형 Polaris Catalog는 AWS, Azure, Google Cloud에 걸친 메타데이터를 표준화하여 마이그레이션을 더욱 용이하게 합니다.
대규모 조직은 복잡한 거버넌스 요구 사항과 여러 부서에 걸친 분석 환경으로 인해 2025년 DWaaS(Data Warehouse-as-a-Service) 시장 점유율의 61.55%를 차지했습니다. 이러한 조직들은 고도의 보안 계층을 도입하고 수천 명의 동시 사용자를 지원하며, 데이터 웨어하우스를 레거시 ERP, CRM, 리스크 관리 엔진과 통합하고 있습니다.
대조적으로, 중소기업은 가장 큰 증분 수익을 주도하고 있으며, 서버리스 엔진을 통해 용량 계획의 장벽이 제거됨에 따라 2031년까지 연평균 성장률(CAGR) 25.60%로 성장할 전망입니다. 로우코드 데이터 가져오기 커넥터와 자연어 쿼리 인터페이스를 통해 비즈니스 분석가는 전담 데이터 사이언스 팀 없이도 예측 모델을 구축할 수 있어, 대기업과의 역량 격차를 좁힐 수 있습니다. 학술 연구에 따르면, 중소기업의 분석 프로그램에서 주요 성공 요인은 하드웨어 예산이 아니라 문화의 변화라고 강조되고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 38.90%를 차지했습니다. 이는 풍부한 데이터센터 용량, 유리한 클라우드 조달 정책, 기술·금융·헬스케어 등 각 산업에 걸친 탄탄한 기술 기반에 힘입은 결과입니다. 각 하이퍼스케일러 기업들은 지역별 맞춤형 AI 가속기 및 주권 클라우드 존을 지속적으로 구축하며, 프리미엄 분석 서비스 계층에 대한 수요를 뒷받침하고 있습니다. 메인주의 클라우드 전환으로 대표되는 연방 및 주 정부 기관의 노력은 공공 부문 워크로드에서 클라우드 데이터 웨어하우스의 유효성을 더욱 입증하고 있습니다.
아시아태평양은 대규모 하이퍼스케일 인프라 확충과 정부의 디지털 경제 로드맵에 힘입어 2031년 연평균 성장률(CAGR)이 24.10%로 가장 빠르게 성장하는 지역입니다. 싱가포르의 GovTech와 같은 공공 부문의 모범 사례는 규제 명확화와 정부 주도의 클라우드 교육이 기업의 도입 주기를 단축한다는 점을 여실히 보여주고 있습니다.
유럽에서는 높은 분석 수요와 엄격한 주권 관련 법규 간의 균형이 이루어지고 있습니다. 각 벤더는 이에 대응하여 EU 전용 리전, 기밀 컴퓨팅 엔클레이브, 주권 메타데이터 서비스 제공을 시작했습니다. 다국적 금융 기관들은 국경을 넘는 리스크 분석 기능을 유지하면서도 현지 데이터 거주 규정을 준수하기 위해 분산형 데이터 메쉬 아키텍처를 도입하고 있습니다. 남미와 중동 및 아프리카에서는 전자상거래의 확대 및 스마트 시티 구상과 관련하여 규모는 작지만 성장세가 두드러진 비즈니스 기회가 나타나고 있습니다. 그러나 인프라 격차와 거시경제의 변동으로 인해 단기적인 보급 속도는 둔화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 동향
KTH 26.09.08According to Mordor Intelligence, data warehouse as a service market size in 2026 is estimated at USD 7.42 billion, growing from 2025 value of USD 6.09 billion with 2031 projections showing USD 19.94 billion, growing at 21.85% CAGR over 2026-2031.
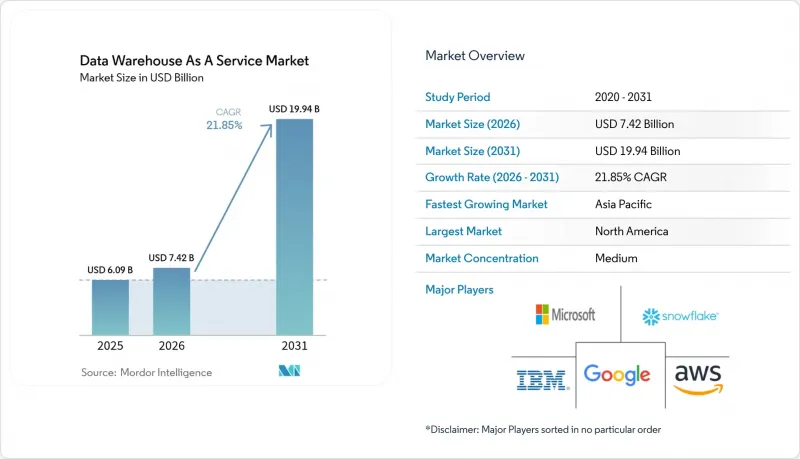
This report is Segmented by Deployment Model (Public Cloud, Private Cloud, Hybrid/Multi-cloud), End-User Enterprise Size (Large Enterprises, Small and Medium Enterprises), End-User Industry (BFSI, Government and Public Sector, and More), Service Type (Enterprise DWaaS, Operational Data-Store As A Service, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Data Warehouse As A Service Market Trends and Insights
Cloud Migration and Real-Time Analytics Boom
Enterprises are shifting from periodic batch reporting to streaming architectures that feed sub-second dashboards and predictive models. ABB consolidated data from 40 disparate ERP systems into a single Snowflake instance and unlocked multimillion-dollar savings through real-time production visibility . Edge gateways now filter time-sensitive telemetry close to manufacturing lines, while cloud data warehouses execute complex joins and historical trend analyses without capacity bottlenecks. These low-latency pipelines support autonomous-equipment optimization, dynamic pricing, and instantaneous fraud controls. As more connected devices proliferate, real-time analytics will remain a top spending priority, reinforcing demand for elastic DWaaS capacity that scales on ingestion rates rather than fixed nodes.
AI/ML-Driven Warehousing Demand
Modern data-warehouse layers blend structured tables with unstructured files, enabling model training inside the storage tier. Snowflake's collaboration with NVIDIA embeds specialized GPUs alongside compute clusters so data never leaves the security perimeter during inference acceleration . Databricks integrates lakehouse storage formats that let data scientists build features over petabyte-scale logs using the same SQL endpoints powering dashboards. Natural-language query assistants driven by large language models democratize analytics access for business users, fueling broader organizational adoption and increasing overall compute consumption across the data warehouse as a service market.
Cyber-Security and Privacy Risks
General Data Protection Regulation requirements in Europe and new localization statutes in Asia restrict cross-border data movement, complicating multinational cloud strategies. Consolidating sensitive assets inside third-party clouds heightens the appeal for threat actors, forcing enterprises to deploy pervasive encryption, zero-trust access and continuous posture monitoring. The shared-responsibility security model itself can blur accountability lines, especially for teams lacking dedicated cloud-security talent, thereby extending procurement cycles and slowing adoption.
Other drivers and restraints analyzed in the detailed report include:
- BFSI Digital-First Road-Maps
- Shift to Consumption-Based Pricing
- Unpredictable Cloud Cost Sprawl
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Public-cloud platforms held 64.80% of the data warehouse as a service market size in 2025 as enterprises prioritized turnkey scalability and global availability. AWS captured roughly 34% of worldwide revenue thanks to deep service integration, while Microsoft Azure benefited from established Office 365 footprints that eased procurement. Private-cloud instances persist where sovereignty mandates preclude external hosting, but higher operational overhead tempers growth.
Hybrid and multi-cloud deployments are projected to record a 23.90% CAGR through 2031 as firms distribute analytics across providers to avoid lock-in, exploit regional cost differentials and place sensitive datasets on preferred sovereign platforms. Google Cloud's BigQuery Omni allows cross-cloud querying without physical data moves, showing how interoperability features reduce egress fees and latency penalties . Snowflake's open Polaris Catalog further eases migration by standardizing metadata across AWS, Azure and Google Cloud.
Large organizations controlled 61.55% of the 2025 data warehouse as a service market share due to complex governance needs and multi-department analytics estates. They deploy advanced security layers, support thousands of concurrent users and integrate warehouses with legacy ERP, CRM and risk engines.
In contrast, SMEs will drive the highest incremental revenue, expanding at a 25.60% CAGR through 2031 as serverless engines remove capacity-planning hurdles. Low-code ingestion connectors and natural-language query interfaces allow business analysts to launch predictive models without dedicated data-science teams, narrowing capability gaps versus larger peers. Academic studies highlight cultural change as the primary success factor for SME analytics programs, not hardware budgets.
Complete Report Scope:
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid / Multi-cloud
- By End-user Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By End-user Industry
- BFSI
- Government and Public Sector
- Healthcare and Life Sciences
- Retail and E-commerce
- Telecom and IT
- Media and Entertainment
- Manufacturing
- By Service Type
- Enterprise DWaaS
- Operational Data-store as a Service
- Data Lakehouse as a Service
- Analytics Acceleration Services
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 38.90% of global revenue in 2025, buoyed by abundant data-center capacity, favorable cloud procurement policies and a deep skills base across technology, finance and healthcare verticals. Hyperscalers continuously launch region-specific AI accelerators and sovereign-cloud zones, sustaining demand for premium analytics tiers. Federal and state agencies, exemplified by the State of Maine's cloud migration, further validate cloud warehouses for public-sector workloads .
Asia-Pacific is the fastest-growing region with a 24.10% CAGR through 2031, supported by massive hyperscale build-outs and government digital-economy roadmaps. Public-sector exemplars such as Singapore's GovTech highlight how regulatory clarity and state-sponsored cloud training shorten enterprise adoption cycles.
Europe balances high analytics demand with stringent sovereignty legislation. Vendors respond by launching EU-only regions, confidential computing enclaves and sovereign-metadata services. Multinational financial institutions implement distributed data-mesh architectures to comply with local residency rules while preserving cross-border risk analytics. South America plus the Middle East & Africa exhibit growing, albeit smaller, opportunity pools linked to e-commerce expansion and smart-city initiatives; however, infrastructure gaps and macro-economic volatility moderate near-term uptake.
- Amazon Web Services Inc.
- Microsoft Corporation
- Google LLC
- Snowflake Inc.
- IBM Corporation
- Oracle Corporation
- SAP SE
- Teradata Corp.
- Cloudera Inc.
- Databricks Inc.
- Micro Focus International plc
- Yellowbrick Data
- ClickHouse Inc.
- Dremio Corporation
- Alibaba Cloud
- Huawei Cloud
- Firebolt Analytics Ltd.
- Vertica (Micro Focus)
- Exasol AG
- Actian Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Market Definition and Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud migration and real-time analytics boom
- 4.2.2 AI/ML-driven warehousing demand
- 4.2.3 BFSI digital-first road-maps
- 4.2.4 Shift to consumption-based pricing
- 4.2.5 Edge-to-cloud low-latency warehousing
- 4.2.6 Green warehousing and carbon reporting focus
- 4.3 Market Restraints
- 4.3.1 Cyber-security and privacy risks
- 4.3.2 Unpredictable cloud cost sprawl
- 4.3.3 Vendor lock-in concerns
- 4.3.4 Shortage of FinOps / data-observability skills
- 4.4 Value Chain Analysis
- 4.5 Evaluation of Critical Regulatory Framework
- 4.6 Impact Assessment of Key Stakeholders
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 Public Cloud
- 5.1.2 Private Cloud
- 5.1.3 Hybrid / Multi-cloud
- 5.2 By End-user Enterprise Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium Enterprises
- 5.3 By End-user Industry
- 5.3.1 BFSI
- 5.3.2 Government and Public Sector
- 5.3.3 Healthcare and Life Sciences
- 5.3.4 Retail and E-commerce
- 5.3.5 Telecom and IT
- 5.3.6 Media and Entertainment
- 5.3.7 Manufacturing
- 5.4 By Service Type
- 5.4.1 Enterprise DWaaS
- 5.4.2 Operational Data-store as a Service
- 5.4.3 Data Lakehouse as a Service
- 5.4.4 Analytics Acceleration Services
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 Google LLC
- 6.4.4 Snowflake Inc.
- 6.4.5 IBM Corporation
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Teradata Corp.
- 6.4.9 Cloudera Inc.
- 6.4.10 Databricks Inc.
- 6.4.11 Micro Focus International plc
- 6.4.12 Yellowbrick Data
- 6.4.13 ClickHouse Inc.
- 6.4.14 Dremio Corporation
- 6.4.15 Alibaba Cloud
- 6.4.16 Huawei Cloud
- 6.4.17 Firebolt Analytics Ltd.
- 6.4.18 Vertica (Micro Focus)
- 6.4.19 Exasol AG
- 6.4.20 Actian Corp.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-need Assessment


