|
시장보고서
상품코드
2122960
이소프렌 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Isoprene - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
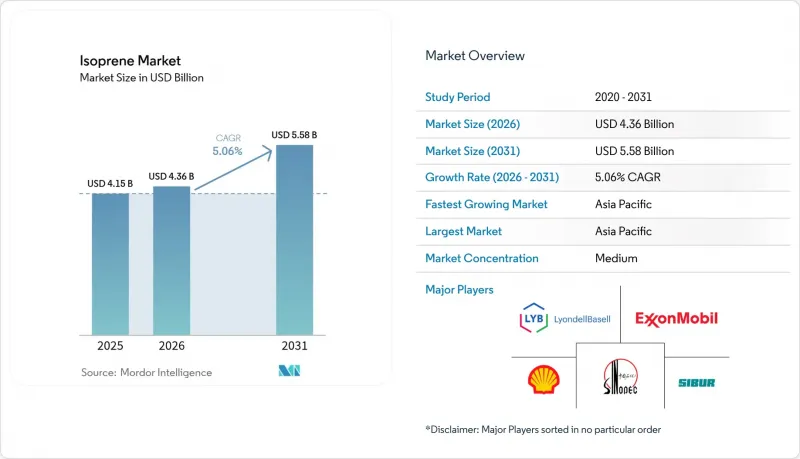
에 의하면, 이소프렌 시장 규모는 2025년 41억 5,000만 달러로 평가되었고, 2026년에는 43억 6,000만 달러로 추정되고, 2026-2031년 CAGR 5.06%로 성장을 지속할 전망이며, 2031년까지 55억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 등급별(폴리머 등급 및 화학 등급), 제조 경로별(석유화학계 C5 크래킹, 바이오 발효, 바이오에탄올의 촉매 전환), 용도별(타이어, 헬스케어, 의류 및 신발, 기타 용도), 그리고 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 이소프렌 시장 동향 및 인사이트
전기차(EV)를 주축으로 한 고성능 타이어용 합성고무 수요의 급증
전기차(EV)의 토크 부하 증가로 인해 우수한 인장 강도와 낮은 구름 저항을 겸비한 폴리머가 요구되고 있으며, 타이어 제조업체들은 천연 고무로는 보장할 수 없는 안정적인 이소프렌 배합을 추구하고 있습니다. 미국 환경보호청(EPA)에 따르면, 연간 30억 개 이상의 타이어가 생산되고 있으며, 전기차 전용 컴파운드에는 배터리 주행 거리를 유지하기 위한 내구성 향상이 요구되고 있습니다. 미쉐린의 바이오 합성 고무 연구는 타이어 컴파운드의 재설계가 시급함을 여실히 보여주고 있습니다. 아시아태평양의 전기차 생산 집중은 해당 지역의 이소프렌 수요를 확대시키고 있으며, 이에 따라 일반적인 교체 주기를 넘어선 수요의 구조적 상승을 지속시키고 있습니다.
석유 유래 원료의 위험을 줄이기 위한 바이오 이소프렌 제조 공정에 대한 투자
IFPEN의 ‘Atol’ 및 ‘BioButterfly’ 프로젝트와 같은 발효 기술은 재생 가능한 에탄올을 폴리머 등급의 이소프렌으로 전환하는 것의 기술적 실현 가능성을 입증하고 있습니다. Global Bioenergies사의 산업용 이소부텐 생산과 Insempla사의 2,000만 달러 규모의 자금 조달 라운드는 재생 가능한 C5 화학 물질에 대한 투자자들의 관심이 높아지고 있음을 여실히 보여주고 있습니다. 비용 평형(cost parity) 예측에 따르면, 특히 바이오에탄올이 과잉 공급되는 지역에서 예측 기간 내에 발효법이 석유 기반 제조 방식에 비용 면에서 근접할 것으로 전망됩니다.
원유 원료 가격 변동이 생산자의 이익 폭을 확대
정유시설의 가동률 변동은 C5 분획공급량에 영향을 미치며, 비통합형 가공업체의 경우 투입 비용 상승을 초래하고, 원유 가격이 급등할 때는 이익률을 압박합니다. 바이오 제조 경로는 가격 안정성을 제공하지만, 현재 사탕수수 유래 옵션은 화석 연료 유래 경로에 비해 280%에서 752%의 프리미엄이 부과되고 있어, 단기적인 경쟁력 유지가 과제로 대두되고 있습니다.
부문 분석
폴리머 등급은 2025년 매출의 62.38%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 4.98%로 확대될 것으로 예측됩니다. 이는 전기차용 타이어에서 균일한 경화 속도에 대한 수요를 반영한 것입니다. 생산자들은 분지도를 낮추고 분자량을 증가시키기 위한 첨단 중합 기술을 채택하고 있으며, 이를 통해 발열을 억제하고 타이어의 내구성을 향상시키는 데 기여하고 있습니다. 화학용 등급은 여전히 틈새 중간체로 사용되고 있으나, 자동차 및 헬스케어 분야에서 폴리머의 일관성이 중요시됨에 따라 시장 점유율은 점차 축소되고 있습니다. 외과용 의료기기에 대한 고순도 요구 사항은 프리미엄 가격을 유지하며, 공급 계약을 자동차 수요의 경기 변동으로부터 보호하고 있습니다.
지역별 분석
아시아태평양의 이소프렌 시장 규모는 2025년에 21억 2,000만 달러에 달한 것으로 평가되었으며, 자동차 OEM 제조업체와의 지리적 근접성으로 인해 운송 비용을 절감할 수 있어 지역공급 안정성이 강화되고 있습니다. 중국은 천연고무와 합성고무 간의 생산 능력 격차를 해소하는 가공 기술의 진보를 통해 엘라스토머 자급자족을 위한 투자를 진행하고 있습니다. 인도의 화학 및 산업 분야 성장은 하류 수요를 확대시키고 있는 반면, 태국의 바이오에틸렌 허브는 재생 가능한 C5 통합을 위한 발판이 되고 있습니다.
북미의 생산자들은 지속 가능한 타이어와 의료기기를 요구하는 소비자들의 압력에 기업들이 주목하고 있음을 반영하여, 바이오폴리머 생산 능력을 연간 260kt까지 확대되고 있습니다. 유럽연합(EU)의 탈탄소화 정책은 발효 및 촉매 전환 플랫폼에 대한 투자를 촉진하고 있습니다. 캐나다 보건부의 발암성 물질 분류는 조달에 영향을 미치고 있으며, OEM 기업들은 견고한 안전 프로토콜을 갖춘 공급업체를 우선적으로 선택하고 있습니다. 남미의 사탕수수 밸류체인은 비용 프리미엄이 축소된다면 전략적 기회를 제공할 것입니다. 중동의 복합 시설은 저렴한 나프타 원료와 아프리카의 신흥 자동차 허브로 이어지는 수출 물류를 결합하고 있는 반면, 아프리카 수요 증가는 자동차 조립 확대와 인프라 개선에 달려 있습니다.
기타 혜택 :
- 엑셀 형식 시장 전망(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the isoprene market size is expected to grow from USD 4.15 billion in 2025 to USD 4.36 billion in 2026 and is forecast to reach USD 5.58 billion by 2031 at 5.06% CAGR over 2026-2031.
This report is Segmented by Grade (Polymer Grade and Chemical Grade), Production Route (Petrochemical C5 Cracking, Bio-Based Fermentation, and Catalytic Conversion of Bio-Ethanol), Application (Tyres, Healthcare, Apparels and Footwear, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Isoprene Market Trends and Insights
EV-Led Surge in Synthetic-Rubber Demand for High-Performance Tires
Higher torque loads in EVs mandate polymers with superior tensile strength and reduced rolling resistance, directing tire makers toward consistent isoprene formulations that natural rubber cannot guarantee. The US EPA notes over 3 billion tires produced annually, with EV-specific compounds requiring enhanced durability for battery-range preservation. Michelin's exploration of bio-based synthetic rubber underscores the redesign imperative facing tire compounds. Asia-Pacific's EV manufacturing concentration magnifies regional pull for isoprene, thereby sustaining a structural uplift in demand beyond the typical replacement cycle.
Investments in Bio-Based Isoprene Routes to Cut Petro-Feedstock Risk
Fermentation technologies such as IFPEN's Atol and the BioButterfly project confirm the technical feasibility of converting renewable ethanol into polymer-grade isoprene. Global Bioenergies' industrial isobutene output and Insempra's USD 20 million funding round highlight the growing investor appetite for renewable C5 chemistry. Cost-parity forecasts indicate fermentation will approach petro-routes within the forecast window, particularly in regions with surplus bio-ethanol.
Crude-Oil Feedstock Price Volatility Widening Producer Margins
Refinery utilization swings alter C5 fraction availability, pushing input costs higher for non-integrated processors and squeezing margins during crude-price spikes. Although bio-based routes offer price stability, current sugarcane-derived options command premiums between 280% and 752% over fossil routes, challenging near-term competitiveness.
Other drivers and restraints analyzed in the detailed report include:
- Rising Healthcare Demand for Ultra-Pure Polyisoprene Medical Devices
- Asia-Pacific Automotive Capacity Expansion Boosting C5 Extraction
- Stricter Workplace Exposure Limits for Isoprene Monomer (Carcinogen)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polymer grade commanded 62.38% of 2025 revenue and is forecast to advance at 4.98% CAGR to 2031, mirroring demand for uniform cure rates in EV tires. Producers deploy advanced polymerization to achieve lower branching and higher molecular weights that curb heat build-up, benefiting tire longevity. Chemical grade continues serving niche intermediates but faces gradual share erosion as automotive and healthcare sectors value polymer consistency. Elevated purity requirements for surgical devices sustain premium pricing and insulate supply contracts from cyclical auto demand.
Complete Report Scope:
- By Grade
- Polymer Grade
- Chemical Grade
- By Production Route
- Petrochemical C5 Cracking
- Bio-based Fermentation
- Catalytic Conversion of Bio-Ethanol
- By Application
- Tyres
- Heathcare
- Apparels and Footwear
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's isoprene market size hit USD 2.12 billion in 2025, and proximity to automotive OEMs offers freight savings that strengthen regional supply stability. China invests in elastomer self-sufficiency through processing advancements that bridge natural and synthetic rubber capability gaps. India's chemical-industrial growth broadens downstream demand, while Thailand's bio-ethylene hub creates a springboard for renewable C5 integration.
North American producers expand bio-polymer capacity to 260 kt per year, reflecting corporate attention to consumer pressure for sustainable tires and medical devices. The European Union's decarbonization policies steer investment toward fermentation and catalytic conversion platforms. Health Canada's carcinogen classification influences procurement, prompting OEMs to favor suppliers with robust safety protocols. South America's sugarcane value chain presents a strategic opportunity once cost premiums shrink. Middle Eastern complexes bundle inexpensive Naphtha feed with export logistics that reach Africa's emerging automotive hubs, while African demand growth hinges on vehicle assembly expansion and infrastructure improvement.
- Braskem
- Chevron Phillips Chemical Company LLC.
- China Petrochemical Corporation
- ENEOS Corporation
- Exxon Mobil Corporation
- JSR Corporation
- Kraton Corporation
- KURARAY CO., LTD.
- LLC Tolyattikauchuk
- LOTTE Chemical CORPORATION
- LyondellBasell Industries Holdings B.V.
- PJSC SIBUR Holding
- Shell plc
- The Goodyear Tire & Rubber Company
- Zeon Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV-led surge in synthetic-rubber demand for high-performance tyres
- 4.2.2 Investments in bio-based isoprene routes to cut petro-feedstock risk
- 4.2.3 Rising healthcare demand for ultra-pure polyisoprene medical devices
- 4.2.4 Asia-Pacific automotive capacity expansion boosting C5 extraction
- 4.2.5 3-D-printed footwear adopting isoprene-based thermoplastic elastomers
- 4.2.6 Low-VOC interior adhesives shifting towards low-odor polyisoprene
- 4.3 Market Restraints
- 4.3.1 Crude-oil feedstock price volatility widening producer margins
- 4.3.2 Stricter workplace exposure limits for isoprene monomer (carcinogen)
- 4.3.3 Fermentation scale-up bottlenecks delaying commercial BioIsoprene
- 4.3.4 Competition from guayule & dandelion natural-rubber alternatives
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Grade
- 5.1.1 Polymer Grade
- 5.1.2 Chemical Grade
- 5.2 By Production Route
- 5.2.1 Petrochemical C5 Cracking
- 5.2.2 Bio-based Fermentation
- 5.2.3 Catalytic Conversion of Bio-Ethanol
- 5.3 By Application
- 5.3.1 Tyres
- 5.3.2 Heathcare
- 5.3.3 Apparels and Footwear
- 5.3.4 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Braskem
- 6.4.2 Chevron Phillips Chemical Company LLC.
- 6.4.3 China Petrochemical Corporation
- 6.4.4 ENEOS Corporation
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 JSR Corporation
- 6.4.7 Kraton Corporation
- 6.4.8 KURARAY CO., LTD.
- 6.4.9 LLC Tolyattikauchuk
- 6.4.10 LOTTE Chemical CORPORATION
- 6.4.11 LyondellBasell Industries Holdings B.V.
- 6.4.12 PJSC SIBUR Holding
- 6.4.13 Shell plc
- 6.4.14 The Goodyear Tire & Rubber Company
- 6.4.15 Zeon Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-needs assessment
- 7.2 Introducing New Manufacturing Techniques to Reduce Hazardous Waste