

|
시장보고서
상품코드
2123003
환경 보건 및 안전(EHS) 소프트웨어 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Environmental Health And Safety (EHS) Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
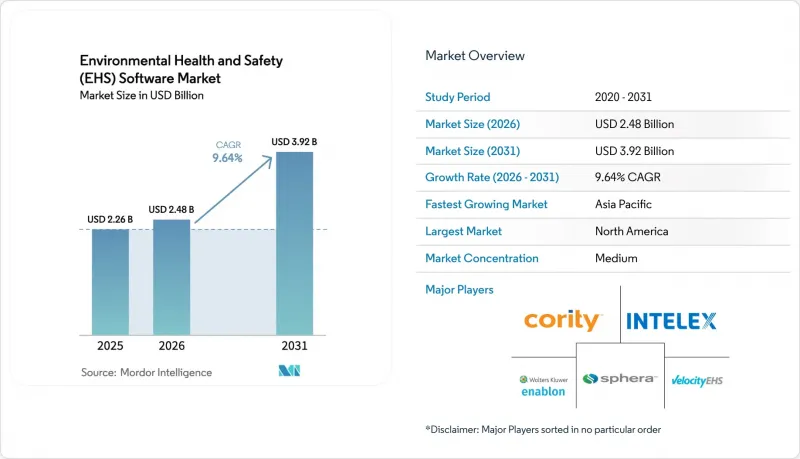
에 의하면, 환경 보건 및 안전(EHS) 소프트웨어 시장 규모는 2025년에 22억 6,000만 달러로 평가되었고 2026년 24억 8,000만 달러에서 2031년까지 39억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.64%를 나타낼 전망입니다.
본 보고서는 배포 방식(클라우드, On-Premise), 구성 요소(소프트웨어, 서비스), 최종 사용자 산업(석유 및 가스, 에너지·유틸리티, 식음료, 기타), 솔루션 유형(사고·안전 관리, 감사·검사, 기타), 조직 규모(대기업, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 환경 보건 및 안전(EHS) 소프트웨어 시장 동향 및 인사이트
규제 집행 강화 및 배상 책임 위험 증가
미국 직업안전보건청(OSHA)은 2025년에 고의적 위반에 대한 최고 벌금을 16만 5,514 달러로, 중대한 위반에 대한 최고 벌금을 1만 6,550 달러로 인상하고, 연례 조정을 매년 1월에 상승하는 지수 연동형 모델로 전환했습니다. 위반 정보가 공개되는 데이터베이스로 인해 평판 리스크가 높아짐에 따라, 기업들은 감사 기록 및 시정 조치 기록을 자동화하도록 권장받고 있습니다. 이와 병행하여 유럽연합(EU)은 직업안전보건 지침을 ISO 45001과 조화시키고, 다국적 기업들에게 브뤼셀과 워싱턴 양측의 요건을 모두 충족하는 단일 세계 플랫폼으로의 전환을 촉구하고 있습니다. Chevron의 ‘운영 우수성 관리 시스템(Operation Excellence Management System)’은 2025-2028년 주기에서 ISO 14001:2015 및 ISO 45001:2018 재인증을 획득했습니다. 이는 통합형 소프트웨어가 환경 및 안전 양 측면에서의 규정 준수를 어떻게 뒷받침하고 있는지를 보여줍니다. 중국과 한국에서 개인 책임에 관한 법규가 강화됨에 따라, 예측 가능하고 감사 가능한 시스템의 도입이 비즈니스 측면에서 유익하다는 사실이 더욱 입증되고 있습니다.
ESG 및 지속가능성 보고 의무의 확대
미국 증권거래위원회(SEC)가 2024년 3월에 발표한 기후 변화 정보 공시 규정에 따르면, 대규모 조기 제출 의무가 있는 기업은 보증된 스코프 1 및 스코프 2 배출량 제출이 의무화되어 있으며, 이에 따라 기업들은 환경, 안전, 탄소 데이터 스트림을 통합하는 플랫폼으로의 전환을 요구받고 있습니다. 유럽의 ‘기업 지속가능성 보고 지침’에서는 상세한 공시 대상이 5만 개사로 확대되었으며, 여기에는 해당 지역에서 대규모 사업 활동을 수행하는 비EU 기업도 포함됩니다. ESG 및 탄소 모듈에 대한 수요는 연평균 성장률(CAGR) 11.68%로 증가하고 있습니다. 이는 이러한 도구가 계량기, 자산 관리 시스템, 공급업체 포털에서 데이터를 자동으로 수집하여 공시 템플릿에 매핑하기 때문입니다. Sphera와 Evonik이 제공하는 TUV 인증 자동 수명 주기 평가(LCA) 도구는 제품의 환경 영향 보고 주기를 몇 주에서 몇 시간으로 단축하여 운영상의 이점을 두드러지게 하고 있습니다.
AI를 활용한 예측형 안전 규정 준수 분석
Cority의 Cortex AI 엔진은 아차 사고 기록, 센서 원격 측정 데이터, 유지보수 데이터를 분석하여 사고가 발생하기 전에 새로운 위험을 식별하고 대책을 제안합니다. Intelex는 비정상적인 배출량이나 잘못된 센서 입력을 자동으로 강조 표시하는 실시간 데이터 품질 검증 기능을 출시하여 규제 당국에 대한 잘못된 보고 가능성을 줄이고 있습니다. 조기 도입 기업들로부터는 기록 대상인 부상률이 측정 가능한 수준으로 감소했으며, 보험사가 예측 위험 대시보드를 참조하기 시작함에 따라 보험료가 인하되었다는 보고가 접수되고 있습니다.
부문 분석
EHS 소프트웨어 시장의 서비스 부문은 11.42%의 연평균 성장률(CAGR)을 보일 것으로 예상되며, 2025년 매출의 70.22%를 소프트웨어가 차지할 것으로 보임에도 불구하고 소프트웨어 매출 성장률을 상회할 전망입니다. 현황 매핑, API 개발, 다국어 사용자 교육을 포함한 컨설팅 계약은 세계 확장의 경우 일반적으로 12-18개월에 이릅니다. 매니지드 서비스는 자본 지출(CapEx)보다 운영 비용(OpEx)을 선호하는 중견 기업들로부터 지지를 받고 있으며, 업그레이드, 규제 규칙 업데이트, 헬프데스크 지원을 벤더에 맡기고 있습니다.
AI 도입으로 서비스 파이프라인이 확대되고 있습니다. 데이터 사이언스 팀은 머신러닝 모델을 조정하고, 리스크 점수를 검증하며, 원시 예측치를 이사회에 제시할 수 있는 인사이트력으로 변환하는 경영진용 대시보드를 구축하고 있습니다. 새로운 SEC 및 EU 규정에 따른 공시 정보 인증을 위한 병행적인 노력이 보증 업무 및 데이터 계보 검증에 대한 수요를 창출하고 있으며, 이 또한 예산을 서비스 제공업체 쪽으로 기울게 하고 있습니다. 인시던트, 감사, ESG, 교육 도구의 모듈화로 인해 통합 지점이 두 배로 증가함에 따라, 2031년까지 이 분야가 서비스 시장에서 가장 빠르게 성장하는 요소로 남아 있을 것으로 확실시됩니다.
환경 보건 및 안전(EHS) 소프트웨어 시장에서 클라우드 도입은 2025년에 74.52%의 점유율을 차지하며, 2031년까지 연평균 성장률(CAGR) 12.84%를 기록할 전망입니다. 지속적인 제공을 통해 공급업체는 새로운 OSHA 양식이나 EU 부속서가 발표된 지 며칠 이내에 규정 준수 템플릿을 배포할 수 있지만, On-Premise 환경의 고객은 주말 유지보수 시간이나 직원의 초과 근무 없이는 이러한 속도를 따라잡을 수 없습니다. 구독형 가격 책정은 비용을 균등하게 분산시키기 때문에 현금 흐름과 수익의 균형을 맞추어야 하는 기업에게 유리합니다.
On-Premise 도입은 국방, 원자력, 데이터 주권법에 따라 국내 호스팅이 의무화된 일부 중국 사업에서 여전히 남아 있습니다. 그러나 5년간의 총 소유 비용(TCO) 추산에 따르면, 하드웨어 업데이트 주기, 데이터베이스 패치 적용, 재해 복구 훈련 비용을 포함할 경우 클라우드 도입이 30-40% 더 저렴하다는 것이 밝혀졌습니다. IoT 센서의 보급도 이러한 추세를 뒷받침하고 있습니다. 진동, 가스, 대기질 데이터를 클라우드 대시보드에 직접 스트리밍하는 것이 모든 거점에 엣지 서버를 설치하는 것보다 용이하기 때문입니다.
지역별 분석
북미는 2025년 매출의 37.46%를 차지했습니다. 이는 OSHA(미국 직업안전보건청)의 제재 강화와, 사실상 지속적인 탄소 회계를 의무화하는 SEC(미국 증권거래위원회)의 기후 변화 정보 공개 규정에 힘입은 결과입니다. 포춘 500대 기업에서의 높은 보급률로 인해, 여전히 클립보드나 구식 데이터베이스를 계속 사용하고 있는 중견 제조업체 및 건설 도급업체를 둘러싼 경쟁이 치열해지고 있습니다. 벤더들의 마케팅에서는 예측 리스크 대시보드를 통해 실현되는 산재보험료 절감이 점점 더 강조되고 있으며, 즉각적인 비용 절감을 원하는 CFO들의 공감을 얻고 있습니다.
유럽은 이에 근소한 차이로 뒤를 잇고 있습니다. 그 원동력은 27개 회원국 전체에 걸쳐 상세하고 디지털화된 정보 공개를 의무화하는 ‘기업 지속가능성 보고 지침’입니다. ISO 45001 인증률은 독일, 프랑스,영국에서 가장 높아, 감사 워크플로우와 지속가능성 지표를 통합하는 플랫폼에 대한 지역적 수요를 뒷받침하고 있습니다. 클라우드 도입은 GDPR(EU 개인정보보호규정) 요건으로 인해 제약을 받고 있지만, 소버린 클라우드 제공을 통해 데이터 전송에 대한 우려가 완화되면서 화학 및 항공우주 기업의 성장을 가속하고 있습니다.
아시아태평양은 환경 보건 및 안전(EHS) 소프트웨어 시장에서 연평균 성장률(CAGR) 10.48%를 기록하며 가장 빠르게 성장하고 있는 지역입니다. 중국에서 개정된 ‘노동안전법’은 중대 사고 발생 시 경영진에게 형사 책임을 부과하는 것으로, 이에 따라 제조업체들은 실시간 사고 보고 시스템 및 디지털 작업 허가 시스템 도입을 서둘러야 하는 상황에 놓였습니다. 인도에서는 ISO 45001에 관한 공식 지침과 새로운 디지털 부상 보고 포털이 마련되어, 현지 공장이 다국적 기업의 감사 요건을 준수할 수 있게 되었습니다. 한국에서는 2022년부터 시행되어 2024년 이후 엄격하게 적용될 ‘중대사고처벌법’이 조선 및 전자 산업 공급망 전반에 걸친 투자를 촉진하고 있습니다.
중동 및 아프리카에서는 사우디아라비아와 아랍에미리트의 국영 석유 회사들이 ‘비전 2030’의 다각화 목표를 달성하기 위해 하청업체와의 계약에 EHS 조항을 포함시키는 움직임이 가속화되고 있습니다. 역사적으로 높은 사망률로 고생해 온 남아프리카의 광업 부문은 지질공학적 위험을 거의 실시간으로 시각화하는 클라우드 대시보드로의 전환을 추진하고 있습니다. 남미에서는 도입 속도에 차이가 보입니다. 브라질에서는 주목을 받은 댐 및 해양 시설 사고를 계기로 Petrobras와 Vale가 전사적 도입에 자금을 투자하며 주도적인 역할을 하고 있는 반면, 규모가 작은 안데스 국가들 시장에서는 도입이 아직 초기 단계에 머물러 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the environmental health and safety software market size was valued at USD 2.26 billion in 2025 and is estimated to grow from USD 2.48 billion in 2026 to reach USD 3.92 billion by 2031, at a CAGR of 9.64% during the forecast period (2026-2031).
This report is Segmented by Deployment Mode (Cloud, and On-Premise), Component (Software, and Services), End-User Vertical (Oil and Gas, Energy and Utility, Food and Beverage, and More), Solution Type (Incident and Safety Management, Audit and Inspection, and More), Organization Size (Large Enterprises, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Environmental Health And Safety (EHS) Software Market Trends and Insights
Stringent Regulatory Enforcement and Rising Liability Exposure
United States OSHA lifted maximum penalties for willful violations to USD 165,514 and serious violations to USD 16,550 in 2025, moving annual adjustments to an indexed model that climbs each January. Public violation databases heighten reputational risk, prompting companies to automate audit trails and corrective-action records. In parallel, the European Union harmonized occupational safety directives with ISO 45001, nudging multinationals toward a single global platform that satisfies both Brussels and Washington. Chevron's Operations Excellence Management System earned ISO 14001:2015 and ISO 45001:2018 recertification for the 2025-2028 cycle, illustrating how integrated software underpins dual environmental and safety compliance. Heightened personal-liability statutes in China and South Korea further reinforce the business case for predictive, auditable systems.
Expansion of ESG and Sustainability Reporting Mandates
The United States SEC's March 2024 climate-disclosure rules require large accelerated filers to furnish assured Scope 1 and Scope 2 emissions, nudging firms toward platforms that merge environmental, safety, and carbon data streams. Europe's Corporate Sustainability Reporting Directive extends detailed disclosures to 50,000 entities, including non-EU companies with sizable regional activity. Demand for ESG and carbon modules is climbing at an 11.68% CAGR because these tools automate data pulls from meters, asset systems, and supplier portals, then map them into disclosure templates. Sphera and Evonik's TUV-certified automated life-cycle assessment tool slashes product-footprint reporting cycles from weeks to hours, underscoring the operational upside.
AI-Driven Predictive Safety and Compliance Analytics
Cority's Cortex AI engine mines near-miss logs, sensor telemetry, and maintenance data to flag emerging risks and recommend interventions before incidents materialize. Intelex released real-time data-quality validation that automatically highlights anomalous emissions figures and faulty sensor inputs, reducing the likelihood of erroneous regulatory filings. Early adopters report measurable declines in recordable injury rates and lower insurance premiums as underwriters begin referencing predictive-risk dashboards.
Other drivers and restraints analyzed in the detailed report include:
- SaaS-First, Mobile-First EHS Platforms Reduce TCO
- High Upfront Implementation and Change-Management Cost
- Cyber-Security and Data-Privacy Concerns in Cloud Roll-Outs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The services slice of the EHS software market posted an 11.42% CAGR outlook, outperforming software revenue growth despite software commanding 70.22% of 2025 turnover. Consulting engagements covering current-state mapping, API development, and multi-language user training routinely span 12 to 18 months for global roll-outs. Managed services appeal to mid-sized firms that prefer OpEx over CapEx, handing vendors the keys to upgrades, regulatory-rule updates, and help-desk support.
AI implementations are enlarging the services pipeline. Data-science teams tune machine-learning models, validate risk scores, and craft executive dashboards that convert raw predictions into board-ready insights. Parallel efforts to certify disclosures under new SEC and EU rules generate demand for assurance and data-lineage validation, again tilting budgets toward service providers. The modularization of incident, audit, ESG, and training tools multiplies integration points, ensuring that services remain the fastest-growing component through 2031.
Cloud deployments held 74.52% share in 2025 and are tracking a 12.84% CAGR through 2031 in the environmental health and safety (EHS) software market. Continuous delivery lets vendors push regulatory templates within days of a new OSHA form or EU annex, a cadence on-premise customers cannot match without weekend maintenance windows and staff overtime. Subscription pricing spreads costs evenly, an advantage for enterprises under pressure to align cash flow with revenue.
On-premise installs persist in defense, nuclear, and certain Chinese operations where data-sovereignty laws require in-country hosting. However, five-year total cost modeling shows cloud deployments 30-40% cheaper once hardware refresh cycles, database patching, and disaster-recovery drills are counted. IoT sensor expansion reinforces the trend: streaming vibration, gas, and air-quality data directly into cloud dashboards is easier than installing edge servers at every site.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud
- On-premise
- By Solution Type
- Incident and Safety Management
- Audit and Inspection
- Compliance and Risk Management
- ESG / Carbon Management
- Training and Learning
- By Organization Size
- Large Enterprises
- Small and Mid-Sized Enterprises (SMEs)
- By End-user Industry
- Energy and Utilities
- Oil and Gas
- Chemicals and Petro-chemicals
- Healthcare and Life Sciences
- Construction and Manufacturing
- Mining and Metals
- Food and Beverages
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Europe
- Germany
- France
- United Kingdom
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- South America
- Brazil
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America captured 37.46% of 2025 revenue, propelled by OSHA's escalating penalties and the SEC's climate-disclosure rule that effectively mandates continuous carbon accounting. High penetration among Fortune 500 firms intensifies competition for mid-market manufacturers and construction contractors still juggling clipboards and legacy databases. Vendor marketing increasingly highlights lower workers' compensation premiums achieved by predictive-risk dashboards, resonating with CFOs seeking immediate savings.
Europe follows closely, anchored by the Corporate Sustainability Reporting Directive, which obliges granular, digitized disclosures across 27 member states. ISO 45001 certification rates are highest in Germany, France, and the United Kingdom, reinforcing the regional appetite for platforms that harmonize audit workflows with sustainability metrics. Cloud uptake is tempered by GDPR requirements, yet sovereign-cloud offerings mitigate data-transfer anxieties, unlocking growth among chemical and aerospace firms.
Asia Pacific is the fastest-growing theater at 10.48% CAGR in the environmental health and safety (EHS) software market. China's revised Work Safety Law imposes criminal liability on executives after serious accidents, driving manufacturers to adopt real-time incident reporting and digital permit-to-work systems. India's formal ISO 45001 guidance and new digital injury-reporting portal align local plants with multinational audit expectations. South Korea's Serious Accidents Punishment Act, in force since 2022 but strictly enforced from 2024 onward, has catalyzed investments across shipbuilding and electronics supply chains.
The Middle East and Africa region gains momentum as national oil companies in Saudi Arabia and the United Arab Emirates embed EHS clauses into contractor agreements to satisfy Vision 2030 diversification goals. South Africa's mining sector, historically plagued by high fatality rates, is shifting to cloud dashboards that surface geotechnical risks in near real-time. South America shows uneven progress: Brazil leads after high-profile dam and offshore incidents spurred Petrobras and Vale to fund enterprise-wide roll-outs, whereas smaller Andean markets remain in earlier adoption phases.
- Enablon France SA (Wolters Kluwer NV)
- Intelex Technologies ULC
- VelocityEHS Holdings Inc.
- Cority Software Inc.
- Sphera Solutions Inc.
- Sai Global Pty Ltd. (Intertek Group PLC)
- Dakota Software Corporation
- Benchmark Digital Partners LLC
- Quentic GmbH
- Metrix Software Solutions (Pty) Ltd. (IsoMetrix)
- SAP SE
- iPoint-Systems GmbH
- Evotix Limited
- DNV Business Assurance Group AS
- EcoOnline Holding AS
- ETQ, LLC (part of Hexagon)
- Origami Risk LLC
- Alcumus Holdings Limited
- Ideagen PLC
- Vector Solutions.com, Inc.
- KPA Services, LLC
- StarTex Software LLC (DBA EHS Insight)
- Quber Technologies, Inc.
- SafetyCulture Pty Ltd.
- Enhesa NV/SA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Regulatory Enforcement and Rising Liability Exposure
- 4.2.2 Expansion of ESG and Sustainability Reporting Mandates
- 4.2.3 SaaS-first, Mobile-first EHS Platforms Reduce TCO
- 4.2.4 AI-driven Predictive Safety and Compliance Analytics
- 4.2.5 Convergence with Digital Twin and Asset Management Stacks
- 4.2.6 Corporate Insurance Linking Premiums to Real-time EHS Metrics
- 4.3 Market Restraints
- 4.3.1 High Upfront Implementation and Change-management Cost
- 4.3.2 Cyber-security and Data-privacy Concerns in Cloud Roll-outs
- 4.3.3 Shortage of Data-science Talent for Next-gen EHS Tools
- 4.3.4 Vendor Consolidation Creating Integration Lock-in Risk
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.3 By Solution Type
- 5.3.1 Incident and Safety Management
- 5.3.2 Audit and Inspection
- 5.3.3 Compliance and Risk Management
- 5.3.4 ESG / Carbon Management
- 5.3.5 Training and Learning
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Mid-Sized Enterprises (SMEs)
- 5.5 By End-user Industry
- 5.5.1 Energy and Utilities
- 5.5.2 Oil and Gas
- 5.5.3 Chemicals and Petro-chemicals
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Construction and Manufacturing
- 5.5.6 Mining and Metals
- 5.5.7 Food and Beverages
- 5.5.8 Other End-user Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Kenya
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Enablon France SA (Wolters Kluwer NV)
- 6.4.2 Intelex Technologies ULC
- 6.4.3 VelocityEHS Holdings Inc.
- 6.4.4 Cority Software Inc.
- 6.4.5 Sphera Solutions Inc.
- 6.4.6 Sai Global Pty Ltd. (Intertek Group PLC)
- 6.4.7 Dakota Software Corporation
- 6.4.8 Benchmark Digital Partners LLC
- 6.4.9 Quentic GmbH
- 6.4.10 Metrix Software Solutions (Pty) Ltd. (IsoMetrix)
- 6.4.11 SAP SE
- 6.4.12 iPoint-Systems GmbH
- 6.4.13 Evotix Limited
- 6.4.14 DNV Business Assurance Group AS
- 6.4.15 EcoOnline Holding AS
- 6.4.16 ETQ, LLC (part of Hexagon)
- 6.4.17 Origami Risk LLC
- 6.4.18 Alcumus Holdings Limited
- 6.4.19 Ideagen PLC
- 6.4.20 Vector Solutions.com, Inc.
- 6.4.21 KPA Services, LLC
- 6.4.22 StarTex Software LLC (DBA EHS Insight)
- 6.4.23 Quber Technologies, Inc.
- 6.4.24 SafetyCulture Pty Ltd.
- 6.4.25 Enhesa NV/SA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


