|
시장보고서
상품코드
2123022
3D 재구성 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)3D Reconstruction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
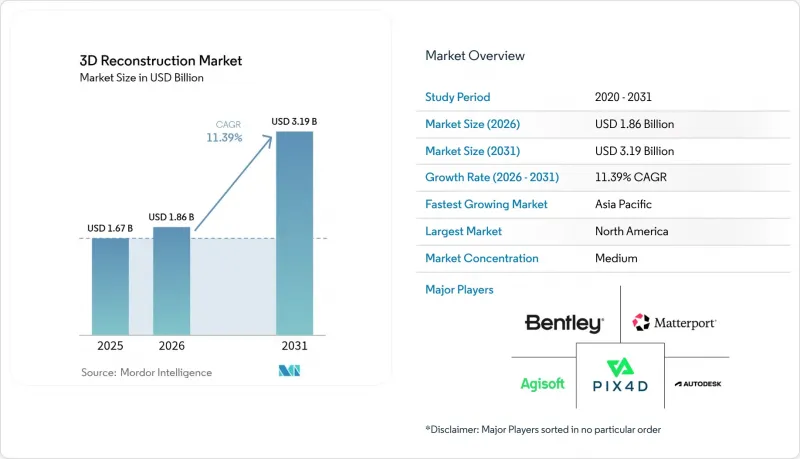
에 의하면, 2026년 3D 재구성 시장 규모는 18억 6,000만 달러로 추정되고, 2025년 16억 7,000만 달러에서 성장하여 2031년에는 31억 9,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 11.39%를 나타낼 전망입니다.
본 보고서는 구성 요소별(소프트웨어 및 서비스), 기술 유형별(능동형 3D 재구성 및 수동형 3D 재구성), 도입 모델별(온프레미스 및 클라우드), 용도별(건설 및 건축, 헬스케어 및 의료 영상, 문화유산·박물관, 산업 제조·검사 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 3D 재구성 시장 동향 및 인사이트
건설 분야의 BIM 주도형 디지털 트윈
3D 재구성은 현재 BIM 모델과 현장의 실태를 지속적으로 동기화하는 ‘상시 가동 피드백 루프’ 역할을 하고 있습니다. 영국의 ‘내셔널 디지털 트윈 프로그램’이나 싱가포르의 ‘버추얼 싱가포르’와 같은 이니셔티브에서는 공공 인프라 시공사에게 정기적인 스캔 데이터를 반영한 통합형 디지털 트윈의 제공을 의무화하고 있으며, 이로 인해 자동화된 포인트 클라우드 데이터 수집 및 메쉬 정렬에 대한 수요가 가속화되고 있습니다. 시공사에 따르면, 정확한 재구성을 통해 현장에서의 수정 작업이 줄어들고 인도까지의 시간이 단축되므로, 수명 주기 비용 최소화를 목표로 하는 발주자 사이에서 도입이 확대되고 있습니다. ISO 19650 확장 표준으로 대표되는 상호 운용성 기준의 개선으로 데이터 변환의 장벽이 낮아져 멀티 벤더 워크플로가 촉진되고 있습니다. 디지털 트윈 프로그램이 지자체 및 공공시설 자산으로 확대됨에 따라, 3D 재구성 시장은 설계 팀에서 시설 관리자 및 유지보수 계약업체로 그 범위를 넓혀가고 있습니다.
센서 및 LiDAR 비용 하락이 보급을 뒷받침
솔리드 스테이트 기술의 혁신과 대량 생산으로 인해 자동차용 LiDAR의 단가는 대당 500달러 미만으로 떨어졌으며, 이용 가능한 고객층이 1차 공급업체나 방위산업의 대기업을 넘어 확대되고 있습니다. 한때 5만 달러나 했던 핸드헬드형 SLAM 스캐너는 현재 3만 달러 미만으로 판매되고 있으며, 드론 탑재형 LiDAR 페이로드도 1만 달러 아래로 떨어지면서 유틸리티 협동조합이나 중규모 측량 회사에서도 복도 매핑이 가능해졌습니다. 하드웨어 비용의 하락으로 인해 남미, 아프리카, 남아시아에서는 새로운 서비스 제공업체들이 시장에 진입하고 있습니다. 이 지역에서는 지상 스캔이 경제적으로 타당하지 않아, 이전 프로젝트에서는 위성 이미지에 의존해 왔습니다. 그러나 기술 격차는 데이터 처리 분야로 옮겨가고 있으며, 각 벤더들은 포인트 클라우드 데이터를 자동으로 분류, 색상 지정, 간소화하는 클라우드 호스팅형 AI 툴세트를 제공함으로써 이에 대응하고 있으며, 이를 통해 지리공간 분야의 전문가가 아닌 사람들의 교육 주기를 단축하고 있습니다.
초기 하드웨어 및 소프트웨어 투자 비용의 높음
실용 수준의 지상 스캐너 가격은 여전히 4만-8만 달러 범위이며, 주요 사진측량 소프트웨어의 경우 사용자당 연간 4,000달러 이상의 라이선스 비용과 유지보수 비용이 듭니다. 클라우드 GPU 사용 시간도 이러한 비용을 더욱 부추기고 있습니다. 1만 장의 이미지로 구성된 조사의 고밀도 재구성을 위해서는 200-300 GPU 시간이 소요되며, 1,000달러의 처리 비용이 발생할 수 있습니다. 문화유산 관련 기관, 소규모 보험사, 지자체 도시계획국에게 이러한 자본 집약적인 비용은 기술 도입을 지연시키거나 외부 위탁을 고려하게 만드는 계기가 될 수 있습니다. 벤더 측의 대응 방안으로는 하드웨어-어즈-어-서비스(HaaS) 번들, 스캔당 과금, 단기 렌탈 등이 있지만, 이러한 대안들은 고객을 독자적인 생태계에 묶어두어 총비용을 절감하기보다는 단지 미루게 만드는 경우가 많습니다.
부문 분석
소프트웨어 분야에서는 영구 라이선스 및 구독 모델을 통해 2025년 매출의 68.52%를 차지했으며, 핵심인 사진측량 및 포인트 클라우드 플랫폼에서 수익을 창출하고 있습니다. 한편, 서비스 매출은 연평균 성장률(CAGR) 11.67%로 증가하고 있습니다. 이는 기업들이 사내 시스템 구축보다 턴키 방식의 결과물을 점점 더 선호하고 있기 때문입니다. 매니지드 서비스 기업들은 현장 데이터 수집, GPU 처리, 품질 보증(QA), 데이터 관리를 월정액 요금에 포함시켜, 자본 구매보다 프로젝트 예산에 더 적합한 형태로 서비스를 제공합니다. 미국 토목학회(ASCE)는 측량 정확도에 관한 제3자 검증 인증서를 요구하는 발주자의 비율이 증가하고 있어, 감사 및 자문 업무의 기회가 확대되고 있다고 지적하고 있습니다. 각 벤더사는 자사 전속 서비스 팀을 보유하며 제품 라인을 확충하고 있습니다. 오토데스크, 벤틀리 시스템즈, 트림블은 지역 밀착형 측량 전문 기업을 인수하여 실무 중심의 워크플로우 구축 및 규정 준수 관련 문서 작성 서비스를 제공합니다. 위치 정보의 정확도나 개인 데이터 마스킹에 관한 규제가 엄격해지는 가운데, 이 서비스는 앞으로도 3D 재구성 시장에서 가장 빠르게 성장하는 분야로 남을 것입니다.
서비스 수요를 높이는 두 번째 요인은 몇 가지 고부가가치 이용 사례가 간헐적으로 발생하는 데 있습니다. 보험사, 법 집행 기관, 긴급 대응 기관은 드문 사건이 발생한 후 현장을 신속하게 기록해야 하지만, 상시적인 팀이나 장비를 유지하는 것은 현실적으로 어렵습니다. 이미 촬영된 도시 트윈에 대한 구독형 접근, 주문형 현장 작업 팀, 그리고 스캔당 과금 방식의 로봇 기술을 통해 이러한 간헐적인 고객들의 진입 장벽이 낮아집니다. 예측 기간 동안, 건설 분야의 변화 감지 분석에서 공공 서비스 분야의 맞춤형 AI 분할 모델에 이르기까지, 전문 서비스 분야는 핵심 소프트웨어 매출을 능가하는 성장을 보이며 벤더의 매출 구성을 재편할 것으로 예측됩니다.
LiDAR, 구조화된 광, 비행 시간(ToF) 센서가 주류를 차지하는 능동형 이미징은 통제된 환경에서 타의 추종을 불허하는 서브 센티미터급 정밀도를 실현할 수 있어, 2025년 3D 재구성 시장에서 60.85%의 점유율을 차지했습니다. 산업용 계측, 공장 자동화, 자율주행차 분야에서는 여전히 능동형 센서가 필수로 간주됩니다. 그러나 신경 방사휘도장 및 가우스 스플래팅 기술을 통해 산재한 사진에서도 인쇄 가능한 수준의 정밀도를 얻을 수 있게 됨에 따라, 수동형 사진측량 기술은 연평균 성장률(CAGR) 11.75%로 성장하고 있습니다. 현재 ‘모바일 퍼스트’ 앱은 휴대 단말기로 촬영한 30-40장의 이미지를 수 분 이내에 텍스처가 적용된 메쉬로 변환하고 있으며, 이 기능을 통해 전자상거래, 주거용 부동산, 보험 분야의 활용 사례가 극히 적은 비용으로 실현 가능해졌습니다. 패시브 캡처의 비용 측면에서의 우위는 실외나 광범위한 프로젝트에서 특히 결정적이며, 특히 LiDAR 수입에 관세나 공급망 지연이 발생하는 신흥 시장에서 두드러집니다.
고밀도 LiDAR 포인트 클라우드와 사진 측량에 의한 텍스처를 융합하는 하이브리드 워크플로가 중간 단계로서 부상하고 있습니다. 문화유산 보존 복원가나 교량 검사관은 이러한 기법을 조합하여 단일 모델 내에서 mm 수준의 형상 정확도와 사진처럼 사실적인 표면 디테일을 구현하고 있습니다. 3D 재구성 시장 규모가 확대됨에 따라, 각 벤더들은 능동 및 수동 입력을 정렬하는 통합 툴킷을 제공하고 있으며, 이를 통해 작업자의 부담이 경감되고 있습니다. 구성 요소 비용도 점차 수렴되고 있습니다. LiDAR 가격이 500달러 아래로 떨어지면서 가격 격차가 줄어들고 있어, 프로젝트 관리자는 예산 제약뿐만 아니라 도입 환경을 바탕으로 기술 스택을 선택할 수 있게 되었습니다.
지역별 분석
북미는 조기 BIM 도입 의무화, 견고한 방위 산업 기반, 그리고 보험 청구를 3D로 광범위하게 기록하는 보험 부문의 지원에 힘입어 2025년 수요의 35.25%를 차지했습니다. ‘Every Day Counts’와 같은 미국 연방 프로그램에서는 LiDAR를 활용한 교량 점검이 추진되고 있는 반면, 캐나다의 광업 및 임업 기업에서는 환경 모니터링을 위해 드론이 도입되고 있습니다. 미국 각 주와 캐나다 각 주 간의 데이터 저장 장소에 관한 규정 차이는 국경을 넘는 프로젝트를 복잡하게 만들 수 있지만, 로컬 클라우드 리전의 활용을 통해 이 문제는 완화되고 있습니다. 멕시코에서는 철도 및 공항 현대화에 따라 회랑 매핑 프로젝트가 진행되고 있으나, 국내 전문 지식이 제한적이어서 현장 실행이 지연되고 있습니다.
유럽은 영국, 독일, 프랑스의 전국적인 BIM 요건 외에도 지중해 전역에 걸친 광범위한 문화유산 보존 활동을 통해 확고한 입지를 유지하고 있습니다. ‘호라이즌 유럽(Horizon Europe)’은 디지털 트윈 및 지리 공간 기술을 위한 연구 자금으로 1,073억 5,000만 달러를 배정하여 산학 컨소시엄의 활성화를 도모하고 있습니다. GDPR(EU 개인정보보호규정) 및 향후 시행될 AI법에 기반한 개인정보 보호 규제는 규정 준수 비용을 증가시키는 한편, 자동 마스킹, 데이터 축소 및 국내 처리 수요도 촉진하고 있습니다. 수입 제한에 직면한 러시아 건설 기업들은 국내 소프트웨어로 눈을 돌리고 있으며, 기능적인 격차는 있지만 현지 생태계의 성장을 뒷받침하고 있습니다.
아시아태평양은 가장 빠르게 성장하고 있으며, 연평균 성장률(CAGR)은 12.44%로 예측됩니다. 중국에서는 2억 위안 이상의 공공 프로젝트에 BIM 도입이 의무화되어 있어, 이는 대규모 스캔-투-BIM 워크플로우를 촉진하고 있습니다. 일본 국토교통성은 지진이 빈번한 지역의 터널과 교량 감시에 LiDAR 탑재 드론을 활용하여 공급망 보호와 공공 안전 확보를 도모하고 있습니다. 인도의 측량국(Survey of India)은 토지 등기 현대화와 재난 대응 계획 수립을 목적으로 도시의 3D 매핑을 추진하고 있습니다. 한국의 조선소나 반도체 공장에서는 서브mm 수준의 검사가 요구되고 있는 반면, 호주의 광업 부문에서는 채굴장 최적화를 위해 항공 LiDAR를 활용하고 있습니다. 인도네시아, 필리핀 및 태평양 제도 국가들에서는 광대역 환경의 격차와 사진 측량에 관한 교육 부족이 시장 확장의 걸림돌이 되고 있습니다.
중동 및 아프리카에서는 사우디아라비아의 ‘NEOM’이나 아랍에미리트의 ‘두바이 2040’과 같은 이니셔티브가 도시 규모의 디지털 트윈을 필요로 하고 있어 매출이 가속화되고 있습니다. 남아프리카의 심부 광산에서는 안전 확보를 위해 광산 내 작업 구역을 스캔하고 있으며, 이집트 관광부는 가상 관광을 위해 유물을 디지털화하고 있습니다. 사하라 이남의 일부 국가에서는 정세 불안과 환율 변동이 자본 조달을 저해하고 있어 시장 침투에 편차가 나타나고 있습니다. 그러나 걸프협력회의(GCC) 국가들의 성장은 메가 프로젝트에 대한 지출을 통해 지역 전체의 평균을 끌어올리고 있습니다.
남미에서는 브라질의 건설 부문이 회복세를 보이고, 아르헨티나가 리튬 채굴 사업을 확대함에 따라 다시 활기를 되찾고 있습니다. 브라질의 토지 개혁 프로그램에서는 토지 소유권을 명확히 하기 위해 드론을 이용한 측량이 가능해지면서, 클라우드 사진 측량에 대한 수요가 증가하고 있습니다. 칠레 유틸리티부는 팬아메리칸 고속도로의 산사태 구역 매핑에 LiDAR를 활용하고 있지만, 레이저 스캐너와 GPU에 대한 수입 관세로 인해 프로젝트 예산이 부풀어 오르고 있습니다. 메르코수르(Mercosur)의 디지털 인프라 실무그룹은 국경을 초월한 데이터 교환을 조화시키기 위한 공통 기술 기준을 마련 중이지만, 실제 도입은 여전히 점진적인 수준에 머물러 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, 3D reconstruction market size in 2026 is estimated at USD 1.86 billion, growing from 2025 value of USD 1.67 billion with 2031 projections showing USD 3.19 billion, growing at 11.39% CAGR over 2026-2031.
This report is Segmented by Component (Software and Services), Technology Type (Active 3D Reconstruction and Passive 3D Reconstruction), Deployment Model (On-Premise and Cloud), Application (Construction and Architecture, Healthcare and Medical Imaging, Cultural Heritage and Museum, Industrial Manufacturing and Inspection, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global 3D Reconstruction Market Trends and Insights
BIM-Driven Digital Twins in Construction
3D reconstruction is now an always-on feedback loop that keeps BIM models synchronized with on-site reality. Mandates such as the United Kingdom's National Digital Twin Programme and Singapore's Virtual Singapore require public infrastructure contractors to deliver federated digital twins that ingest periodic scans, accelerating demand for automated point cloud capture and mesh alignment. Contractors report that accurate reconstructions reduce field rework and compress handover times, thereby boosting adoption among owners seeking to minimize lifecycle costs. Improved interoperability standards, typified by ISO 19650 extensions, are reducing data conversion friction and encouraging multi-vendor workflows. As digital-twin programs extend to municipal and utility assets, the 3D reconstruction market is expanding from design teams to facilities managers and maintenance contractors.
Falling Sensor and LiDAR Costs Boosting Accessibility
Solid-state innovation and volume manufacturing have pulled LiDAR price points below USD 500 per automotive-grade unit, widening the accessible customer base beyond tier-one contractors and defense primes. Handheld SLAM scanners, which once cost USD 50,000, now list for under USD 30,000, and drone-mounted LiDAR payloads have dropped below USD 10,000, making corridor mapping accessible to utility cooperatives and mid-sized survey firms. Lower hardware cost is drawing new service entrants in South America, Africa, and South Asia, where earlier projects relied on satellite imagery because terrestrial scanning was uneconomical. The skills gap, however, has shifted to data processing; vendors are responding with cloud-hosted AI toolsets that automatically classify, colorize, and thin-point clouds, thereby shortening training cycles for non-geospatial professionals.
High Up-Front Hardware-Software Investment Outlay
A production-grade terrestrial scanner still ranges from USD 40,000 to USD 80,000, and leading photogrammetry software carries annual license and maintenance charges that can exceed USD 4,000 per seat. Cloud GPU time compounds these commitments: dense reconstruction of a 10,000-image survey can consume 200-300 GPU hours and incur USD 1,000 in processing fees. For cultural heritage bodies, small insurers, and municipal planning offices, capital intensity can slow adoption or prompt them to consider outsourcing. Vendor responses include hardware-as-a-service bundles, per-scan pricing, and short-term rentals; however, these alternatives often lock customers into proprietary ecosystems and defer, rather than eliminate, total costs.
Other drivers and restraints analyzed in the detailed report include:
- Explosive VR and AR Content Demand Across Media and Entertainment
- Drone-Based Data Capture Enabling Large-Area Mapping
- Workflow Complexity Requiring Specialist Skillsets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software captured 68.52% of 2025 revenue through perpetual-license and subscription models, monetizing core photogrammetry and point-cloud platforms. Services revenue, however, is rising at an 11.67% CAGR because enterprises increasingly favor turnkey deliverables over in-house buildouts. Managed-service firms bundle field capture, GPU processing, QA, and data management into monthly fees that better align with project budgets than capital purchases. The American Society of Civil Engineers notes that a rising share of owners demand third-party validation certificates for survey accuracy, expanding opportunity for audit and advisory engagements. Vendors are augmenting product lines with captive service teams. Autodesk, Bentley Systems, and Trimble have each acquired regional survey specialists to offer hands-on workflow configuration and compliance documentation. As regulatory oversight around geolocation precision and personal-data masking tightens, services will remain the fastest-growing component of the 3D reconstruction market.
A second factor elevating services is the episodic nature of several high-value use cases. Insurers, law enforcement units, and emergency response agencies require rapid scene capture after rare events but cannot justify maintaining permanent teams or equipment. Subscription access to pre-shot city twins, on-demand field crews, and pay-per-scan robotics lowers barriers for these intermittent customers. Over the forecast horizon, professional services lines, ranging from change-detection analytics in construction to bespoke AI segmentation models in utilities, are expected to outpace core software revenue and reshape the vendor revenue mix.
Active imaging, dominated by LiDAR, structured light, and time-of-flight sensors, held a 60.85% market share in 3D reconstruction in 2025, owing to its unmatched sub-centimeter fidelity in controlled conditions. Industrial metrology, factory automation, and autonomous vehicles still treat active sensors as mandatory. Yet passive photogrammetry is growing at an 11.75% CAGR as neural radiance fields and Gaussian splatting yield printable accuracy from sparse photographs. Mobile-first apps now transform 30-40 handheld images into textured meshes within minutes, a capability that unlocks ecommerce, residential real estate, and insurance use cases at negligible cost. The cost advantage of passive capture is particularly decisive for outdoor and large-area projects, especially in emerging markets where LiDAR imports face tariffs and supply chain delays.
Hybrid workflows that blend dense LiDAR point clouds with photogrammetric textures occupy a rising middle ground. Cultural heritage conservators and bridge inspectors combine modalities to achieve millimeter-level geometry and photorealistic surface detail in a single model. As the 3D reconstruction market size expands, vendors are shipping integrated toolkits that co-register active and passive inputs, reducing operator effort. Component costs are converging as well: as LiDAR falls below USD 500, price differentials shrink, allowing project managers to choose technology stacks based on the deployment environment rather than solely on budget constraints.
Complete Report Scope:
- By Component
- Software
- Services
- By Technology Type
- Active 3D Reconstruction
- Passive 3D Reconstruction
- By Deployment Model
- On-Premise
- Cloud
- By Application
- Construction and Architecture
- Healthcare and Medical Imaging
- Media and Entertainment
- Cultural Heritage and Museum
- Industrial Manufacturing and Inspection
- Public Safety and Forensics
- Robotics and Drones
- Education and Research
- Gaming and Virtual Reality
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 35.25% of 2025 demand, buoyed by early BIM mandates, a robust defense-industrial base, and an insurance sector that widely documents claims in 3D. U.S. federal programs, such as Every Day Counts, promote LiDAR bridge inspections, while Canadian mining and forestry firms deploy drones for environmental monitoring. Data-residency differences among U.S. states and Canadian provinces can complicate cross-border projects; however, local cloud regions help mitigate this issue. Mexico's rail and airport modernizations have led to corridor-mapping projects, although limited domestic expertise has slowed the field execution.
Europe maintains a strong position through nationwide BIM requirements in the United Kingdom, Germany, and France, as well as through extensive cultural heritage preservation across the Mediterranean. Horizon Europe allocated USD 107.35 billion in research funding toward digital twin and geospatial technologies, stimulating university-industry consortia. Privacy rules under GDPR and the forthcoming AI Act increase compliance costs but also drive demand for automated masking, redaction, and on-shore processing. Russian construction firms, facing import constraints, have turned to domestic software, which has encouraged the growth of the local ecosystem despite capability gaps.
The Asia-Pacific region is the fastest-growing, with a projected 12.44% CAGR. China's mandate that public projects above CNY 200 million deploy BIM is feeding large-scale scan-to-BIM workflows. Japan's transport ministry utilizes LiDAR-equipped drones to monitor tunnels and bridges in seismic zones, thereby protecting supply chains and ensuring public safety. India's Survey of India is mapping cities in 3D to modernize land records and disaster-response planning. South Korea's shipyards and fabs require sub-millimeter inspection, while Australia's mining sector leverages aerial LiDAR for pit optimization. Broadband gaps and limited photogrammetry training restrict expansion in Indonesia, the Philippines, and Pacific Island states.
Middle East and Africa sales accelerate as Saudi Arabia's NEOM and the United Arab Emirates' Dubai 2040 initiatives demand city-scale digital twins. South Africa's deep mines scan underground workings for safety, and Egypt's Ministry of Tourism digitizes antiquities for virtual tourism. Political instability and currency volatility hinder capital acquisitions in several sub-Saharan countries, resulting in uneven market penetration. Gulf Cooperation Council growth, however, drags regional averages upward through mega-project spending.
South America experiences renewed momentum as Brazil's construction sector rebounds, and Argentina expands its lithium mining operations. Brazilian land-reform programs now mandate drone surveys for land-tenure clarification, spurring demand for cloud photogrammetry. Chile's public-works ministry relies on LiDAR to map landslide zones on the Pan-American Highway, but import tariffs on laser scanners and GPUs inflate project budgets. A Mercosur digital infrastructure working group is drafting shared technical standards to harmonize cross-border data exchange; yet, tangible adoption remains incremental.
- Autodesk Inc.
- Pix4D SA
- Agisoft LLC
- Bentley Systems Incorporated
- Capturing Reality s.r.o.
- Matterport Inc.
- Paracosm Inc.
- PhotoModeler Technologies
- Trimble Inc.
- Hexagon AB
- FARO Technologies Inc.
- Siemens AG
- Dassault Systemes SE
- 3Dflow SRL
- Skyline Software Systems Inc.
- NavVis GmbH
- GeoSLAM Ltd.
- DroneDeploy Inc.
- SimActive Inc.
- Artec Europe S.a r.l. (Artec 3D)
- SZ DJI Technology Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption of BIM-Driven Digital Twins in Construction
- 4.2.2 Falling Sensor and LiDAR Costs Boosting Accessibility
- 4.2.3 Explosive VR- and AR-Content Demand Across Media and Entertainment
- 4.2.4 Drone-Based Data Capture Enabling Large-Area Mapping
- 4.2.5 Insurance Sector Shift to 3D Scene Documentation for Rapid Claims
- 4.2.6 Patient-Specific Surgical Planning Platforms Gaining Traction
- 4.3 Market Restraints
- 4.3.1 High Up-Front Hardware-Software Investment Outlay
- 4.3.2 Workflow Complexity Requiring Specialist Skillsets
- 4.3.3 Urban-Capture Privacy and Data-Sovereignty Regulations
- 4.3.4 Cloud Processing's Rising Carbon-Footprint Scrutiny
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Degree of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Technology Type
- 5.2.1 Active 3D Reconstruction
- 5.2.2 Passive 3D Reconstruction
- 5.3 By Deployment Model
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.4 By Application
- 5.4.1 Construction and Architecture
- 5.4.2 Healthcare and Medical Imaging
- 5.4.3 Media and Entertainment
- 5.4.4 Cultural Heritage and Museum
- 5.4.5 Industrial Manufacturing and Inspection
- 5.4.6 Public Safety and Forensics
- 5.4.7 Robotics and Drones
- 5.4.8 Education and Research
- 5.4.9 Gaming and Virtual Reality
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Autodesk Inc.
- 6.4.2 Pix4D SA
- 6.4.3 Agisoft LLC
- 6.4.4 Bentley Systems Incorporated
- 6.4.5 Capturing Reality s.r.o.
- 6.4.6 Matterport Inc.
- 6.4.7 Paracosm Inc.
- 6.4.8 PhotoModeler Technologies
- 6.4.9 Trimble Inc.
- 6.4.10 Hexagon AB
- 6.4.11 FARO Technologies Inc.
- 6.4.12 Siemens AG
- 6.4.13 Dassault Systemes SE
- 6.4.14 3Dflow SRL
- 6.4.15 Skyline Software Systems Inc.
- 6.4.16 NavVis GmbH
- 6.4.17 GeoSLAM Ltd.
- 6.4.18 DroneDeploy Inc.
- 6.4.19 SimActive Inc.
- 6.4.20 Artec Europe S.a r.l. (Artec 3D)
- 6.4.21 SZ DJI Technology Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment