

|
시장보고서
상품코드
2123059
압력 트랜스미터 및 트랜스듀서 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pressure Transmitter And Transducer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
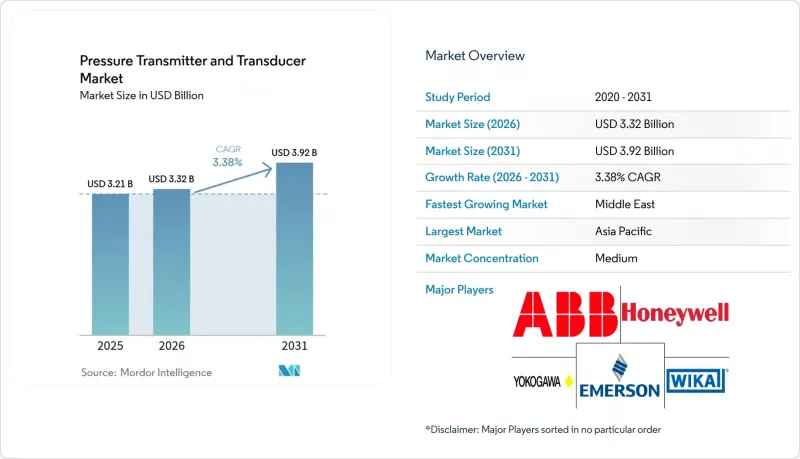
에 의하면, 2026년 압력 트랜스미터 및 트랜스듀서 시장 규모는 33억 2,000만 달러로 추정되고 있어 2025년 32억 1,000만 달러에서 확대해, 2031년에는 39억 2,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 3.38%가 될 것으로 전망됩니다.
본 보고서는 제품 유형(압력 트랜스미터 및 압력 트랜스듀서), 감지 기술(피에조 저항식, 정전용량식 등), 압력 범위(저압(100 Psi 미만/7 Bar 미만) 등),출력/통신 방식(아날로그, 디지털 등), 최종 사용자 산업(석유 및 가스, 화학제품 및 석유화학제품 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 압력 트랜스미터 및 트랜스듀서 시장 동향 및 인사이트
업스트림 수소 및 CCUS 프로젝트가 SIL-3 인증 트랜스미터 수요를 견인
유럽 및 북미의 신규 수소 및 탄소 포집 시설에서는 더욱 엄격한 위험 허용 기준을 충족하기 위해 SIL-3 준수 차압 트랜스미터가 지정되고 있습니다. VEGAPULS 6X 레이더 센서와 같은 장치는 IEC 61508 및 IEC 61511 준수는 물론 사이버 보안 인증도 획득하여, 예측 진단을 원하는 사업자의 요구를 충족시키고 있습니다. 수소 전해조의 규모가 확대됨에 따라 플랜트 소유주들은 드리프트를 조기에 감지하여 가동 중지 시간을 최소화하는 계측기에 내장된 자가 진단 루틴을 높이 평가했습니다. 이러한 수요로 인해 프리미엄 가격이 상승하여 표준 제품군에 영향을 미치는 상품화로부터 공급업체를 보호하는 동시에, 압력 트랜스미터 및 트랜스듀서 시장이 통합형 안전 솔루션으로 전환되는 추세를 뒷받침하고 있습니다.
중동 정유시설의 디지털 전환 가속화
IEC 61511에 따른 의무적인 업그레이드로 인해, 걸프 지역 정유시설에서는 수천 개의 아날로그 그룹이 스마트 트랜스미터로 전환되고 있습니다. Baker Hughes는 고압 어셈블리의 현지 생산 및 리드타임 단축을 목표로 2024년에 아부다비에 4만 6,000제곱미터 규모의 압력 제어 센터를 개설했습니다. 디지털 장비는 원격 설정 및 고급 진단을 가능하게 하여, 운영자가 유지보수를 위해 출장하는 횟수를 줄이고 인력 현지화 목표를 달성할 수 있도록 지원합니다. 이러한 프로젝트들은 무선 기술의 도입을 촉진하고, 압력 트랜스미터 및 트랜스듀서 시장을 이 지역의 다운스트림 현대화 프로그램의 초석으로 확고히 다지고 있습니다.
고진동 환경에서 MEMS 칩의 고장이 보급을 저해하고 있습니다.
시추공 내 도구는 섬세한 MEMS 구조를 손상시킬 수준의 진동에 노출되기 때문에 운영사는 열과 충격에 내성이 있는 광섬유 대체품을 모색하고 있습니다. 현재 분산형 광섬유 시스템을 통해 유정 전체에 걸쳐 압력이 지속적으로 모니터링되고 있습니다. 내구성이 강화된 MEMS 변형이 성숙 단계에 도달할 때까지는 도입이 제한적일 것이며, 이로 인해 압력 트랜스미터 및 트랜스듀서 시장의 일부가 제한될 것입니다.
부문 분석
2025년, 차압 트랜스미터는 압력 트랜스미터 및 트랜스듀서 시장에서 33.65%의 점유율을 유지하며, 기존의 유량 측정 용도에서 그 입지를 공고히 했습니다. 대조적으로, 멀티바리어블 모델은 압력, 온도, 밀도를 하나의 패키지로 제공하는 싱글 플랜지 설치를 고객이 선호함에 따라 연평균 성장률(CAGR) 5.55%를 나타낼 것으로 예측됩니다. Systec Controls가 인증을 받은 Ex 존 대응 멀티바리어블 제품의 출시는 이러한 통합화 추세를 뒷받침하고 있습니다.
디지털화의 진전에 따라 임펄스 라인의 막힘을 감지하는 온보드 진단 기능이 추진되고 있으며, 펌웨어 업데이트를 통해 원격 재교정이 가능해졌습니다. 이러한 기능들은 장기 서비스 계약의 기반이 되어 공급업체의 수익원을 확대하는 동시에, 압력 트랜스미터 및 트랜스듀서 시장을 솔루션 중심의 기반으로 끌어올리고 있습니다. 게이지 압력 및 절대 압력 제품은 일반적인 유틸리티 및 진공 공정에서 여전히 주류를 이루고 있지만, 그 성장률은 둔화되고 있습니다.
피에조 저항형 칩은 저렴한 비용과 견고한 온도 보정 기능 덕분에 2025년 매출의 47.40%를 차지했습니다. 반면, 광학식 솔루션은 전자기 간섭의 영향을 받지 않고 가혹한 환경에도 적합하기 때문에 연평균 성장률(CAGR) 6.88%로 확대되고 있습니다. NETL의 레이저 성장형 광섬유 프로브는 극한의 열을 견디며 장기간에 걸쳐 선형성을 유지합니다.
저압 감도와 고압 내성을 모두 갖춘 하이브리드 MEMS-광학 어셈블리가 등장하고 있습니다. 온보드 포토닉스의 가격이 하락함에 따라, 압력 트랜스미터 및 트랜스듀서 시장은 특히 EMI 내성이 요구되는 원자력 발전 및 고주파 RF 시험 장비 분야에서 점차 하이엔드화될 것입니다.
지역별 분석
아시아태평양은 적극적인 반도체 생산 능력 확대에 힘입어 2025년에는 전 세계 매출의 37.50%를 차지했습니다. 각 주조 업체, 특히 대만과 한국에서는 초고청정 및 스테인리스 프리 어셈블리를 지정하고 있어, 압력 트랜스미터 및 트랜스듀서 시장에서 이 지역의 주도적 위치를 공고히 하고 있습니다. 중국의 고정밀 제조로의 전환에 따라 자동차 및 화학 플랜트용 중급 센서에 대한 수요는 견조한 추세를 보이고 있습니다. 일본은 항공우주 및 로봇 공학 등급의 계측 기기에서 프리미엄 틈새 시장을 유지하고 있는 반면, 인도의 백신 제조 공장에서는 클린룸용 센서의 도입이 확대되고 있습니다.
중동은 2031년까지 연평균 성장률(CAGR) 5.47%로 성장을 주도할 것입니다. 사우디아라비아의 ‘비전 2030’은 화학제품 및 수소의 다각화를 추진하고 있어, SIL-3 인증을 획득한 트랜스미터에 대한 수요를 높이고 있습니다. SABIC의 2024년 매출 373억 달러는 정밀한 압력 제어에 의존하는 저탄소 제품 개발에 자금을 지원하고 있습니다. UAE의 현지화 추진의 좋은 사례로 베이커 휴즈(Baker Hughes)의 아부다비 신규 시설을 들 수 있습니다. 이 시설은 리드타임을 단축하고 공급망의 회복력을 높이고 있습니다.
북미는 계속해서 기술적으로 선진적이며, 셰일 사업자들은 실시간 유정 진단을 위해 무선 트랜스미터를 채택하고 있습니다. 탄소 저장에 대한 연방 정부의 인센티브로 인해, 고신뢰성 장치에 대한 특수한 수요가 발생하고 있습니다. 유럽에서는 에너지 효율 향상을 위한 개조 및 선진적인 안전 기준이 중시되고 있으며, 수소 클러스터를 위한 스마트하고 자체 검증 기능을 갖춘 트랜스미터의 구매가 촉진되고 있습니다. 남미에서는 브라질과 가이아나의 심해 개발 프로젝트에서 초고압 장치가 필수로 요구되는 반면, 칠레와 페루 전역의 광업 프로젝트에서는 견고한 설계가 요구되고 있습니다. 이러한 다양한 지역적 요인들이 결합되어 전 세계 압력 트랜스미터 및 트랜스듀서 시장의 균형 잡힌 성장을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, pressure transmitter and transducer market size in 2026 is estimated at USD 3.32 billion, growing from 2025 value of USD 3.21 billion with 2031 projections showing USD 3.92 billion, growing at 3.38% CAGR over 2026-2031.
This report is Segmented by Product Type (Pressure Transmitters and Pressure Transducers), Sensing Technology (Piezoresistive, Capacitive, and More), Pressure Range (Low (<100 Psi / <7 Bar), and More), Output/Communication (Analog, Digital, and More), End-User Industry (Oil and Gas, Chemical and Petrochemical, and More), Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Pressure Transmitter And Transducer Market Trends and Insights
Upstream Hydrogen and CCUS Projects Driving SIL-3 Certified Transmitters
New hydrogen and carbon-capture facilities in Europe and North America are specifying SIL-3 differential transmitters to meet tighter risk tolerances. Devices such as the VEGAPULS 6X radar sensor provide IEC 61508 and IEC 61511 compliance plus cybersecurity certification, aligning with operators' push for predictive diagnostics. As hydrogen electrolyzers scale, plant owners value the instruments' built-in self-check routines that flag drift early, limiting downtime. This demand lifts premium pricing, cushioning vendors from the commoditization affecting standard ranges, and reinforces the pressure transmitter and transducer market's pivot toward integrated safety solutions.
Middle-East Refinery Mandates Accelerating Digital Transformation
Mandated upgrades under IEC 61511 are converting thousands of analog loops to smart transmitters across Gulf refineries. Baker Hughes' 46,000 sqm pressure-control center opened in Abu Dhabi in 2024 to localize high-pressure assemblies and shorten lead times. Digital devices enable remote configuration and advanced diagnostics, helping operators cut maintenance trips and align with workforce-nationalization goals. These projects reinforce wireless adoption and cement the pressure transmitter & transducer market as a cornerstone of the region's downstream modernization programs.
MEMS-Chip Failures Limiting Adoption in High-Vibration Environments
Down-hole tools encounter vibration levels that fracture delicate MEMS structures, prompting operators to seek fiber-optic alternatives that tolerate heat and shock. Distributed fiber systems now monitor pressure continuously along entire wellbores. Until ruggedized MEMS variants mature, adoption remains capped, limiting part of the pressure transmitter and transducer market.
Other drivers and restraints analyzed in the detailed report include:
- Deep-Water Exploration Pushing Ultra-High Pressure Technology
- Semiconductor Fabs Requiring Ultra-Clean Pressure Solutions
- Price Erosion Squeezing Margins in Standard Pressure Ranges
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Differential transmitters retained a 33.65% slice of the pressure transmitter and transducer market in 2025, cementing their role in traditional flow applications. Multivariable models, by contrast, are forecast to climb at 5.55% CAGR as customers favor single-flange installations that deliver pressure, temperature, and density in one package. The Systec Controls certified Ex-zone multivariable launch underscores this tilt toward integration.
Growing digitalization is driving on-board diagnostics that flag impulse-line clogging, while firmware updates provide remote recalibration. These capabilities anchor long-term service contracts, enlarging vendor revenue streams and elevating the pressure transmitter and transducer market to a solution-centric footing. Gauge and absolute variants remain staples for general utilities and vacuum processes, but absorb slower growth.
Piezoresistive chips delivered 47.40% of 2025 revenue owing to low cost and robust temperature compensation. Optical solutions, however, are expanding at a 6.88% CAGR, immune to electromagnetic interference and ideal for harsh zones. NETL's laser-grown optical fiber probes endure extreme heat with extended linearity.
Hybrid MEMS-optical assemblies are emerging to capture both low-pressure sensitivity and high-pressure resilience. As on-board photonics prices fall, the pressure transmitter and transducer market will gradually migrate upscale, particularly in nuclear power and high-frequency RF test stands that demand EMI immunity.
Complete Report Scope:
- By Product Type
- Pressure Transmitters
- Differential Pressure
- Absolute Pressure
- Gauge Pressure
- Multivariable Pressure
- Pressure Transducers
- Strain-Gauge Transducers
- Piezoresistive Transducers
- Capacitive Transducers
- Optical Transducers
- Pressure Transmitters
- By Sensing Technology
- Piezoresistive
- Capacitive
- Strain Gauge
- Piezoelectric
- Optical
- MEMS Hybrid
- By Pressure Range
- Low (<100 psi / <7 bar)
- Medium (100-1000 psi)
- High (1 000-10 000 psi)
- Ultra-High (>10 000 psi)
- By Output / Communication
- Analog (4-20 mA, 0-10 V)
- Digital (HART, Fieldbus, Profibus, Modbus)
- Wireless (WirelessHART, ISA100)
- IO-Link
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Power Generation and Utilities
- Water and Wastewater
- Food and Beverage
- Pharmaceuticals and Biotechnology
- Medical Devices and Healthcare
- Aerospace and Defense
- Semiconductor and Electronics
- Mining, Metals and Marine
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries (Sweden, Norway, Denmark)
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Southeast Asia (Indonesia, Malaysia, Thailand, Vietnam)
- Australia
- New Zealand
- South America
- Brazil
- Argentina
- Chile
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Turkey
- Africa
- South Africa
- Nigeria
- Egypt
- North America
Geography Analysis
Asia-Pacific generated 37.50% of global revenue in 2025, anchored by aggressive semiconductor capacity expansion. Foundries specify ultra-clean stainless-free assemblies, particularly in Taiwan and South Korea, reinforcing regional leadership within the pressure transmitter & transducer market. China's shift toward higher-precision manufacturing keeps demand brisk for mid-range sensors in automotive and chemical plants. Japan sustains a premium niche for aerospace and robotics-grade instruments, while India's vaccine plants boost cleanroom sensor uptake.
The Middle East leads growth at a 5.47% CAGR through 2031. Saudi Arabia's Vision 2030 diversifies chemicals and hydrogen, elevating need for SIL-3 certified transmitters. SABIC's USD 37.3 billion sales in 2024 fund low-carbon product rollouts reliant on advanced pressure control. The UAE's localization drive is exemplified by Baker Hughes' new Abu Dhabi facility, which trims lead times and heightens supply-chain resilience.
North America remains technologically forward, with shale operators adopting wireless transmitters for real-time well diagnostics. Federal incentives for carbon storage add specialized demand for high-integrity devices. Europe favors energy-efficiency retrofits and progressive safety norms, spurring purchases of smart, self-verifying transmitters for hydrogen clusters. South America's deep-water campaigns in Brazil and Guyana mandate ultra-high pressure units, while mining projects across Chile and Peru secure rugged designs. Collectively, varied regional drivers sustain the pressure transmitter and transducer market's balanced global footprint.
- Emerson Electric Co.
- ABB Ltd
- Yokogawa Electric Corporation
- Honeywell International Inc.
- Siemens AG
- Endress+Hauser AG
- Schneider Electric SE
- Danfoss A/S
- TE Connectivity Ltd.
- Sensata Technologies Inc.
- WIKA Alexander Wiegand SE and Co. KG
- Dwyer Instruments LLC
- Spectris plc (Omega, HBM)
- Ashcroft Inc.
- Keller AG fur Druckmesstechnik
- Brooks Instrument LLC
- Gems Sensors and Controls (Fortive)
- Viatran (IDEX Corp.)
- OleumTech Corporation
- AMETEK Inc. (Crystal)
- NXP Semiconductors N.V.
- Mensor (WIKA Group)
- Zemic Group
- Micro Sensor Co., Ltd.
- Huba Control AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Upstream Hydrogen and CCUS Projects in EU/NA Demanding SIL-3 Differential Transmitters
- 4.2.2 Middle-East Refinery Mandates for Smart Instrumentation (IEC 61511) Fueling Digital Adoption
- 4.2.3 Deep-water Investments in Brazil and Guyana Requiring >20 kpsi Sub-sea Transducers
- 4.2.4 APAC Semiconductor Fabs Need for Ultra-Clean Sub-1 Torr Transducers
- 4.3 Market Restraints
- 4.3.1 MEMS-Chip Failures under High Vibration Down-hole Environments
- 4.3.2 Price Erosion in 0-10 bar OEM Transducers from Low-Cost Asian Suppliers
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook (Smart, Wireless, IIoT Integration)
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Pressure Transmitters
- 5.1.1.1 Differential Pressure
- 5.1.1.2 Absolute Pressure
- 5.1.1.3 Gauge Pressure
- 5.1.1.4 Multivariable Pressure
- 5.1.2 Pressure Transducers
- 5.1.2.1 Strain-Gauge Transducers
- 5.1.2.2 Piezoresistive Transducers
- 5.1.2.3 Capacitive Transducers
- 5.1.2.4 Optical Transducers
- 5.1.1 Pressure Transmitters
- 5.2 By Sensing Technology
- 5.2.1 Piezoresistive
- 5.2.2 Capacitive
- 5.2.3 Strain Gauge
- 5.2.4 Piezoelectric
- 5.2.5 Optical
- 5.2.6 MEMS Hybrid
- 5.3 By Pressure Range
- 5.3.1 Low (<100 psi / <7 bar)
- 5.3.2 Medium (100-1000 psi)
- 5.3.3 High (1 000-10 000 psi)
- 5.3.4 Ultra-High (>10 000 psi)
- 5.4 By Output / Communication
- 5.4.1 Analog (4-20 mA, 0-10 V)
- 5.4.2 Digital (HART, Fieldbus, Profibus, Modbus)
- 5.4.3 Wireless (WirelessHART, ISA100)
- 5.4.4 IO-Link
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Chemical and Petrochemical
- 5.5.3 Power Generation and Utilities
- 5.5.4 Water and Wastewater
- 5.5.5 Food and Beverage
- 5.5.6 Pharmaceuticals and Biotechnology
- 5.5.7 Medical Devices and Healthcare
- 5.5.8 Aerospace and Defense
- 5.5.9 Semiconductor and Electronics
- 5.5.10 Mining, Metals and Marine
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Nordic Countries (Sweden, Norway, Denmark)
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Taiwan
- 5.6.3.6 Southeast Asia (Indonesia, Malaysia, Thailand, Vietnam)
- 5.6.3.7 Australia
- 5.6.3.8 New Zealand
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Chile
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Qatar
- 5.6.5.4 Turkey
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Egypt
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, JV, Partnerships)
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)}
- 6.4.1 Emerson Electric Co.
- 6.4.2 ABB Ltd
- 6.4.3 Yokogawa Electric Corporation
- 6.4.4 Honeywell International Inc.
- 6.4.5 Siemens AG
- 6.4.6 Endress+Hauser AG
- 6.4.7 Schneider Electric SE
- 6.4.8 Danfoss A/S
- 6.4.9 TE Connectivity Ltd.
- 6.4.10 Sensata Technologies Inc.
- 6.4.11 WIKA Alexander Wiegand SE and Co. KG
- 6.4.12 Dwyer Instruments LLC
- 6.4.13 Spectris plc (Omega, HBM)
- 6.4.14 Ashcroft Inc.
- 6.4.15 Keller AG fur Druckmesstechnik
- 6.4.16 Brooks Instrument LLC
- 6.4.17 Gems Sensors and Controls (Fortive)
- 6.4.18 Viatran (IDEX Corp.)
- 6.4.19 OleumTech Corporation
- 6.4.20 AMETEK Inc. (Crystal)
- 6.4.21 NXP Semiconductors N.V.
- 6.4.22 Mensor (WIKA Group)
- 6.4.23 Zemic Group
- 6.4.24 Micro Sensor Co., Ltd.
- 6.4.25 Huba Control AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


