

|
시장보고서
상품코드
2123072
스마트 스페이스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Smart Spaces - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
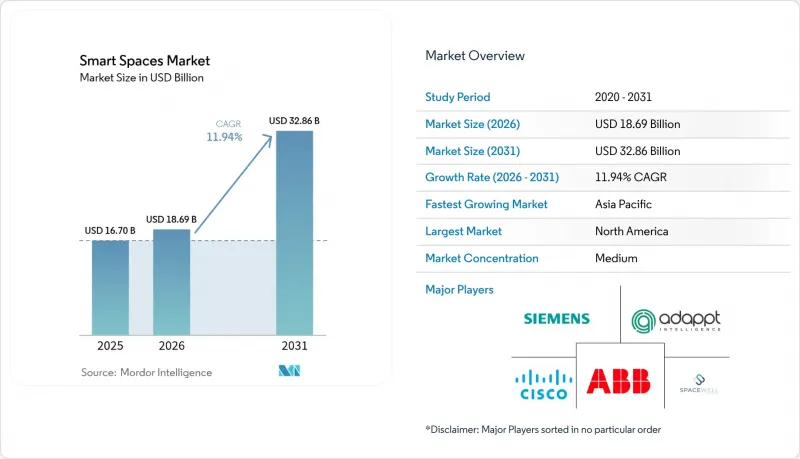
에 의하면, 스마트 스페이스 시장 규모는 2025년 167억 달러로 평가되었고, 2026년에는 186억 9,000만 달러로 추정되고, 2026-2031년 CAGR 11.94%로 성장을 지속할 전망이며, 2031년에는 328억 6,000만 달러에 이를 것으로 예측됩니다.
(1) Thread Group, “Thread 1.4 제품 인증 건수 6억 7,000만 건 돌파”, threadgroup.org 이러한 상승 추세는 대규모 도입을 용이하게 하는 IoT 센서 가격 하락, 디지털 전환을 가속화하는 넷제로 건축 기준의 의무화, 그리고 실시간 공간 최적화를 촉진하는 하이브리드 근무 정책에 의해 형성되고 있습니다. 본 보고서는 유형별(솔루션 및 서비스), 최종 사용자 산업별(상업용 및 주거용), 용도별(에너지 관리, 재실 현황 및 공간 분석, 조명 및 HVAC 제어 등), 연결 기술별(Wi-Fi, Zigbee, Z-Wave 등), 그리고 지역별로 분류되어 있습니다.
세계의 스마트 스페이스 시장 동향 및 인사이트
IoT 지원 기기의 보급 및 센서 가격 하락
반도체 공급 과잉으로 인해 2023년 이후 센서의 평균 판매 가격은 두 자릿수 비율로 하락했으며, 이에 따라 건물 소유주는 재실 상황, 공기질, 전력계 노드를 건물 전체에 설치하여 상세한 데이터를 클라우드 분석으로 전송할 수 있게 되었습니다. 2025년 초까지 670대 이상의 Thread 인증 기기가 출하되었으며, 이는 각 벤더들이 현재 멀티 벤더 간의 상호 운용성을 필수 조건으로 간주하고 있음을 분명히 보여줍니다. Milesight 본사에 352개의 센서를 도입하여 연간 유틸리티 비용을 4만 5,000달러 절감한 사례는 시설 관리자들 사이에서 널리 화제가 되고 있습니다. 엣지 AI 칩의 메모리 대역폭 확대로 지연 시간의 부정적인 영향이 해소되어 실시간 제어 루프가 지원되게 되었지만, 기존 시설에의 통합은 여전히 기존의 배선 및 제어 시스템에 따라 상황이 다릅니다. 자본 비용이 감소하는 가운데, 의사 결정은 하드웨어의 가격 경쟁력보다 에너지 절감 실적이 더 큰 영향을 미치게 되었으며, 이러한 전환으로 인해 스마트 스페이스 시장은 수요 주도형 사이클을 유지하고 있습니다.
하이브리드 근무에 대응한 사무실 재설계가 가속화
하이브리드 근무 체제의 도입으로 평일 인원 수가 변동함에 따라, 기존의 시간대별 HVAC 프로그래밍은 시대에 뒤떨어진 방식이 되었습니다. 존슨 컨트롤즈(Johnson Controls)는 과거 평균값이 아닌 실제 재실 상황에 따라 기류와 조명을 조정하는 적응형 제어 시스템의 수주가 2025년 1분기에 16% 증가했습니다. 워싱턴 D.C.의 한 오피스 빌딩에서는 고정 설정값을 멀티 센서를 통한 재실 데이터로 대체하고, 칠러에 수요 곡선에 따른 운전을 지시한 결과 33%의 에너지 절감을 실현했습니다. AI를 활용한 환기 모델을 통해 CO₂ 농도를 1,000 ppm 미만으로 유지하면서 환기 에너지를 12.5% 절감해, 직원 건강 증진 목표와 수익 목표를 동시에 달성하고 있습니다. 상업용 부동산 소유주들 사이에서는 실제 이용 현황에 따라 유연하게 조정되는 ‘동적 임대료’ 도입이 시도되고 있으며, 데이터 생성을 수익원으로 전환하고 있습니다. 다만, 실시간 분석을 수행하기 위해서는 GDPR(EU 개인정보보호규정) 및 CCPA에 따라 임차인의 개인정보를 보호하기 위해 사이버 보안 대책이 마련된 네트워크와 안전한 데이터 레이크가 필요합니다.
기존 건물의 고액 초기 개보수 비용
오래된 건물에는 오픈 프로토콜을 통한 오버레이가 어려운 독자적인 HVAC 및 조명 시스템이 채택되어 있는 경우가 많습니다. QuadReal사는 이종 서브시스템을 통합하기 위해 3,000만 제곱피트에 달하는 패시브 광 백본이 필요했으나, 이 자본 프로젝트는 운영 비용의 50-70% 절감이 예상되어야 비로소 정당화될 수 있었습니다. Limbach사가 여러 세대의 HVAC 시스템이 혼재된 20곳의 시설을 디지털화한 결과, 데이터의 세분화 수준에 일관성이 없어 분석이 복잡해지는 것으로 드러났습니다. PHOENIX와 같은 파일럿 프로그램에서는 39-61%라는 놀라운 효율 향상이 실현되었지만, 텔레메트리 데이터를 표준화하기 위해 맞춤형 미들웨어가 필요했습니다. 에너지 서비스 기업(ESCO)을 통한 자금 조달이나 성과 연동형 리스를 활용하면 초기 투자를 서비스 요금으로 전환하는 것이 가능하지만, 이해관계자들이 하나의 프로젝트 헌장 하에서 기계, 전기, IT 업그레이드를 조율해야 하는 경우 의사 결정 주기는 여전히 길어질 수밖에 없습니다.
부문 분석
솔루션 분야는 2025년 매출의 67.35%라는 최대 점유율을 차지했으며, 스마트 스페이스 시장 규모 112억 5,000만 달러에 해당합니다. 하드웨어 장비와 모니터링 소프트웨어가 디지털 기반을 형성하고 있지만, 최종 사용자는 최적화 업무를 제3자에게 위탁하는 경향이 강해지고 있습니다. 서비스 분야는 연평균 성장률(CAGR) 13.61%를 기록할 전망이며, 이는 지속적인 시운전, 원격 진단, AI를 활용한 의사결정 지원에 대한 수요 증가를 반영합니다. BrainBox AI는 2024년 3월, 생성형 빌딩 어시스턴트를 출시하여 에너지 이상에 대한 대화형 문의 및 처방적 조정이 가능하도록 했습니다. Trane Technologies는 이 기능을 신속하게 애프터마켓 포트폴리오에 통합하여, 두 자릿수 유틸리티 비용 절감을 보장하는 성과 기반 계약에 자율형 HVAC 제어를 포함시켰습니다. 관리형 서비스 공급업체는 칠러를 좁은 설정값 범위 내로 유지하는 알고리즘에 데이터를 제공함으로써 시간 단위 원격 측정 데이터를 통해 수익을 창출하고 있으며, 이를 통해 마모를 줄이고 탄소 배출량도 억제하고 있습니다. 인력 부족으로 사내 시설 관리 팀의 활동이 제약을 받는 가운데, 경영진은 외부 전문 지식을 성능 저하 위험에 대한 보험으로 간주하고 있습니다.
장기적으로는 장치의 펌웨어, 분석 모델, 보안 패치가 지속적으로 업데이트됨에 따라 하이브리드 클라우드 아키텍처로 인해 제품 및 서비스의 경계가 모호해질 것입니다. 엣지 디바이스와 클라우드 플랫폼을 모두 보유한 벤더는 현장 방문 없이 무선(OTA)을 통해 기능 강화를 제공할 수 있어, 락인(lock-in)을 강화하는 동시에 하드웨어 전문 경쟁사를 시장에서 배제할 수 있습니다. 따라서 스마트 스페이스 시장에서는 일회성 설치에서 라이프사이클 관리로 전환하는 기업이 높이 평가받게 되며, 서비스 부문의 성장 프리미엄이 더욱 강화될 것입니다.
상업용 부동산, 의료, 호텔·관광, 소매의 4개 분야는 2025년 스마트 스페이스 시장 규모의 58.40%에 해당하는 97억 5,000만 달러를 차지했습니다. 사무실에서는 분석 가능한 이용률 데이터가 필요한 유연한 좌석 배치가 추구되는 반면, 병원에서는 감염 예방을 위해 환기량과 기기 가동 시간을 추적하고 있습니다. 그러나 주거 분야, 특히 공동 주택 수요는 연평균 성장률(CAGR) 13.28%로 증가할 것으로 예측됩니다. Logical Buildings사는 수요 반응(Demand Response)을 수익화하기 위해 전체 공동주택 재고에 걸쳐 1억 1,000만 달러 규모의 가상 발전소를 운영하고 있으며, 대규모 주거용 시스템의 경제성을 입증하고 있습니다. SmartRent사는 2024년 12월, 셀프 서비스 입주자용 포털, 출입 통제, 서브미터링 기능을 갖춘 입주자용 셀프 서비스 포털의 임대인 도입 확대를 위해 1,000만 달러를 투자했습니다. 규제 완화된 시장에서는 전력 회사가 피크 절감 프로그램과 연계된 스마트 온도 조절기에 대해 현금 인센티브를 제공함으로써, 주택 소유자의 이익과 전력망의 안정성을 동시에 확보하고 있습니다. 소비자의 가격 민감도는 여전히 제약 요인으로 작용하고 있지만, 광대역과 에너지를 결합한 패키지를 통해 도입 장벽이 낮아지면서, 2030년까지 스마트 홈 시장은 각 부문 간 수요가 균형을 이루는 방향으로 나아가고 있습니다.
또한 규제 당국은 EU 일부 지역과 미국의 특정 주에서 신축 아파트에 서브미터 설치를 의무화함으로써 가정의 에너지 관리를 촉진하고 있습니다. 이러한 정책적 호재에 힘입어 주거용 시장 규모는 확대되고 있으나, 단위당 수익은 상업용 평균보다 낮은 수준입니다. 각 벤더사는 보안, 웰니스,고령자 돌봄 모니터링에 이르는 플랫폼 기반의 다중 제품 교차 판매를 통해 이익률 하락에 대응하고 있습니다. 서비스 포트폴리오가 풍부해짐에 따라 주거용 시장의 성장 곡선은 상업 분야 기존 기업들과의 격차를 좁혀가고 있으며, 이는 스마트 스페이스 산업이 유비쿼터스 인프라 계층으로 진화하고 있음을 뒷받침합니다.
지역별 분석
북미는 주 차원의 엄격한 에너지 규제와 하이브리드 근무 분석의 조기 도입에 힘입어 2025년 매출의 36.40%를 차지했습니다. 캘리포니아주의 적극적인 기준과 연방 세액 공제가 대규모 개조를 촉진하는 한편, 물류 단지에서 진행된 민간 주도형 5G 시범 사업은 지연에 민감한 이용 사례의 유효성을 입증하고 있습니다. 하네웰은 2025년 1분기에 건물 자동화 제품 라인 전체에서 8%의 유기적 성장을 기록했습니다. 이는 클라우드 네이티브 대시보드에 대한 미국 수요에 힘입은 결과입니다. 사이버 보안 규제로 인해 기업들이 규정 준수 업무를 신뢰할 수 있는 공급업체에 위탁하는 움직임이 가속화되면서 관리형 서비스 도입이 확대되고 있습니다. 노후된 건물의 개보수 비용이 확장 속도를 둔화시키고 있지만, 측정된 절감액에 보상을 연동하는 성과 연동형 계약을 통해 보수적인 예산 활용이 가능해지면서 스마트 스페이스 시장은 견조한 성장 궤도를 유지하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 13.06%의 궤도에 올라 있으며, 세계 시장 규모에서 점점 더 큰 비중을 차지하게 될 것입니다. 중국은 2024년도 예산에서 스마트 시티 시범 사업에 45억 달러를 배정하고, 모든 신규 시 소유 건물에 디지털 트윈 도입을 의무화하고 있습니다. 일본의 ‘사회 5.0’ 로드맵에서는 스마트 빌딩이 로봇 공학 및 모빌리티 네트워크와 같은 더 광범위한 분야와 통합되어 있는 반면,인도의 ‘스마트 시티 미션’은 총액 196억 7,000만 달러에 달하는 8,000건의 진행 중인 프로젝트를 포괄하고 있습니다. 기업의 투자도 공공 부문의 노력과 발맞추고 있습니다. 예를 들어, 후지산 근교에 위치한 토요타의 ‘Woven City’는 센서가 밀집된 도시 경관을 시험적으로 구축하는 민간 테스트베드 역할을 하고 있습니다. 규제 환경의 이질성이 다국적 기업의 사업 확장을 복잡하게 만들고 있지만, 도시의 밀집화, 에너지 안보, 고령화 같은 공통 과제가 지역 전체 수요를 뒷받침하고 있습니다. 유럽에서는 기후 정책을 배경으로 꾸준한 성장을 유지하고 있습니다. EU의 제로 배출 의무화로 인해 비효율적인 제어 시스템을 대체하는 시장이 보장되고 있으며, GDPR(EU 개인정보보호규정)(일반 데이터 보호 규정)에 따라 ‘프라이버시 바이 디자인’ 기능이 프리미엄 가격으로 제공될 수 있게 되었습니다. 지멘스는 디지털 트윈을 활용해 베를린의 ‘지멘스슈타트’를 재탄생시키기 위해 7억 5,000만 유로를 투자하며, 스마트 캠퍼스 모델에 대한 자신감을 보여주고 있습니다. 중동 및 아프리카에서는 도입이 다소 뒤처지고 있지만, 대규모 프로젝트가 주목을 받고 있습니다. 사우디아라비아의 ‘네옴’과 UAE의 ‘마스다르 시티’는 완전히 디지털화된 건축 구조에 의존하고 있으며, 이 지역의 실증 사례로 자리 잡고 있습니다. 예산 변동이나 정치적 리스크로 인해 도입은 정부 지원 사업에 치우치는 경향이 있지만, 입증된 수익성이 시간이 지남에 따라 민간 공동 투자자를 유치하여 대상 스마트 스페이스 시장의 확대로 이어지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the smart spaces market size is expected to grow from USD 16.70 billion in 2025 to USD 18.69 billion in 2026 and is forecast to reach USD 32.86 billion by 2031 at 11.94% CAGR over 2026-2031.
[1] Thread Group, "Thread 1.4 Product Certifications Pass 670 Milestone," threadgroup.org The upward trajectory is shaped by falling IoT sensor prices that simplify large-scale deployment, mandatory net-zero building codes that accelerate digital retrofits, and hybrid-work policies that reward real-time space optimisation. This report is Segmented by Type (Solutions and Services), End-User Industry (Commercial and Residential), Application (Energy Management, Occupancy and Space Analytics, Lighting and HVAC Control, and More), Connectivity Technology (Wi-Fi, Zigbee, Z-Wave, and More), and Geography.
Global Smart Spaces Market Trends and Insights
IoT-enabled device proliferation and falling sensor prices
Semiconductor oversupply has pushed sensor average selling prices down by double-digits since 2023, allowing building owners to blanket properties with occupancy, air-quality and power-meter nodes that feed granular data to cloud analytics. More than 670 Thread-certified devices shipped by early 2025, a clear signal that vendors now view multi-vendor interoperability as table stakes. A 352-sensor deployment at Milesight's headquarters cut annual utilities by USD 45,000, a case that has circulated widely among facilities managers. Expanded memory bandwidth in edge AI chips eliminates latency penalties and supports real-time control loops, yet brownfield integration still varies by legacy wiring and controls. As capital costs decline, decisions hinge on energy-saving proof points rather than hardware affordability, a pivot that keeps the Smart space market in a demand-led cycle.
Accelerated hybrid-work redesign of offices
Hybrid scheduling fluctuates weekday headcounts, making legacy time-of-day HVAC programming obsolete. Johnson Controls logged 16% order growth in Q1 2025 for adaptive controls that modulate airflow and lighting to actual presence rather than historical averages. A Washington D.C. office building realised 33% energy savings after replacing static set-points with multi-sensor occupancy data that instructs chillers to follow demand curves. AI ventilation models have kept CO2 concentrations below 1,000 ppm while trimming ventilation energy by 12.5%, aligning wellness goals with bottom-line targets. The commercial landlord community is experimenting with dynamic rent that flexes by verified utilisation, turning data exhaust into revenue streams. Real-time analytics, however, require cyber-hardened networks and secure data lakes to protect tenant privacy under GDPR and CCPA.
High upfront retrofit costs for brown-field buildings
Older properties often contain proprietary HVAC or lighting systems that resist open-protocol overlays. QuadReal required a passive optical backbone across 30 million sq ft to unify disparate subsystems, a capital project justifiable only by projected 50-70% operational savings. Limbach's digitisation of 20 sites spanning multiple HVAC vintages exposed inconsistent data granularity that complicated analytics. Pilot programmes such as PHOENIX delivered headline efficiency gains of 39-61% but demanded customised middleware to normalise telemetry. Energy-service-company financing and outcome-based leases help convert cash outlays into service fees, yet decision cycles still elongate when stakeholders must coordinate mechanical, electrical, and IT upgrades under one project charter.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory green-building / net-zero regulations
- Rapid 5G private-network rollouts in commercial estates
- Cyber-security and data-privacy liabilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions retained the lion's share at 67.35% of 2025 revenue, equal to USD 11.25 billion of the Smart space market size. Hardware devices and supervisory software form the digital backbone, yet end-users increasingly outsource optimisation to third parties. Services are set to post a 13.61% CAGR, reflecting appetite for continuous commissioning, remote diagnostics, and AI-driven decision support. BrainBox AI launched its generative building assistant in March 2024, enabling conversational queries about energy anomalies and prescriptive adjustments. Trane Technologies quickly folded the capability into its aftermarket portfolio, bundling autonomous HVAC controls inside outcome-based contracts that guarantee double-digit utility cuts. Managed-service vendors monetise hourly telemetry by feeding algorithms that keep chillers within narrow set-point bands, reducing wear and curbing carbon fees. As labour shortages constrain in-house facility teams, executives view external expertise as risk insurance against performance penalties.
In the long run, hybrid cloud architectures will blur product and service boundaries because device firmware, analytics models, and security patches update continuously. Vendors that own both edge devices and cloud platforms can push over-the-air enhancements without onsite visits, deepening lock-in while squeezing pure-play hardware rivals. The Smart space market therefore rewards firms that pivot from one-and-done installations toward lifecycle stewardship, reinforcing the Services growth premium.
Commercial real estate, healthcare, hospitality and retail collectively generated 58.40% of 2025 revenue, or USD 9.75 billion of the Smart space market size. Offices pursue flexible seating that demands analytics-ready occupancy data, whereas hospitals track air exchange and device uptime for infection control. Yet residential demand, especially in multi-dwelling units, is forecast to rise at a 13.28% CAGR. Logical Buildings is orchestrating a USD 110 million virtual power plant across multifamily stock to monetise demand response, demonstrating fleet-scale residential economics. SmartRent earmarked USD 10 million in December 2024 to widen landlord adoption of self-service resident portals, access control, and sub-metering. Utilities in deregulated markets offer cash incentives for smart thermostats linked to peak-shave programmes, aligning homeowner interests with grid stability. While consumer price sensitivity remains a restraint, bundled broadband plus energy packages lower acquisition friction, tilting the Smart space market toward balanced demand across sectors by 2030.
Regulators also push home energy management via mandatory sub-meters in new apartments across parts of the EU and select US states. This policy tailwind elevates residential volumes, though per-unit revenue lags commercial averages. Vendors combat margin dilution through platform multiproduct cross-sales spanning security, wellness and eldercare monitoring. As service portfolios deepen, the residential curve narrows its gap with commercial incumbents, confirming the Smart space industry's evolution into a ubiquitous infrastructure layer.
Complete Report Scope:
- By Type
- Solutions
- Software Platforms
- Hardware and Edge Devices
- Services
- Professional Services
- Managed Services
- Solutions
- By End-user Industry
- Commercial
- Offices and Co-working Spaces
- Retail and Malls
- Healthcare Facilities
- Hospitality and Leisure
- Residential
- Single-family Homes
- Multi-dwelling Units
- Commercial
- By Application
- Energy Management
- Occupancy and Space Analytics
- Lighting and HVAC Control
- Security and Access Management
- Facility Automation Integration Platforms
- By Connectivity Technology
- Wi-Fi
- Bluetooth Low Energy (BLE)
- Zigbee
- Thread / Matter
- Z-Wave
- NB-IoT and LoRaWAN
- Wired (Ethernet / PoE)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Argentina
- Brazil
- Rest of South America
- Europe
- United Kingdom
- France
- Germany
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- Nigeria
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America contributed 36.40% of 2025 revenue, driven by stringent state-level energy codes and early adoption of hybrid-work analytics. California's aggressive standards and federal tax credits support deep retrofits, while private 5G pilots in logistics parks validate latency-sensitive use cases. Honeywell recorded 8% organic growth across its building automation lines in Q1 2025, underpinned by US demand for cloud-native dashboards. Cyber-security regulation accelerates managed-service uptake as firms outsource compliance tasks to trusted vendors. Retrofit costs for ageing stock temper rollout pace, but outcome-based contracts that tie fees to measured savings unlock conservative budgets, keeping the Smart space market on a solid expansion path.
Asia Pacific is on track for a 13.06% CAGR and will increasingly tilt global volume. China allocated USD 4.5 billion to smart city pilots in its 2024 budget, stipulating that all new municipal buildings integrate digital twins. Japan's Society 5.0 roadmap bundles smart buildings with wider robotics and mobility networks, while India's Smart Cities Mission spans 8,000 live projects worth USD 19.67 billion. Corporate investments match the public push: Toyota's Woven City near Mount Fuji serves as a private testbed for sensor-dense neighbourhoods. Heterogeneous regulatory landscapes complicate multinational scaling, but common motivations-urban density, energy security and ageing populations-sustain demand across the region. Europe maintains disciplined growth on the back of climate policy. The EU's zero-emission mandate guarantees a replacement market for inefficient controls, and GDPR ensures that privacy-by-design features carry premium pricing. Siemens committed EUR 750 million to regenerate Berlin's Siemensstadt with digital twins, reflecting confidence in smart campus models. Middle East and Africa trail in adoption but showcase showcase megaprojects: Saudi Arabia's Neom and the UAE's Masdar City rely on fully digital building fabrics, serving as regional proof points. Budget volatility and political risk keep deployment skewed to government-backed ventures, yet demonstrable returns draw private co-investors over time, widening the addressable Smart spaces market.
- ABB Ltd
- Siemens AG
- Cisco Systems Inc.
- Schneider Electric SE
- IBM Corporation
- Microsoft Corporation
- Honeywell International Inc.
- Johnson Controls International
- Huawei Technologies Co. Ltd.
- Hitachi Vantara LLC
- ICONICS Inc.
- Spacewell (Nemetschek Group)
- SmartSpace Software PLC
- Ubisense Ltd.
- Adappt Intelligence Inc.
- Enlighted Inc. (Siemens)
- Bosch Building Technologies
- Legrand SA
- Crestron Electronics Inc.
- Verkada Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IoT-enabled device proliferation and falling sensor prices
- 4.2.2 Accelerated post-COVID hybrid-work redesign of offices
- 4.2.3 Mandatory green-building / net-zero regulations
- 4.2.4 Rapid 5G private-network roll-outs in commercial estates
- 4.2.5 AI-driven workplace analytics reducing real-estate OPEX
- 4.2.6 Rise of occupancy-based insurance and leasing models
- 4.3 Market Restraints
- 4.3.1 High upfront retro-fit costs for brown-field buildings
- 4.3.2 Cyber-security and data-privacy liabilities
- 4.3.3 Inter-vendor interoperability gaps and standards fragmentation
- 4.3.4 Volatility in commercial real-estate valuations
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Solutions
- 5.1.1.1 Software Platforms
- 5.1.1.2 Hardware and Edge Devices
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Solutions
- 5.2 By End-user Industry
- 5.2.1 Commercial
- 5.2.1.1 Offices and Co-working Spaces
- 5.2.1.2 Retail and Malls
- 5.2.1.3 Healthcare Facilities
- 5.2.1.4 Hospitality and Leisure
- 5.2.2 Residential
- 5.2.2.1 Single-family Homes
- 5.2.2.2 Multi-dwelling Units
- 5.2.1 Commercial
- 5.3 By Application
- 5.3.1 Energy Management
- 5.3.2 Occupancy and Space Analytics
- 5.3.3 Lighting and HVAC Control
- 5.3.4 Security and Access Management
- 5.3.5 Facility Automation Integration Platforms
- 5.4 By Connectivity Technology
- 5.4.1 Wi-Fi
- 5.4.2 Bluetooth Low Energy (BLE)
- 5.4.3 Zigbee
- 5.4.4 Thread / Matter
- 5.4.5 Z-Wave
- 5.4.6 NB-IoT and LoRaWAN
- 5.4.7 Wired (Ethernet / PoE)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Argentina
- 5.5.2.2 Brazil
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 France
- 5.5.3.3 Germany
- 5.5.3.4 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 Nigeria
- 5.5.5.2.2 South Africa
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Cisco Systems Inc.
- 6.4.4 Schneider Electric SE
- 6.4.5 IBM Corporation
- 6.4.6 Microsoft Corporation
- 6.4.7 Honeywell International Inc.
- 6.4.8 Johnson Controls International
- 6.4.9 Huawei Technologies Co. Ltd.
- 6.4.10 Hitachi Vantara LLC
- 6.4.11 ICONICS Inc.
- 6.4.12 Spacewell (Nemetschek Group)
- 6.4.13 SmartSpace Software PLC
- 6.4.14 Ubisense Ltd.
- 6.4.15 Adappt Intelligence Inc.
- 6.4.16 Enlighted Inc. (Siemens)
- 6.4.17 Bosch Building Technologies
- 6.4.18 Legrand SA
- 6.4.19 Crestron Electronics Inc.
- 6.4.20 Verkada Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


