|
시장보고서
상품코드
2123073
가상사설망(VPN) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Virtual Private Network - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 가상사설망(VPN) 시장 규모는 2025년 612억 6,000만 달러에서 2026년에는 704억 6,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 15.05%로 성장을 지속하여, 2031년에는 1,420억 6,000만 달러에 이를 것으로 예측됩니다.
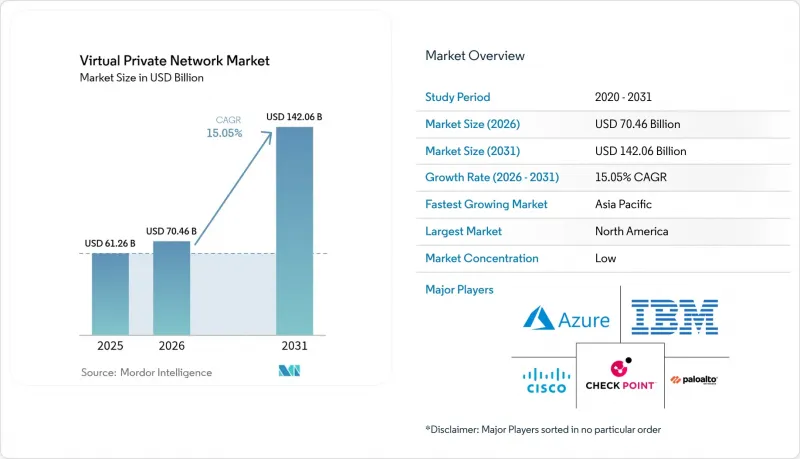
본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 유형(호스팅형/관리형, IPsec VPN, MPLS VPN 등), 배포 모드(클라우드, On-Premise), 최종 사용자 산업(은행, 금융서비스 및 보험(BFSI), 헬스케어 및 생명과학, IT 및 통신 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 가상사설망(VPN) 시장 동향 및 인사이트
보안 원격 접속에 대한 하이브리드 인력의 의존도 증가
업무 방식의 변화로 인해 VPN 연결은 비즈니스에 필수적인 요소가 되었습니다. 뉴욕시 교육청은 100만 명 이상의 사용자와 200만 대 이상의 기기를 제로 트러스트 프레임워크로 전환한 결과, 공격 건수가 15% 감소한 반면 차단된 위협은 40% 증가했다고 보고했습니다. 기업에서는 트래픽을 용도으로 직접 라우팅하여 기존 콘센트레이터에서 발생하는 지연이나 패치 적용에 따른 부담을 해소하는 클라우드 네이티브 SASE 플랫폼의 도입이 점점 더 확대되고 있습니다.
암호화된 연결이 필요한 IoT 기기의 급증
현재 산업용 네트워크에서는 세밀한 ID 기반 액세스 제어가 요구되고 있습니다. 시스코의 ‘Secure Equipment Access’는 광범위한 VPN 터널을 대체하여 운영 기술(OT) 리소스에 대해 세밀한 제로 트러스트 제어를 실현합니다. 광둥대학교에서는 차이나모바일의 5G VPN이 기존 솔루션에 비해 다운링크 속도를 10배로 높였을 뿐만 아니라, 2만 명의 동시 사용자를 지원했습니다.
VPN/SASE 관리 인력 부족이 총 소유 비용을 상승시키고 있다.
숙련된 엔지니어에 대한 수요가 공급을 초과함에 따라, 조직들은 매니지드 서비스로의 전환을 피할 수 없게 되었습니다. 각 제공업체에 따르면 인건비가 총 운영비의 30%에 육박함에 따라, 고객들은 수동 유지보수 작업을 줄일 수 있는 통합형 SASE 솔루션으로 유도되고 있습니다.
부문 분석
2025년, 가상사설망(VPN) 시장의 42.80%를 하드웨어 어플라이언스가 차지하며, 많은 대규모 원격 액세스 도입을 뒷받침했습니다. 이 부문의 견조한 성장은 On-Premise 환경에서 규정 준수 요건이 부과되는 업계의 긴 교체 주기에 기인합니다. 반면, 소프트웨어는 연평균 성장률(CAGR) 15.72%로 성장하고 있으며, 하이퍼스케일 클라우드에서 몇 분 만에 배포할 수 있는 컨테이너형 게이트웨이 및 가상 방화벽이 그 원동력이 되고 있습니다. 반도체 관련 공급망의 긴축으로 인해 AWS나 Azure상의 pfSense Plus와 같은 클라우드 호스팅형 이미지의 채택이 촉진되며, 개념 증명(PoC)이 가속화되고 있습니다. 관리형 운영 및 도입 프로젝트에 이르는 서비스 수익은 SASE로의 전환에 따라 확대되고 있으며, 현재 구성 요소별 지출의 세 번째 축을 형성하고 있습니다. 기업들은 온사이트 성능 향상을 위한 하드웨어와 도달 범위 확대를 위한 소프트웨어 게이트웨이를 결합하고 있으며, 이는 대체가 아닌 공존을 시사합니다.
기업들이 유지보수 부담을 전문가에게 이관함에 따라, 2025년에는 호스팅형 및 관리형 서비스가 가상사설망(VPN) 시장 점유율의 24.45%를 차지했습니다. 이러한 서비스는 예측 가능한 구독 모델을 통해 지속적인 업데이트, 위협 인텔리전스 피드, 연중무휴 24시간 모니터링을 통합하고 있습니다. 한편, MPLS VPN은 부활의 조짐을 보이고 있으며, 기업들이 하이브리드 클라우드 및 미션 크리티컬한 협업을 위해 결정론적 지연 시간을 필요로 함에 따라 연평균 성장률(CAGR) 16.52%로 성장하고 있습니다. 클라우드 VPN 및 더 광범위한 SASE 제품군은 IPsec, SD-WAN 및 서비스형 방화벽(FWaaS)을 통합된 오케스트레이션 하에 통합하여 정책의 난립을 해소하고 있습니다. IPsec VPN은 확립된 프로토콜 인증을 준수해야 하는 국방 기관 및 정부 기관에 여전히 필수적이지만, 새롭게 등장한 WireGuard 솔루션은 간소화된 코드베이스와 니어라인 속도의 처리량을 중시합니다.
지역별 분석
북미는 2025년에도 가상사설망 시장 매출의 26.85%를 차지하며 여전히 최대 지역 시장으로 남아 있습니다. 초기 단계의 제로 트러스트 도입 시험과 엄격한 정보 유출 공개 규제로 인해 지출 모멘텀은 유지되고 있습니다. 연방 및 주 정부 프로그램에 힘입어 IPsec 컨센트레이터에서 신원 중심 SASE 노드로의 업그레이드가 가속화되고 있는 한편, 하이퍼스케일러에 의한 고밀도 PoP(Point of Presence) 구축으로 분산된 사용자에 대한 지연 시간이 최소화되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 15.96%로 가장 빠른 성장세를 보이고 있습니다. 대규모 디지털화 프로그램과 사이버 보험 가입률 상승이 맞물리면서, 기업들은 클라우드 워크로드와 모바일 인력의 보안을 확보해야 하는 압박을 받고 있습니다. 중국 대학에서 실시된 시범 운영에서는 5G 독립형(SA) 네트워크상의 모바일 VPN 성능이 10배 향상된 것으로 입증되었습니다. 인도의 금융 규제 당국은 현재 외부 처리 센터에 대해 암호화된 연결을 의무화하고 있으며, 이는 도입을 더욱 촉진하고 있습니다.
유럽에서는 일반 데이터 보호 규정(GDPR(EU 개인정보보호규정))의 시행에 따라 꾸준한 진전이 나타나고 있습니다. 기업들은 주권을 확보하기 위해 해당 지역 내에 데이터센터를 보유한 제공업체를 우선적으로 선택하고 있으며, 규정 준수를 위해 많은 기업이 VPN에 데이터 유출 방지 기능을 결합하고 있습니다. 독일과 프랑스의 정부 프로젝트에서는 새로운 원격 액세스 조달 시, 포스트 양자암호화에 대한 대응을 요건으로 명시하고 있습니다.
한편, 중동 및 아프리카에서는 Starlink의 확산으로 지방에도 광대역이 보급되고 있으며, 신흥 전자상거래 및 전자정부 트래픽을 보호하기 위해 VPN 서비스가 활용되고 있습니다. 라틴아메리카에서는 브라질의 은행과 멕시코의 소매업체들이 현지 인력 부족을 보완하기 위해 매니지드 VPN을 도입하고 있어, 그 보급이 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the virtual private network market size is expected to grow from USD 61.26 billion in 2025 to USD 70.46 billion in 2026 and is forecast to reach USD 142.06 billion by 2031 at 15.05% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Type (Hosted/Managed, Ipsec VPN, MPLS VPN and More), Deployment Mode (Cloud, On-Premise), End-User Industry (BFSI, Healthcare and Life Sciences, IT and Telecom and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Virtual Private Network Market Trends and Insights
Rising Hybrid-Workforce Dependence on Secure Remote Access
Shifts in work patterns have elevated VPN connectivity to business-critical status. The New York City Department of Education migrated more than 1 million users and 2 million devices to a zero-trust framework and reported a 15% reduction in attacks alongside a 40% increase in blocked threats. Enterprises increasingly adopt cloud-native SASE platforms that route traffic directly to applications, eliminating the latency and patching burdens found in traditional concentrators.
Proliferation of IoT Devices Requiring Encrypted Connectivity
Industrial networks now demand granular, identity-based access. Cisco's Secure Equipment Access replaces broad VPN tunnels with fine-grained, zero-trust controls for operational technology resources. At Guangdong University, China Mobile's 5G VPN delivered ten-fold downlink speed versus legacy solutions while supporting 20,000 concurrent users.
Talent Shortage in VPN/SASE Administration Inflating Total Cost of Ownership
Demand for skilled engineers exceeds supply, pushing organizations toward managed services. Providers report staffing outlays approaching 30% of total operating expense, steering customers to integrated SASE offerings that reduce manual upkeep.
Other drivers and restraints analyzed in the detailed report include:
- Escalating Ransomware Losses Driving Zero-Trust Network Spending
- Cloud-Native Application Adoption Boosting Demand for Cloud VPN and SASE
- Performance and Latency Penalties Versus SDP and ZTNA Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware appliances accounted for 42.80% of the virtual private network market in 2025, underpinning many large-scale remote access roll-outs. Segment resilience is tied to long refresh cycles in sectors with on-premises compliance mandates. Yet software is growing at a 15.72% CAGR, fueled by containerized gateways and virtual firewalls that deploy in minutes on hyperscale clouds. Supply-chain tightness around semiconductors catalyzed adoption of cloud-hosted images such as pfSense Plus on AWS and Azure, accelerating proofs of concept. Services revenue, spanning managed operations and implementation projects, scales in tandem with SASE transitions and currently forms the third pillar of component spend. Organizations continue to blend hardware for on-site performance with software gateways to extend reach, signalling coexistence rather than replacement.
Hosted and managed offerings secured 24.45% of virtual private network market share in 2025 as enterprises shifted maintenance burdens to specialists. These services integrate continuous updates, threat intelligence feeds, and 24X7 monitoring within predictable subscription models. Meanwhile, MPLS VPN shows a renaissance, pacing at 16.52% CAGR as firms require deterministic latency for hybrid cloud and mission-critical collaboration. Cloud VPN and broader SASE suites converge IPsec, SD-WAN, and firewall-as-a-service under unified orchestration, trimming policy sprawl. IPsec VPN remains essential for defense and government entities adhering to established protocol accreditation, while emerging WireGuard solutions emphasize streamlined code bases and near-line-rate throughput.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Type
- Hosted / Managed
- IPsec VPN
- MPLS VPN
- Cloud VPN / SASE
- Others
- By Deployment Mode
- Cloud
- On-premise
- By End-User Industry
- BFSI
- Healthcare and Life Sciences
- IT and Telecom
- Government and Public Sector
- Manufacturing and Industrial
- Retail and E-Commerce
- Education
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America remained the largest regional contributor with 26.85% of virtual private network market revenue in 2025. Spending momentum is sustained by early zero-trust pilots and stringent breach disclosure regulations. Federal and state programs accelerate upgrades from IPsec concentrators to identity-centric SASE nodes, while hyperscalers' dense PoP distribution keeps latency low for dispersed users.
Asia-Pacific delivers the fastest expansion at 15.96% CAGR. Massive digitization programs, combined with rising cyber insurance uptake, push enterprises to secure cloud workloads and mobile workforces. Trials in Chinese universities demonstrate ten-fold performance gains for mobile VPN on 5G stand-alone networks. India's financial regulators now require encrypted connectivity for outsourced processing centers, further catalyzing adoption.
Europe maintains steady progress under General Data Protection Regulation enforcement. Enterprises prefer providers with in-region data centers to ensure sovereignty, and many layer VPN with data-loss prevention for compliance. Government projects in Germany and France specify post-quantum readiness in new remote access procurement.
Meanwhile, Middle East and Africa benefit from Starlink roll-outs that extend broadband to rural districts; VPN services ride on top to protect emerging e-commerce and e-government traffic. Latin America gains traction as Brazilian banks and Mexican retailers embrace managed VPN to bypass local talent shortages.
- Cisco Systems Inc.
- Microsoft Corp. (Azure)
- Palo Alto Networks Inc.
- Check Point Software Technologies Ltd.
- IBM Corp.
- Nord Security (NordVPN)
- Kape Technologies PLC (ExpressVPN, CyberGhost)
- Avast s.r.o. (AVG Secure)
- Fortinet Inc.
- Juniper Networks Inc.
- OpenVPN Inc.
- Citrix Systems Inc.
- Array Networks Inc.
- NetMotion Software Inc. (Absolute Secure Access)
- Golden Frog GmbH (VyprVPN)
- Cloudflare Inc. (Cloudflare One / WARP)
- Google LLC (Google VPN)
- McAfee LLC
- Sophos Ltd.
- F5 Inc. (BIG-IP APM)
- Zscaler Inc. (Zscaler Private Access)
- Barracuda Networks Inc.
- Perimeter 81 Ltd.
- Tailscale Inc.
- WireGuard Development Team
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising hybrid-workforce dependence on secure remote access
- 4.2.2 Proliferation of IoT devices requiring encrypted connectivity
- 4.2.3 Escalating ransomware losses driving zero-trust network spending
- 4.2.4 Cloud-native application adoption boosting demand for Cloud VPN and SASE
- 4.2.5 Emergence of privacy regulations (GDPR, CPRA, LGPD) spurring corporate VPN roll-outs
- 4.2.6 Satellite broadband expansion in emerging regions unlocking new VPN user bases
- 4.3 Market Restraints
- 4.3.1 Talent shortage in VPN/SASE administration inflating total cost of ownership
- 4.3.2 Performance/latency penalties versus SDP and ZTNA alternatives
- 4.3.3 Heightened regulatory scrutiny on consumer VPN logging practices
- 4.3.4 Commodity pricing wars among 400+ retail VPN brands squeezing margins
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (WireGuard, Post-Quantum, SASE Convergence)
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Type
- 5.2.1 Hosted / Managed
- 5.2.2 IPsec VPN
- 5.2.3 MPLS VPN
- 5.2.4 Cloud VPN / SASE
- 5.2.5 Others
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-premise
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 Healthcare and Life Sciences
- 5.4.3 IT and Telecom
- 5.4.4 Government and Public Sector
- 5.4.5 Manufacturing and Industrial
- 5.4.6 Retail and E-Commerce
- 5.4.7 Education
- 5.4.8 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Netherlands
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Share, Products and Services, Recent Developments)
- 6.4.1 Cisco Systems Inc.
- 6.4.2 Microsoft Corp. (Azure)
- 6.4.3 Palo Alto Networks Inc.
- 6.4.4 Check Point Software Technologies Ltd.
- 6.4.5 IBM Corp.
- 6.4.6 Nord Security (NordVPN)
- 6.4.7 Kape Technologies PLC (ExpressVPN, CyberGhost)
- 6.4.8 Avast s.r.o. (AVG Secure)
- 6.4.9 Fortinet Inc.
- 6.4.10 Juniper Networks Inc.
- 6.4.11 OpenVPN Inc.
- 6.4.12 Citrix Systems Inc.
- 6.4.13 Array Networks Inc.
- 6.4.14 NetMotion Software Inc. (Absolute Secure Access)
- 6.4.15 Golden Frog GmbH (VyprVPN)
- 6.4.16 Cloudflare Inc. (Cloudflare One / WARP)
- 6.4.17 Google LLC (Google VPN)
- 6.4.18 McAfee LLC
- 6.4.19 Sophos Ltd.
- 6.4.20 F5 Inc. (BIG-IP APM)
- 6.4.21 Zscaler Inc. (Zscaler Private Access)
- 6.4.22 Barracuda Networks Inc.
- 6.4.23 Perimeter 81 Ltd.
- 6.4.24 Tailscale Inc.
- 6.4.25 WireGuard Development Team
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment