|
시장보고서
상품코드
2123094
자동차 생체인식 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Biometric In The Automotive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
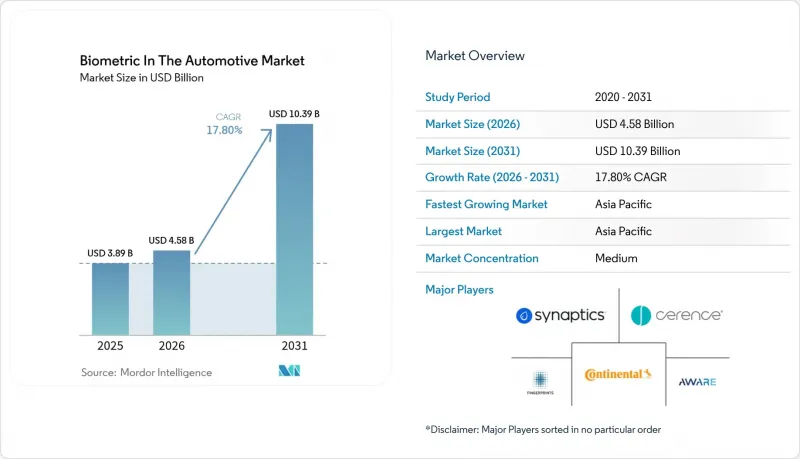
에 의하면, 2026년 자동차 생체인식 시장 규모는 45억 8,000만 달러로 추정되고 있어 2025년 38억 9,000만 달러에서 확대해, 2031년에는 103억 9,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR)은 17.80%를 나타낼 것으로 전망됩니다.
본 보고서는 구성 요소(하드웨어 및 소프트웨어), 생체인식 방식(지문 인증, 홍채 인증 등), 차량 유형(승용차, 소형 상용차 등), 용도(운전자 인증 및 접근 관리 등), 판매 채널(OEM 장착 및 애프터마켓), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 자동차 생체인식 시장 동향 및 인사이트
비접촉식 차량 접근 및 개인화 수요 증가
소비자들은 이제 스마트폰만큼이나 신속하게 자신을 인식해 주는 차량 내 환경을 기대하고 있습니다. 2025년 Smart Eye와 FORVIA가 시연한 터치 프리 홍채 및 얼굴 인증 시스템은 도어가 열리기 전에 운전자나 동승자의 신원을 확인하고, 1초 이내에 시트, 미러,인포테인먼트 프로파일을 불러옵니다. 운전자가 바뀔 때마다 수동으로 프로파일을 재설정할 필요가 없어지므로, 공유 모빌리티 사업자는 추가적인 부가가치를 얻을 수 있습니다. Synaptics는 2016년부터 Tier 1 공급업체를 대상으로 ‘Natural ID’ 지문 인증 키트를 출하해 왔으며, 스와이프나 탭 제스처를 인증과 메뉴 조작 모두에 활용할 수 있도록 하고 있습니다. 이를 통해 차량 내 버튼이 간소화되고 인체공학적 편의성이 향상되는 한편, 1초 미만의 프로파일 불러오기 속도는 고객 만족도를 높여주며, OEM 제조업체에게는 경쟁사가 단기간 내에 따라잡기 어려운 차별화 요소를 제공합니다. 이러한 장점 덕분에 사용자 경험의 기준이 높아짐에 따라, 자동차 생체인식 기술 보급이 가속화되고 있습니다.
엄격한 자동차 안전 및 보안 규제
2026년부터 시행되는 유럽의 UNECE 운전자 모니터링 규정과 Euro NCAP의 운전자 모니터링 성능 및 별점 평가 연동에 따라, 생체인식은 틈새 고급 기능에서 규정 준수 요건으로 변화했습니다. ISO/IEC TS 22604:2024는 주행 중인 차량에 접근하는 운전자를 위한 비접촉식 생체인식을 공식적으로 규정하고 있으며, 차량용 보안 인터페이스에 관한 ISO 규격은 하드웨어에 대한 요구 사항을 통일하고 있습니다. 중국에서는 2025년 6월에 공표된 얼굴 인식 가이드라인에 따라 10만 명 이상의 대상자에 대해 데이터 현지화가 의무화되었으며, 각 OEM 업체들은 기기 내 대조 기능을 탑재할 수밖에 없게 되었습니다. 이러한 규제들이 맞물리면서 설계 주기가 가속화되고, 자동차 생체인식 기술 도입이 구조적인 성장 궤도를 유지할 것이 보장됩니다.
세계 표준 및 상호 운용성의 부재
자발적인 ISO 및 FIDO 사양에는 강제력 있는 국경을 초월한 상호 인정이 부족하기 때문에 각 OEM 업체는 유럽, 중국, 미국별로 하드웨어 인증을 개별적으로 취득해야 합니다. 중국의 데이터 현지화 규제로 인해 유럽의 렌터카 회사는 중국 내에서 자사의 운전자 데이터베이스를 재사용할 수 없게 되었으며, 차량 운영 사업자는 사일로화된 시스템을 유지할 수밖에 없는 실정입니다. 소규모 애프터마켓 공급업체들은 재시험에 드는 비용으로 어려움을 겪고 있으며, 이로 인해 가격에 민감한 지역에서 제품의 가용성이 제한되고, 자동차 생체인식 기술의 보급이 지연되고 있습니다.
부문 분석
2025년에는 매출의 64.55%를 하드웨어가 차지하며, 이는 자동차 생체인식 기술이 전통적으로 센서를 많이 사용해 온 역사를 반영합니다. 반면, 소프트웨어는 연평균 성장률(CAGR) 18.62%로 확대되고 있습니다. 이는 각 OEM 업체들이 지속적인 인증, 동의 관리, 무선 프로파일 업데이트를 포함한 구독형 라이선스 모델을 선호하기 때문입니다. Synaptics의 ‘Match-in-Sensor’ 아키텍처는 센서 다이 내에서 캡처, 대조, 암호화를 수행하여 가치를 중앙 ECU에서 엣지로 이전하는 동시에, 호스트 수준의 악성 코드로부터 템플릿을 보호합니다.
엣지의 지능화로 인해 생체인식용 펌웨어 가중치가 모듈에 직접 내장됨에 따라 하드웨어와 소프트웨어의 경계가 모호해지고, 수동적인 장치가 지능형 노드로 변모합니다. 그 결과, 라이선싱 수익은 물리적 출하 대수보다 빠르게 증가하고 있으며, 범용 카메라 가격이 하락하더라도 매출 총이익률 확대가 가능해졌습니다. 센서를 안전한 클라우드 API와 통합하는 Tier 1 공급업체는 추가적인 플랫폼 사용료를 확보하여 자동차 생체인식 시장의 수익화 곡선을 가속화할 것입니다.
2025년에는 스마트폰 수준의 기능을 활용하는 저비용 정전용량식 부품 덕분에 지문 인식 기술이 생체인식 시장 점유율의 40.15%를 차지하며 시장을 휩쓸었습니다. 그러나 얼굴 인증은 연간 20.12%의 성장이 예상됩니다. 이는 단일 RGB-IR 카메라로 운전자 모니터링, 탑승자 분류 및 인증이 가능해져, 도어나 대시보드에 별도의 지문 인식기를 설치할 필요가 없어졌기 때문입니다. Smart Eye가 Fingerprint Cards로부터 라이선스를 취득한 홍채 인증 SDK는 결제 및 차량 관리 규정 준수에 있어 오인식률 0.01% 미만이 요구되는 프리미엄 부문을 대상으로 합니다.
얼굴과 홍채를 결합한 하이브리드 구성은 신원 도용 위험을 줄이고 새로운 FIDO 테스트 프로토콜도 충족하지만, 손바닥 정맥 인증이나 음성 인증은 환경 소음이나 문화적 선호도 등의 이유로 여전히 틈새 시장에 머물러 있습니다. ISO/IEC TR 24722:2024는 센서 융합의 가중치를 공식적으로 규정하고 있으며, 각 OEM 업체의 멀티모달 스택 채택을 촉진하고 있습니다. 카메라가 기능을 통합함에 따라 생체인식 기능을 하나 추가할 때마다 발생하는 하드웨어의 한계 비용은 감소하는 반면, 차량 1대당 소프트웨어 사용료는 증가하고 있어, 자동차 생체인식 시장에서 플랫폼 경제로의 전환이 더욱 가속화되고 있습니다.
지역별 분석
아시아태평양은 2025년에 매출의 37.95%를 차지하며,중국의 ‘지능형 커넥티드 차량(ICV)’에 대한 이중 의무화 조치와 기기 내 처리를 의무화하는 엄격한 데이터 현지화 규제 덕분에 연평균 성장률(CAGR) 19.98%로 성장할 전망입니다. 중국의 각 OEM 업체들은 현재 할당 요건을 충족하면서도 국경을 넘는 데이터 전송을 피하기 위해 국내 카메라 및 지문 인증 공급업체와 제휴하고 있습니다. 일본에서는 하네다 공항의 운전기사 부족 문제에 대응하기 위해 얼굴 인식 기능을 갖춘 자율주행 셔틀의 실증 실험이 진행되고 있습니다. 한편, 한국과 호주에서는 스마트폰과의 높은 호환성을 활용하여 소비자의 수용을 가속화하고 있습니다. 인도에서는 여전히 가격에 대한 민감성이 나타나고 있지만, 도시 지역에서 도난 방지를 위한 생체인식에 대한 보험상의 우대 조치가 보급을 확대할 가능성이 있는 실증 프로그램을 뒷받침하고 있습니다.
북미와 유럽에서는 국경을 넘어 렌터카 차량 인증을 가능하게 하는 ISO 및 FIDO 표준과의 통합이 진행되고 있습니다. 2026년부터 시행되는 유럽의 UNECE 운전자 모니터링 법에 따라 프로그램 일정이 단축되었으며, 생체인식 기능이 주류 차량 유형에 탑재되고 있습니다. 미국에는 연방 규정이 없지만, 일리노이주의 동의법 및 캘리포니아주의 개인정보 보호법에 따라 기술 제공업체는 Lytx의 ‘Dynamic Adjust’ 지오펜스 등 지역별 맞춤형 개인정보 제어 기능을 구현해야 합니다. 캐나다와 멕시코에서는 상업용 트럭의 주요 노선에 생체인식을 도입하여 통관 절차와 운송업체 감사를 효율화함으로써, 자동차 생체인식 시장의 지역적 성장 동력을 창출하고 있습니다.
중동에서는 자동차 생체인식을 국가 디지털 ID 프로그램의 연장선으로 자리매김하고 있습니다. UAE의 얼굴 인식 도입과 사우디아라비아의 IDEMIA 및 SAMI 간 제휴를 통해 차량 접근 권한과 시민 ID 정보가 연동되며, 고온 환경에 적합한 손바닥 정맥 및 홍채 인증 방식의 조기 시험이 촉진되고 있습니다. 아프리카에서는 여전히 높은 하드웨어 비용과 인프라 격차가 장벽으로 작용하고 있지만, 남아프리카공화국과 나이지리아에서는 물류 허브에서의 도난을 억제하기 위해 차량 군에 생체인식 도입을 추진하고 있습니다. 고온 환경에서의 내구성과 관련된 과제는 여전히 남아 있지만, 내환경성이 뛰어난 광학 모듈은 현재 장기 열침투 시험을 통과하여 점차 보급의 길이 열리고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, biometric in the automotive market size in 2026 is estimated at USD 4.58 billion, growing from 2025 value of USD 3.89 billion with 2031 projections showing USD 10.39 billion, growing at 17.80% CAGR over 2026-2031.
This report is Segmented by Component (Hardware and Software), Biometric Modality (Fingerprint Recognition, Iris Recognition, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Application (Driver Identification and Access, and More), Sales Channel (OEM-Fitted and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Biometric In The Automotive Market Trends and Insights
Rising Demand for Contactless Vehicle Access and Personalization
Consumers now expect a cabin to recognize them as quickly as a smartphone. Touch-free iris and face systems demonstrated by Smart Eye and FORVIA in 2025 verify driver and passenger identities before a door opens, loading seats, mirrors, and infotainment profiles within one second. Shared-mobility operators gain extra value because each hand-off between drivers no longer requires a manual profile reset. Synaptics has shipped Natural ID fingerprint kits to Tier 1 suppliers since 2016, allowing swipe and tap gestures to double as both authentication and menu navigation. The resulting reduction in cabin-button clutter enhances ergonomics, while sub-second profile loading boosts customer satisfaction scores and provides OEMs with a differentiator that is challenging for rivals to replicate quickly. These gains accelerate the biometric in the automotive market as user-experience benchmarks rise.
Stringent Automotive Safety and Security Regulations
Europe's UNECE driver-monitoring rule, effective from 2026, and Euro NCAP's linkage of driver-monitoring performance to star ratings have converted biometrics from a niche luxury to a compliance requirement. ISO/IEC TS 22604:2024 formalizes contactless biometrics for drivers approaching a vehicle while it is in motion, and ISO standards for in-vehicle secure interfaces harmonize hardware expectations. In China, facial-recognition guidelines issued in June 2025 require data localization for over 100,000 subjects, compelling OEMs to embed on-device matching. Together, these mandates accelerate design cycles and ensure that biometric in the automotive market adoption remains on a structural growth trajectory.
Lack of Global Standards and Interoperability
OEMs must certify hardware separately for Europe, China, and the United States because voluntary ISO and FIDO specifications lack enforceable cross-border reciprocity. China's data-localization rule prevents a European rental car company from reusing its driver database within Chinese territory, forcing fleet operators to maintain siloed systems. Smaller aftermarket vendors struggle with the cost of re-testing, which limits product availability in price-sensitive regions and slows the adoption of biometrics in the automotive market.
Other drivers and restraints analyzed in the detailed report include:
- Lower Sensor Costs and Integration into Electronics Architectures
- Insurance Premium Discounts Linked to Anti-Theft Biometrics
- High Initial System Cost in Mass-Market Vehicle Segments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware accounted for 64.55% of revenue in 2025, reflecting the sensor-heavy heritage of biometrics in the automotive market. Software, however, is scaling at 18.62% CAGR because OEMs prefer subscription license models that include continuous authentication, consent management, and over-the-air profile updates. Synaptics' Match-in-Sensor architecture performs capture, matching, and encryption within the sensor die, moving value from the central ECU to the edge and shielding templates from host-level malware.
Edge smartness blurs the hardware-software divide by embedding firmware weights for liveness detection directly onto the module, turning a passive device into an intelligent node. Licensing-focused revenue, therefore, rises faster than physical shipments, enabling gross-margin expansion even as commodity camera prices fall. Tier 1 suppliers that integrate sensors with secure cloud APIs will capture incremental platform fees, accelerating the monetization curve of biometrics in the automotive market.
Fingerprint technology dominated the biometric market share with 40.15% in 2025, due to low-cost capacitive parts that leverage smartphone-scale capabilities. Yet, facial recognition is forecast to rise 20.12% annually, as a single RGB-IR camera now supports driver monitoring, occupant classification, and authentication, eliminating the need for separate fingerprint readers on doors or dashboards. Smart Eye's license of Fingerprint Cards' iris SDK targets premium segments requiring a false-acceptance rate of less than 0.01% for payments and fleet compliance.
Hybrid face-iris configurations reduce spoof risk and satisfy emerging FIDO test protocols, while palm-vein and voice remain niche due to environmental noise and cultural preferences. ISO/IEC TR 24722:2024 formalizes sensor-fusion weighting, encouraging OEMs to adopt multimodal stacks. As cameras consolidate functions, the marginal hardware cost per additional biometric decreases, while software royalties per vehicle increase, reinforcing the shift toward platform economics in the biometric automotive market.
Complete Report Scope:
- By Component
- Hardware
- Software
- By Biometric Modality
- Fingerprint Recognition
- Iris Recognition
- Palm Recognition
- Facial Recognition
- Voice Recognition
- Other Modalities
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Trucks
- Buses and Coaches
- Specialty Vehicles
- By Application
- Driver Identification and Access
- Engine Start / Immobilizer
- In-Car Payments
- Driver Health and Drowsiness Monitoring
- Infotainment Personalization
- Fleet Management and Telematics
- By Sales Channel
- OEM-Fitted
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held 37.95% of revenue in 2025 and is set to expand 19.98% CAGR thanks to China's dual mandate for intelligent connected vehicles and strict data-localization rules that require on-device processing. Chinese OEMs now integrate domestic camera and fingerprint suppliers to meet quota requirements while avoiding cross-border data transfers. Japan pilots facial-verified autonomous shuttles to address driver shortages at Haneda Airport, while South Korea and Australia leverage high smartphone familiarity to accelerate consumer acceptance. India remains price-sensitive, but insurance incentives for anti-theft biometrics in urban centers spark pilot programs that could widen adoption.
North America and Europe converge on ISO and FIDO standards that enable cross-border rental fleet authentication. Europe's UNECE driver-monitoring law, effective from 2026, compresses program timelines and integrates biometric features into mainstream models. The United States lacks a federal rule; however, Illinois' consent law and California's privacy statute require technology providers to ship region-specific privacy controls, such as Lytx's Dynamic Adjust geofences. Canada and Mexico deploy biometrics in commercial trucking corridors to streamline customs and carrier audits, creating regional momentum for biometric in the automotive market.
The Middle East positions automotive biometrics as an extension of national digital-identity programs. The UAE's facial-ID rollout and Saudi Arabia's IDEMIA-SAMI partnership align vehicle access with civil-ID credentials, fostering early trials of palm-vein and iris modalities adapted to high-temperature environments. Africa remains constrained by high hardware costs and infrastructure gaps, yet South Africa and Nigeria are pursuing fleet biometrics to curb theft in logistics hubs. Hot-climate durability challenges persist, but ruggedized optical modules now pass extended heat-soak tests, slowly opening the door for broader uptake.
- Synaptics Incorporated
- Fingerprint Cards AB
- Aware, Inc.
- Cerence Inc.
- Continental Aktiengesellschaft
- Sensory, Inc.
- Shenzhen Goodix Technology Co., Ltd.
- B-Secur Ltd.
- EyeLock LLC
- Precise Biometrics AB
- Robert Bosch GmbH
- Valeo SA
- Gentex Corporation
- NEC Corporation
- IDEMIA Identity and Security France SAS
- IriTech, Inc.
- BioID GmbH
- Nexteer Automotive Group Limited
- Hella GmbH and Co. KGaA
- Stanley Black and Decker, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for contactless vehicle access and personalization
- 4.2.2 Stringent automotive safety and security regulations
- 4.2.3 Lower sensor costs and integration into vehicle electronics architectures
- 4.2.4 Insurance premium discounts linked to anti-theft biometrics
- 4.2.5 Expansion of in-car payment ecosystems requiring secure authentication
- 4.2.6 Escalating OEM focus on driver wellness monitoring via biometrics
- 4.3 Market Restraints
- 4.3.1 Lack of global standards and interoperability
- 4.3.2 High initial system cost in mass-market vehicle segments
- 4.3.3 Privacy and data security concerns
- 4.3.4 Environmental durability limitations of cabin-mounted optical sensors
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.2 By Biometric Modality
- 5.2.1 Fingerprint Recognition
- 5.2.2 Iris Recognition
- 5.2.3 Palm Recognition
- 5.2.4 Facial Recognition
- 5.2.5 Voice Recognition
- 5.2.6 Other Modalities
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Heavy Trucks
- 5.3.4 Buses and Coaches
- 5.3.5 Specialty Vehicles
- 5.4 By Application
- 5.4.1 Driver Identification and Access
- 5.4.2 Engine Start / Immobilizer
- 5.4.3 In-Car Payments
- 5.4.4 Driver Health and Drowsiness Monitoring
- 5.4.5 Infotainment Personalization
- 5.4.6 Fleet Management and Telematics
- 5.5 By Sales Channel
- 5.5.1 OEM-Fitted
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Synaptics Incorporated
- 6.4.2 Fingerprint Cards AB
- 6.4.3 Aware, Inc.
- 6.4.4 Cerence Inc.
- 6.4.5 Continental Aktiengesellschaft
- 6.4.6 Sensory, Inc.
- 6.4.7 Shenzhen Goodix Technology Co., Ltd.
- 6.4.8 B-Secur Ltd.
- 6.4.9 EyeLock LLC
- 6.4.10 Precise Biometrics AB
- 6.4.11 Robert Bosch GmbH
- 6.4.12 Valeo SA
- 6.4.13 Gentex Corporation
- 6.4.14 NEC Corporation
- 6.4.15 IDEMIA Identity and Security France SAS
- 6.4.16 IriTech, Inc.
- 6.4.17 BioID GmbH
- 6.4.18 Nexteer Automotive Group Limited
- 6.4.19 Hella GmbH and Co. KGaA
- 6.4.20 Stanley Black and Decker, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment