

|
시장보고서
상품코드
2123142
브로칭 머신 시장 : 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Broaching Machine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 브로칭 머신 시장 규모는 2025년 10억 8,000만 달러에서 2026년에는 11억 3,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 4.62%로 성장을 지속하여, 2031년까지 14억 2,000만 달러에 이를 것으로 예측됩니다.
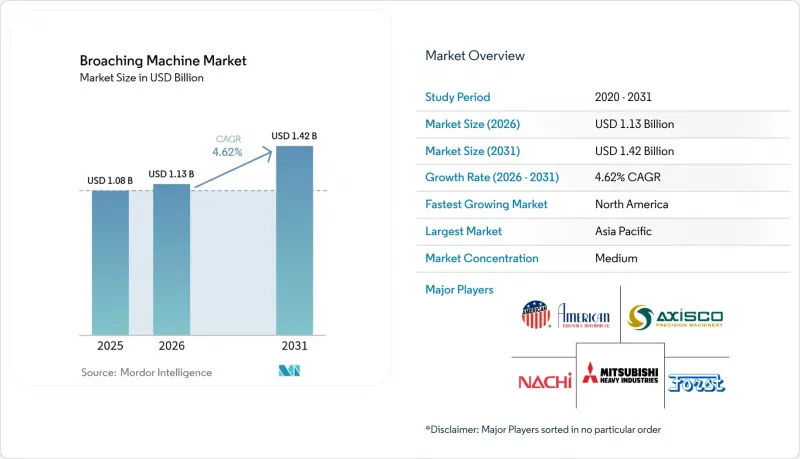
본 보고서는 제품 유형(수직형 브로칭 머신, 수평형 브로칭 머신, 표면 브로칭 머신, 기타), 작동 모드(수동, 반자동, 완전 자동), 최종 사용자 산업(자동차, 기타) 및 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 브로칭 머신 시장 동향 및 인사이트
고정밀 가공된 EV 파워트레인 부품의 급증(아시아)
현재, 전기자동차용 기어박스에는 ±0.0005인치의 톱니 형상 정밀도가 요구되고 있지만, 이러한 공차 수준은 대규모 밀링 가공으로는 실현하기 어렵습니다. 중국의 각 제조업체들은 정책 금융 및 세액 공제를 활용하여, 20시간 연속 가동 시 치수 변동을 2미크론 이하로 억제하는 완전 밀폐형 서보 구동 장치를 갖춘 수평형 브로칭 셀을 도입하고 있습니다. 통합형 e-액슬 설계에서는 여러 개의 기어, 스플라인, 키 홈이 단일 하우징에 통합되어 있어, 이를 통해 내면 절삭과 외면 절삭을 순차적으로 수행할 수 있는 유연한 브로칭 라인에 대한 수요가 증가하고 있습니다. 아시아에서 제조된 e-파워트레인의 북미 조립 공장으로의 수출 계약은 생산 능력 증대를 뒷받침하고 있으며, 양 지역에서의 브로칭 기계 시장 확대를 가속화하고 있습니다. 제품 수명 주기가 단축되는 가운데, 공급업체들은 셋업 시간을 40% 단축할 수 있는 퀵 체인지 가이드가 장착된 모듈식 브로치 헤드를 선호하고 있으며, 이로 인해 해당 기술의 도입이 더욱 정착되고 있습니다.
중국 2차 가공업체들의 적극적인 자동화 개조
베이징시의 설비 갱신 이니셔티브는 2027년까지 공작기계에 대한 투자를 실질 25% 증가시키는 것을 목표로 하고 있으며, 주요 공정의 CNC 보급률을 75%로 높이는 것을 목표로 하고 있습니다. 각 성의 보조금 프로그램은 중소기업이 CNC 브로치 라인에 투자한 비용의 최대 30%를 지원합니다. 자동화 개조에는 로봇 로더, 비전 기반 기준점 검사, 폐쇄 루프식 공구 마모 센서가 통합되어 있어 다품종 소량 생산 환경에서 무인 운전이 가능해졌습니다. 파일럿 플랜트에서는 단위 비용이 18% 절감되고 불량품이 32% 감소한 것으로 보고되었으며, 이에 따라 재주문이 증가하고 있습니다. 중국의 1차 공급업체들이 생산 패키지를 지역 파트너에게 이관함에 따라 아세안(ASEAN) 공급업체로의 기술 보급이 진행되고 있으며, 동남아시아 전역에서 브로칭 머신 시장 점유율이 확대되고 있습니다.
EU 및 미국 내 브로치 가공 숙련 공구 제작자 부족
제조업에서는 베테랑 기계 가공 기술자의 은퇴에 따라 2030년까지 210만 명의 인력 부족이 발생할 것으로 예측됩니다. 브로치 공구 설계에는 선각의 순서 지정이나 전단 영역의 열 관리에 관한 전문 지식이 필요하지만, 이러한 기술은 표준 CNC 교육 과정에서는 거의 다루어지지 않습니다. 핀란드 탐페레 지역에서는 기계 가공 기술자의 졸업률이 대체 수요의 절반 수준에 그치고 있는 것으로 보고되고 있으며, 독일과 미국에서도 유사한 인력 부족 현상이 나타나고 있습니다. 공장 측에서는 견습 제도 체계가 개선될 때까지 새로운 브로치 라인 도입을 주저하고 있습니다. 각 벤더사는 혼합 현실(MR) 시뮬레이터와 클라우드 기반 용도 지원을 통해 대응하고 있지만, 인력 부족은 여전히 생산량의 구조적 제약으로 남아 있어 브로칭 기계 시장의 성장 여지를 제한하고 있습니다.
부문 분석
수평형 모델은 2025년 매출의 44.72%를 차지하고 있으며, 이는 부품 길이가 1m를 초과하는 구동축 및 중장비 생산 라인에서 이 모델이 갖는 우위를 반영합니다. 주철 베이스 위에 구축된 최신 기종은 듀얼 서보 유압 구동 장치를 통합하여 채터링(진동)을 일으키지 않으면서 압출력을 300kN까지 높였습니다. 표면 브로칭 시스템은 출하 대수는 적지만, 항공우주 및 정형외과 분야에서의 용도에서 연삭으로는 실현할 수 없는 ‘파티트리’나 ‘골 플레이트’의 윤곽이 요구되기 때문에 6.46%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 표면 브로칭 가공기 시장 규모는 2026년 2억 2,370만 달러에서 2031년까지 3억 610만 달러로 확대될 것으로 예측됩니다. 로터리 테이블 어태치먼트는 다품종 생산을 수행하는 기어박스 공장으로의 적용을 확대되고 있습니다. 표준 CNC 가공 센터에 장착함으로써 ±0.0005인치의 정밀도를 유지하면서 밀링 가공 속도의 10배로 절삭이 가능합니다. 퀵 체인지 가이드 팩을 통해 3분 이내에 프로그램 전환이 가능해져, 200개 미만의 로트 크기에 최적입니다. 브로칭 머신 업계는 성형 및 슬롯 가공을 위해 헤드를 교체할 수 있는 하이브리드형(수직형·수평형 겸용) 프레임으로 계속 진화하고 있으며, 위치 조정 없이 3가지의 서로 다른 절삭 가공이 가능한 유연한 셀을 구현하여 설비 가동률을 더욱 높이고 있습니다.
지역별 분석
아시아태평양은 2027년까지 중국의 설비 투자 성장 목표 25%에 힘입어 2025년에도 세계 시장 점유율 55.22%를 유지했습니다. 중국의 각 OEM 기업들은 ‘중국 제조 2025’ 전략에 따라 브로치 라인을 스마트 제조 셀로 통합하고 있는 반면, 일본은 정밀 기계 수출을 위해 롱 스트로크 기계의 업그레이드를 추진하고 있습니다. 한국 및 아세안(ASEAN) 국가들은 반도체 및 자동차 공급망에 투자하고 있으며, 이는 수요의 점진적인 증가를 뒷받침하고 있습니다. 인도에서는 방위 오프셋 사업의 일환으로 기어트레인 공장에 대한 신규 수주가 예상되지만, 일본의 CNC 시스템에 대한 수입 관세가 비용 측면의 장벽으로 작용하고 있습니다.
북미에서는 미국의 기체 생산 대수가 회복되고 방위 프로그램이 확대됨에 따라, 2031년까지 연평균 성장률(CAGR) 6.94%로 가장 높은 성장세를 보일 것으로 예측됩니다. 리쇼어링 정책에 따라 부품 리드타임 단축을 위해 브로치 가공을 도입하는 소규모 기계 가공 공장에 보조금이 지원되고 있습니다. 캐나다는 프랫 앤 휘트니(Pratt & Whitney)사의 터보팬 오프셋 및 광산용 트럭 부품 수요의 혜택을 받고 있는 반면, 멕시코의 바히오 회랑(Bajo Corridor)에는 새로운 추진 시스템 및 항공우주용 기계 가공 센터가 입지해 있습니다. 북미의 브로칭 머신 시장 규모는 2026년 1억 8,570만 달러에서 2031년에는 2억 5,980만 달러로 확대될 것으로 추정됩니다.
유럽에서는 독일의 자동차 공급망이 수평 브로치 가공 능력을 갱신하고, 영국이 항공우주용 공구의 업그레이드를 가속화하고 있어 안정적인 성장을 유지하고 있습니다. 프랑스와 이탈리아에서는 에너지 효율 향상 세액 공제 제도에 따라 설비 갱신이 진행되고 있으며, 북유럽의 공장에서는 인력 부족을 보완하기 위해 자동화를 활용하고 있습니다. 숙련된 노동력 부족은 여전히 제약 요인으로 작용하고 있으며, 2024년에는 EU 전체에서 367개 직종에서 인력 부족이 발생할 것으로 지적되고 있습니다. 그럼에도 불구하고, 공급업체가 제공하는 관리형 서비스와 가상 교육이 병목 현상을 완화하고 있어, 브로칭 머신 시장의 완만하지만 예측 가능한 확장이 유지되고 있습니다.
기타 혜택:
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the broaching machine market size is expected to grow from USD 1.08 billion in 2025 to USD 1.13 billion in 2026 and is forecast to reach USD 1.42 billion by 2031 at 4.62% CAGR over 2026-2031.
This report is Segmented by Product Type (Vertical Broaching Machines, Horizontal Broaching Machines, Surface Broaching Machines, and Others), by Operation Mode (Manual, Semi-Automatic, and Fully Automatic), by End-User Industry (Automotive, and Others), and by Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Broaching Machine Market Trends and Insights
Surge in Precision-Machined EV Power-train Components (Asia)
Electric-vehicle gearboxes now require tooth accuracy of +-0.0005 inches, a tolerance level impractical for milling at scale. Chinese manufacturers leverage policy loans and tax credits to install horizontal broach cells with fully enclosed servo drives that hold dimensional drift below 2 microns for 20-hour runs. Integrated e-axle designs fold multiple gears, splines, and keyways into a single housing, pushing demand toward flexible broaching lines able to complete internal and surface cuts sequentially. Export contracts for Asia-manufactured e-power-trains into North American assembly plants reinforce capacity additions, amplifying the broaching machines market across both regions. As product life cycles compress, suppliers favor modular broach heads with quick-change guides that cut setup times by 40%, further entrenching technology adoption.
Aggressive Automation Retrofits in Chinese Tier-2 Job Shops
Beijing's equipment-upgrade initiative seeks 25% real growth in machine-tool investment by 2027 and targets 75% numerical-control penetration across key processes. Provincial grant programs reimburse up to 30% of CNC broach-line spend for small and mid-sized firms. Automation retrofits integrate robot loaders, vision-based datum checking, and closed-loop tool-wear sensors, enabling lights-out operation in high-mix environments. Pilot plants report 18% unit-cost savings and 32% scrap reduction, reinforcing repeat orders. Technology diffusion to ASEAN vendors follows, as Chinese tier-ones transfer production packages to regional partners, expanding the broaching machines market footprint across Southeast Asia.
Shortage of Broach-Skilled Toolmakers in EU & U.S.
The manufacturing sector forecasts 2.1 million unfilled roles by 2030 as senior machinists retire. Broach-tool design demands expertise in rake-angle sequencing and shear-zone heat management, skills rarely covered in standard CNC curricula. Finland's Tampere region reports machinist graduation rates at half replacement demand, mirroring shortages across Germany and the United States. Factories hesitate to install new broaching lines until apprenticeship pipelines improve. Vendors respond with mixed-reality simulators and cloud-based application support, yet the talent gap persists as a structural cap on throughput, limiting upside for the broaching machines market.
Other drivers and restraints analyzed in the detailed report include:
- Revival of Commercial Aerospace Build-Rates (North America & Europe)
- Defence Offset Mandates Fueling Local Gear-Hob & Broach Demand (Middle East)
- Volatile Tungsten-Carbide Pricing Disrupting Broach Tool Supply
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Horizontal models generated 44.72% of 2025 revenue, reflecting their dominance in drive-shaft and heavy-equipment lines where components exceed 1 m length. Built on cast-iron bases, modern units integrate dual-servo hydraulic drives that boost push forces to 300 kN without chatter. Surface broach systems, though smaller in unit shipments, post the fastest 6.46% CAGR as aerospace and orthopedic applications require fir-tree and bone-plate contours unachievable with grinding. The broaching machines market size for surface platforms is projected to climb from USD 223.7 million in 2026 to USD 306.1 million by 2031.Rotary-table attachments expand reach into high-mix gearbox shops. Mounted on standard CNC centers, they cut 10 times faster than milling while holding +-0.0005 inches. Quick-change guide packs enable programed switch-over in under 3 minutes, attractive for batch sizes below 200 pieces. The broaching machines industry continues to evolve toward hybrid vertical-horizontal frames that swap out heads for shaping or slotting, delivering a flexible cell capable of three distinct cutting processes without repositioning, thereby deepening equipment utilization.
Complete Report Scope:
- By Product Type
- Vertical Broaching Machines
- Horizontal Broaching Machines
- Surface Broaching Machines
- Others (Rotary, CNC Broaching, Hydraulic Broaching Machines)
- By Operation Mode
- Manual
- Semi-Automatic
- Fully Automatic
- By End-user Industry
- Automotive
- Fabrication & Industrial Machinery
- Aerospace & Defense
- Oil & Gas / Energy
- Construction Equipment
- Electronics & Precision Components
- Medical Devices
- Others (Agricultural Equipment, Firearms & Defense, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Peru
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN (Indonesia, Thailand, Philippines, Malaysia, Vietnam)
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- Kuwait
- Turkey
- Egypt
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific retained 55.22% global share in 2025, buoyed by China's 25% equipment-investment growth target through 2027. Chinese OEMs integrate broach lines into intelligent-manufacturing cells under the "Made in China 2025" strategy, while Japan upgrades long-stroke machines for precision machinery exports. South Korea and ASEAN nations invest in semiconductor and automotive supply chains, spurring incremental demand. India contributes fresh orders via defense-offset gear-train plants, though import tariffs on Japanese CNC systems raise cost hurdles.
North America is projected to post the fastest 6.94% CAGR to 2031 as US air-frame build-rates rebound and defense programs expand. Reshoring policies funnel grants toward small machine shops that add broaching to shorten component lead times. Canada benefits from Pratt & Whitney turbofan offsets and mining-truck component demand, while Mexico's Bajio corridor hosts new propulsion and aerospace machining centers. The broaching machines market size for North America is estimated to climb from USD 185.7 million in 2026 to USD 259.8 million in 2031.
Europe maintains stable growth as Germany's automotive supply chain refreshes horizontal broach capacity, and the United Kingdom accelerates aerospace tooling upgrades. France and Italy renew equipment under energy-efficiency tax credits, and Nordic plants leverage automation to offset labor scarcity. Skilled-worker shortages remain a limiting factor, with 367 occupations flagged as in deficit across the EU in 2024. Nonetheless, vendor managed-services and virtual training mitigate bottlenecks, sustaining a modest yet predictable expansion of the broaching machines market.
- Mitsubishi Heavy Industries Ltd.
- American Broach & Machine Co.
- Apex Broaching Systems
- Nachi-Fujikoshi Corp.
- Arthur Klink GmbH
- Axisco Precision Machinery Co. Ltd.
- Colonial Tool Group Inc.
- Forst Technologie GmbH & Co. KG
- Pioneer Broach Co.
- Steelmans Broaches Pvt Ltd.
- The Ohio Broach & Machine Co.
- Hoffmann Raumtechnik GmbH
- Accu-Cut Diamond Tool Co.
- General Broach Company
- Hexagon Manufacturing Intelligence
- Phoenix Broach Co.
- V W Broaching Service Inc.
- Fuji Seiko Ltd.
- Suzhou HXM Broaching Machine Ltd.
- Shanghai Machine Tool Works Co. Ltd.*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Precision-Machined EV Power-train Components (Asia)
- 4.2.2 Revival of Commercial Aerospace Build-Rates (North America & Europe)
- 4.2.3 Defence Offset Mandates Fueling Local Gear-Hob & Broach Demand (Middle East)
- 4.2.4 Aggressive Automation Retrofits in Chinese Tier-2 Job-Shops
- 4.2.5 OEM Shift from Hobbing to Rotary-Table Broaching for High-Mix Gearboxes
- 4.2.6 Rapid Tooling-as-a-Service Models for Short-Run Prototyping
- 4.3 Market Restraints
- 4.3.1 Shortage of Broach-Skilled Toolmakers in EU & U.S.
- 4.3.2 Volatile Tungsten-Carbide Pricing Disrupting Broach Tool Supply
- 4.3.3 Cap-Ex Freeze at Oil-field Service Firms (2024-25)
- 4.3.4 Import Tariffs on Japanese CNC Systems in India
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Global Manufacturing Sector Snapshot
- 4.9 Metal-working Industry Snapshot
- 4.10 Spotlight on Broach Tools
5 Market Size & Growth Forecasts (Value, In USD Billion)
- 5.1 By Product Type
- 5.1.1 Vertical Broaching Machines
- 5.1.2 Horizontal Broaching Machines
- 5.1.3 Surface Broaching Machines
- 5.1.4 Others (Rotary, CNC Broaching, Hydraulic Broaching Machines)
- 5.2 By Operation Mode
- 5.2.1 Manual
- 5.2.2 Semi-Automatic
- 5.2.3 Fully Automatic
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Fabrication & Industrial Machinery
- 5.3.3 Aerospace & Defense
- 5.3.4 Oil & Gas / Energy
- 5.3.5 Construction Equipment
- 5.3.6 Electronics & Precision Components
- 5.3.7 Medical Devices
- 5.3.8 Others (Agricultural Equipment, Firearms & Defense, etc.)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Peru
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.4.3.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.3.8 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 Australia
- 5.4.4.5 South Korea
- 5.4.4.6 ASEAN (Indonesia, Thailand, Philippines, Malaysia, Vietnam)
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 Kuwait
- 5.4.5.5 Turkey
- 5.4.5.6 Egypt
- 5.4.5.7 South Africa
- 5.4.5.8 Nigeria
- 5.4.5.9 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, JV, Tech-Licensing)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Mitsubishi Heavy Industries Ltd.
- 6.4.2 American Broach & Machine Co.
- 6.4.3 Apex Broaching Systems
- 6.4.4 Nachi-Fujikoshi Corp.
- 6.4.5 Arthur Klink GmbH
- 6.4.6 Axisco Precision Machinery Co. Ltd.
- 6.4.7 Colonial Tool Group Inc.
- 6.4.8 Forst Technologie GmbH & Co. KG
- 6.4.9 Pioneer Broach Co.
- 6.4.10 Steelmans Broaches Pvt Ltd.
- 6.4.11 The Ohio Broach & Machine Co.
- 6.4.12 Hoffmann Raumtechnik GmbH
- 6.4.13 Accu-Cut Diamond Tool Co.
- 6.4.14 General Broach Company
- 6.4.15 Hexagon Manufacturing Intelligence
- 6.4.16 Phoenix Broach Co.
- 6.4.17 V W Broaching Service Inc.
- 6.4.18 Fuji Seiko Ltd.
- 6.4.19 Suzhou HXM Broaching Machine Ltd.
- 6.4.20 Shanghai Machine Tool Works Co. Ltd.*
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet Need Assessment


