

|
시장보고서
상품코드
2123241
유전자 치료 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Gene Therapy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
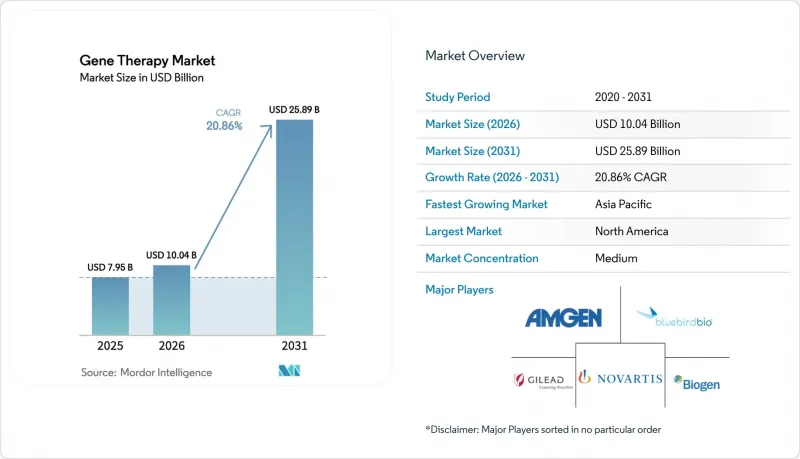
에 의하면, 유전자 치료 시장 규모는 2025년에 79억 5,000만 달러로 평가되었고, 2026년 100억 4,000만 달러에서 2031년까지 258억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 20.86%를 나타낼 전망입니다.
본 보고서는 치료법 유형별(생체 내, 생체등), 벡터 유형별(바이러스 벡터, 비바이러스 벡터), 적응증별(종양학, 희귀 유전성 질환 등), 투여 방법별(전신 투여, 국소 투여), 최종 사용자별(병원 및 전문 클리닉 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 유전자 치료 시장 동향 및 인사이트
원샷형 근치 요법의 승인 급증
규제 당국은 2024-2025년 심사 절차를 가속화하여, 위스콧-올드리치 증후군 치료제 ‘와스키라(Waskyra)’, 척수성 근위축증 치료제 ‘잇비스마(Itvisma)’, 겸상적혈구빈혈증 치료제 ‘카스게비(Casgevy)’ 등의 치료제를 우선 심사 절차를 통해 승인했습니다. 이러한 결정의 근거가 된 임상 데이터는 지속적인 유효성을 보여주었으며, ‘Casgevy’의 경우 12개월 동안 환자의 93.5%가 발작을 보이지 않았고, ‘Beqvez’의 경우 제9인자 활성이 40% 이상 유지되어 B형 혈우병의 예방적 치료가 불필요해졌습니다. 보험사들은 단 한 번의 치료로 수십 년에 걸친 만성기 관리 비용을 상쇄할 수 있음을 인식하고 있으며, 이로 인해 예산 모델의 재검토가 촉진되고 있습니다. 일본의 ‘사키가케’ 제도가 유전자 치료로 적용 범위를 확대한 것은 아시아태평양 내 광범위한 협력을 부각시키고 있으며, 전 세계가 근치적 치료 패러다임으로 전환하는 데 박차를 가하고 있습니다.
극히 희귀한 질환에 대한 보험 급여 확대
현재 미국 내 민간 계약의 약 40%는 성과 연계형 모델에 따라 운영되고 있으며, CMS(미국 의료보험의료서비스센터)의 ‘세포 및 유전자 치료 접근 모델’은 35개 메디케이드 프로그램을 포괄하며, 제약 기업과 재정적 위험을 분담하고 있습니다. 유럽은 여전히 대응이 제각각이지만, 분할 지급 시도가 진행 중이며, 프랑스의 HAS(고등보건위원회)는 졸겐스마의 210만 달러 비용을 5년에 걸쳐 분할 지급하고 있습니다. 미국 의회예산처(CBO)의 예측에 따르면, 2028년까지 겸상적혈구빈혈 치료제만으로 연간 18억 달러의 메디케이드 지출이 발생할 가능성이 있으며, 이에 따라 각 주 의회는 공동 구매 방안 마련을 추진하고 있습니다. ‘졸겐스마’의 실제 데이터를 기반으로 한 레지스트리 조사 결과, 치료를 받은 소아의 95%가 5년 후 추적 조사 시점에서 운동 발달의 이정표를 유지하고 있는 것으로 나타나, 성과 연동형 보상 제도의 가치가 입증되었습니다.
높은 원가와 6자리 수의 가격에 대한 반발
바이러스 벡터의 배치 제조 비용은 50만-200만 달러에 달하고, 렌멜디(Lenmeldy)의 425만 달러와 같은 정가를 끌어올리고 있으며,미국 상원 재정위원회 청문회나 NICE가 정한 ‘10만 파운드/QALY’ 기준치를 하회한다는 이유로 승인이 기각되는 사태를 초래하고 있습니다. 1회 제조 캠페인당 수율이 30%에서 70%까지 편차가 있어, 과잉 생산이나 평가손실 계상이 불가피한 상황입니다. Resilience사와 후지필름 디오신사(Fujifilm Diosynsa)가 진행 중인 연속 제조 파일럿 프로젝트는 50%의 비용 절감을 약속하고 있지만, 2027년까지는 실질적인 상업적 규모에 도달하지 못할 전망입니다. 블루버드사가 상환 승인 실패에 따라 2024년에 EU 시장에서 ‘Zynteglo’를 철수시킨 사례는 HTA(의료기술평가) 기관이 가격 승인에 소극적인 태도를 보임으로써 발생하는 존립을 위협하는 위험을 여실히 보여주고 있습니다.
부문 분석
2025년 유전자 치료 시장 규모에서 생체 내(in vivo) 접근법이 매출의 67.31%를 차지했으며, 간 및 전신 응용 분야에서 그 우위를 반영하고 있습니다. 생체외(ex vivo) 요법은 나머지 부분을 차지하고 있지만, 자가 유래의 병목 현상을 피하는 CRISPR을 활용한 동종 CAR-T의 설계에 힘입어 연평균 성장률(CAGR) 21.97%로 시장 평균을 상회하는 성장이 예상됩니다. Allogene사와 CRISPR Therapeutics사는 2024년에 2상 임상시험을 진행하여 14일이라는 신속한 ‘정맥에서 정맥으로(vein-to-vein)’ 워크플로우를 입증했습니다. FDA의 CMC 지침안에서는 배치 시험 및 기증자 선별 기준이 명확해져 규제상의 모호성이 해소되었습니다.
이 기술의 보급은 비용 효율적인 현장(point-of-care) 제조에 달려 있습니다. 론자와 밀테니 바이오테크는 2024년, 1회분당 비용을 40% 절감하는 이동식 클린룸의 시범 운영을 실시하여 병원 시설을 마이크로 팩토리로 자리매김했습니다. 생체 내(in vivo) 프로그램에서는 여전히 면역원성 문제에 직면해 있으며, 후보 물질의 최대 50%에서 중화 항체가 확인됨에 따라 변형 캡시드 개발이 진행되고 있습니다. uniQure사의 AMT-130을 필두로 한 신경퇴행성 질환 분야에서는 체외(ex vivo) 방법이 실용적이지 않은 경우에도 유망한 결과가 나타나고 있어, 치료법의 다양성이 유지되고 있습니다.
2025년 매출의 74.83%는 바이러스 기반 플랫폼이 차지한 것으로 평가되었으며, 그 중심에는 AAV의 간세포 친화성과 혈액 질환에 대한 LV의 유전자 삽입이 자리 잡고 있습니다. 비바이러스성 벡터는 연평균 성장률(CAGR) 23.41%로 확대될 것으로 예상되며, Moderna사와 BioNTech사의 전임상 모델에서 40%-60%의 편집률을 달성한 최적화된 지질 나노입자를 통해 그 격차를 좁힐 것으로 기대됩니다. MaxCyte사의 전기천공 기술은 50건 이상의 임상시험을 뒷받침하고 있으며, 생체 외(ex vivo) 편집에 적합한 일시적 발현을 실현하고 있습니다.
바이러스 기반 벡터 부문에서는 개량된 AAV-PHP.B 캡시드가 파킨슨병을 대상으로 한 첫 번째 인간 임상시험에 진입했습니다. 이는 중추신경계(CNS) 전달을 위한 차세대 트로피즘을 부각시키는 사례입니다. Touchlight사의 효소적 DNA는 세균 유래 오염 물질을 피할 수 있는 플라스미드의 대안으로 경쟁하고 있어, 비바이러스성 선택지를 확대되고 있습니다. FDA의 비바이러스성 지침은 품질 요건을 표준화하고, 벡터 범주가 아닌 비가역적 편집 위험을 기준으로 규제를 통일했습니다.
지역별 분석
북미는 45건의 새로운 RMAT 지정과 메디케이드 장벽을 완화하는 CMS 접근 모델에 힘입어 2025년 매출의 41.36%를 유지했습니다. 론자, 카탈렌트, 레질리언스가 구축한 생산 능력은 바이오리액터 기준으로 총 120만 리터에 달하며, 이 지역 공급 우위를 확고히 했습니다. 성과 연계형 계약은 현재 미국 치료법의 40%를 차지하고 있으며, Lyfgenia사가 1억 명의 피보험자를 대상으로 계약을 체결한 것이 그 예입니다. 캐나다에서는 주 차원의 환급 협상이 장기화되고 있어 2024년 승인 건수는 단 2건에 그쳤습니다.
연평균 성장률(CAGR) 28.78%를 나타낼 것으로 예측되는 아시아태평양은 중국 국가약품감독관리국(NMPA)의 ‘록타비안’ 및 ‘예스칼타’ 승인, 그리고 200건 이상의 진행 중인 임상시험에 힘입어 성장하고 있습니다. WuXi AppTec의 플라스미드 제조 시설과 삼성의 AAV 제조 공장은 전 세계 제조거점의 다양화에 기여하고 있습니다. 일본의 PMDA는 ‘사키가케’ 패스트트랙 제도를 유전자 치료 분야로도 확대했으며, 인도는 미국 가격의 10분의 1 수준에서 최초의 CAR-T 요법을 승인함으로써 비용 측면에서의 혁신을 보여주었습니다. 호주는 ‘카스게비’를 승인했으나, 보험 급여 승인 지연에 직면해 있습니다.
유럽에서는 HTA(의료기술평가) 시스템의 분절화라는 과제에 직면해 있습니다. 블루버드사의 ‘Zynteglo’가 보험 급여 승인을 얻지 못해 시장에서 철수한 사례는 EMA(유럽의약품청)의 승인에 수반되는 상업적 위험을 여실히 보여주고 있습니다. 독일 IQWiG의 헴제닉스에 대한 긍정적 평가나 프랑스의 ‘졸젠스마’ 분할 납부 제도는 고립된 성공 사례에 불과합니다. EUnetHTA가 2025년에 실시할 공동 평가는 증거의 조화를 목표로 하고 있지만, 가격 결정권은 여전히 각국의 보험자가 장악하고 있습니다. 중동 및 아프리카 및 남미는 여전히 발전 단계에 있지만 규제 체계를 정비해 나가고 있으며, UAE와 브라질에서는 특별 사용 허가나 공립병원에서의 사용을 목적으로 특정 치료법이 승인되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the gene therapy market size was valued at USD 7.95 billion in 2025 and is estimated to grow from USD 10.04 billion in 2026 to reach USD 25.89 billion by 2031, at a CAGR of 20.86% during the forecast period (2026-2031).
This report is Segmented by Therapy Type (In Vivo, Ex Vivo), Vector Type (Viral Vectors, Non-Viral Vectors), Indication (Oncology, Rare Genetic Disorders, and More), Delivery Method (Systemic, Localised), End User (Hospitals & Specialty Clinics, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Gene Therapy Market Trends and Insights
Surge in Approvals of One-Shot Curative Therapies
Regulators accelerated timelines in 2024-2025, clearing therapies such as Waskyra for Wiskott-Aldrich syndrome, Itvisma for spinal muscular atrophy, and Casgevy for sickle-cell disease under priority pathways. Clinical datasets underpinning these decisions demonstrate durable efficacy, with Casgevy keeping 93.5% of patients crisis-free over 12 months and Beqvez maintaining greater than 40% factor IX activity, thereby eliminating the need for hemophilia B prophylaxis. Payers acknowledge that one-time interventions can offset decades of chronic-care costs, triggering recalibrated budget models. Japan's Sakigake pathway extension to gene therapy underscores the broader alignment in the Asia-Pacific region, reinforcing the global shift toward curative paradigms.
Expanding Reimbursement for Ultra-Rare Disorders
Outcomes-based models now govern roughly 40% of U.S. commercial contracts, and CMS's Cell and Gene Therapy Access Model covers 35 Medicaid programs, sharing financial risk with manufacturers. Europe remains fragmented but is experimenting with installment payments, as France's HAS spreads Zolgensma's USD 2.1 million cost over five years. U.S. forecasts from the Congressional Budget Office indicate that sickle-cell therapies alone could generate USD 1.8 billion in annual Medicaid expenditures by 2028, prompting legislatures to develop pooled-purchase solutions. Registry data from real-world Zolgensma use indicate that 95% of treated children retain motor milestones at a five-year follow-up, reinforcing the value of pay-for-performance schemes.
High COGS and Six-Figure Price Backlash
Viral-vector batches cost USD 500,000-2 million, driving list prices such as Lenmeldy's USD 4.25 million, provoking U.S. Senate Finance hearings and NICE rejections under GBP 100,000/QALY thresholds. Yield variability ranging from 30% to 70% per campaign forces overproduction and write-offs. Continuous-manufacturing pilots by Resilience and Fujifilm Diosynth promise a 50% cost reduction but will not reach commercial scale meaningfully before 2027. Bluebird's 2024 withdrawal of Zynteglo from the EU, following reimbursement failures, illustrates the existential risk posed by HTA bodies' reluctance to accept prices.
Other drivers and restraints analyzed in the detailed report include:
- Manufacturing Platform Standardization (AAV & LV)
- Growing Venture & SPAC Funding Pipelines
- Complex Long-Term Safety Monitoring Mandates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The gene therapy market size for in vivo approaches accounted for 67.31% of the revenue in 2025, reflecting its dominance in liver and systemic applications. Ex vivo therapies accounted for the remainder but are projected to outpace the market at a 21.97% CAGR, fueled by CRISPR-enabled allogeneic CAR-T designs that bypass autologous bottlenecks. Allogene and CRISPR Therapeutics advanced Phase 2 trials in 2024, demonstrating rapid 14-day vein-to-vein workflows. FDA draft CMC guidance clarified batch testing and donor-screening criteria, reducing regulatory ambiguity.
Adoption hinges on cost-effective point-of-care manufacturing. Lonza and Miltenyi Biotec piloted mobile clean rooms in 2024 that slash per-dose costs by 40%, positioning hospital sites as micro-factories. In vivo programs still encounter immunogenicity; up to 50% of candidates possess neutralizing antibodies, prompting the development of engineered capsids. Neurodegenerative disorders, led by uniQure's AMT-130, show promise where ex vivo is impractical, keeping therapeutic diversity high.
Viral platforms generated 74.83% of 2025 revenue, anchored by AAV's hepatocyte tropism and LV's integration for hematologic disorders. Non-viral vectors are expected to expand at a 23.41% CAGR, narrowing the gap through optimized lipid nanoparticles that delivered 40%-60% editing rates in Moderna and BioNTech preclinical models. MaxCyte's electroporation supports 50+ clinical trials, offering transient expression suitable for ex vivo editing.
Within viral categories, engineered AAV-PHP.B capsids entered first-in-human studies for Parkinson's disease, highlighting next-generation tropism for CNS delivery. Touchlight's enzymatic DNA competes as a plasmid alternative that avoids bacterial contaminants, broadening non-viral options. The FDA non-viral guidance standardized quality expectations, aligning oversight with irreversible editing risk rather than vector category.
Complete Report Scope:
- By Therapy Type
- In Vivo
- Ex Vivo
- By Vector Type
- Viral Vectors
- Adeno-Associated Virus
- Lentivirus
- Adenovirus
- Retrovirus & Y-Retrovirus
- Other Viral
- Non-viral Vectors
- Viral Vectors
- By Indication
- Oncology
- Rare Genetic Disorders
- Ophthalmology
- Hematology
- Neurology
- Cardiovascular & Others
- By Delivery Method
- Systemic Administration
- Localised Administration
- By End User
- Hospitals & Specialty Clinics
- Academic & Research Institutes
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America maintained 41.36% of 2025 revenue, supported by 45 new RMAT designations and the CMS Access Model easing Medicaid barriers. Capacity built by Lonza, Catalent, and Resilience totaled 1.2 million liters of bioreactors, cementing the region's supply dominance. Outcomes-based contracts now cover 40% of U.S. therapies, as exemplified by Lyfgenia's coverage for 100 million lives. Canada trails with only two approvals in 2024, due to protracted provincial reimbursement negotiations.
The Asia-Pacific region, projected to grow at a 28.78% CAGR, is driven by China's NMPA approvals of Roctavian and Yescarta, as well as over 200 active clinical trials. WuXi AppTec's plasmid facility and Samsung's AAV plant diversify global manufacturing. Japan's PMDA extended Sakigake's fast-track to gene therapy, and India green-lit its first CAR-T at one-tenth the U.S. price, showcasing cost innovation. Australia approved Casgevy but faces delays in reimbursement.
Europe grapples with fragmented HTA systems. Bluebird's Zynteglo exit following reimbursement failures exemplifies the commercial risk associated with EMA approval. Germany's IQWiG positive Hemgenix assessment and France's installment payments for Zolgensma are isolated wins. EUnetHTA's 2025 joint assessments aim to harmonize evidence, yet national payers still control pricing. The Middle East & Africa, as well as South America, remain nascent but are developing regulatory frameworks, with the UAE and Brazil approving select therapies for compassionate or public hospital use.
- Amgen
- Beam Therapeutics
- bluebird bio Inc.
- Bristol-Myers Squibb
- Biogen
- CRISPR Therapeutic
- Editas Medicine
- Freeline Therapeutics
- Gilead Sciences
- Intellia Therapeutics
- LogicBio Therapeutics
- MeiraGTx
- Mustang Bio
- Novartis
- Orchard Therapeutics
- Passage Bio
- Pfizer
- Regenxbio
- Sangamo Therapeutics
- Sarepta Therapeutics
- Spark Therapeutics
- Takeda Pharmaceuticals
- uniQure N.V.
- ViGeneron
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Approvals of One-Shot Curative Therapies
- 4.2.2 Expanding Reimbursement for Ultra-Rare Disorders
- 4.2.3 Manufacturing Platform Standardisation (AAV & LV)
- 4.2.4 Growing Venture & SPAC Funding Pipelines
- 4.2.5 CRISPR-Based in Vivo Editing Breakthroughs
- 4.2.6 Growing Inclusion of Rare-Disease Gene Therapies
- 4.3 Market Restraints
- 4.3.1 High COGS And Six-Figure Price Backlash
- 4.3.2 Complex Long-Term Safety Monitoring Mandates
- 4.3.3 Global Viral-Vector Capacity Bottlenecks
- 4.3.4 Emerging Patent Thickets on Gene-Editing Payloads
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Therapy Type
- 5.1.1 In Vivo
- 5.1.2 Ex Vivo
- 5.2 By Vector Type
- 5.2.1 Viral Vectors
- 5.2.1.1 Adeno-Associated Virus
- 5.2.1.2 Lentivirus
- 5.2.1.3 Adenovirus
- 5.2.1.4 Retrovirus & Y-Retrovirus
- 5.2.1.5 Other Viral
- 5.2.2 Non-viral Vectors
- 5.2.1 Viral Vectors
- 5.3 By Indication
- 5.3.1 Oncology
- 5.3.2 Rare Genetic Disorders
- 5.3.3 Ophthalmology
- 5.3.4 Hematology
- 5.3.5 Neurology
- 5.3.6 Cardiovascular & Others
- 5.4 By Delivery Method
- 5.4.1 Systemic Administration
- 5.4.2 Localised Administration
- 5.5 By End User
- 5.5.1 Hospitals & Specialty Clinics
- 5.5.2 Academic & Research Institutes
- 5.5.3 Other End Users
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Amgen Inc.
- 6.3.2 Beam Therapeutics
- 6.3.3 bluebird bio Inc.
- 6.3.4 Bristol Myers Squibb
- 6.3.5 Biogen Inc.
- 6.3.6 CRISPR Therapeutics
- 6.3.7 Editas Medicine
- 6.3.8 Freeline Therapeutics
- 6.3.9 Gilead Sciences Inc.
- 6.3.10 Intellia Therapeutics
- 6.3.11 LogicBio Therapeutics
- 6.3.12 MeiraGTx
- 6.3.13 Mustang Bio
- 6.3.14 Novartis AG
- 6.3.15 Orchard Therapeutics
- 6.3.16 Passage Bio
- 6.3.17 Pfizer Inc.
- 6.3.18 Regenxbio
- 6.3.19 Sangamo Therapeutics
- 6.3.20 Sarepta Therapeutics
- 6.3.21 Spark Therapeutics
- 6.3.22 Takeda Pharmaceutical
- 6.3.23 uniQure N.V.
- 6.3.24 ViGeneron
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


