

|
시장보고서
상품코드
2123246
혈우병 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hemophilia - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
혈우병 시장 규모는 2026년에 153억 5,000만 달러로 추정되고 있어 2025년 145억 6,000만 달러에서 성장하여 2031년에는 199억 7,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.4%로 성장할 것으로 전망됩니다.
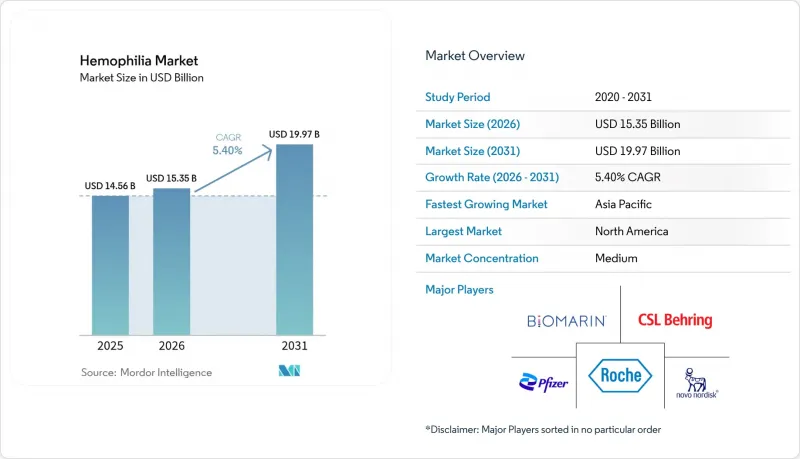
본 보고서는 질환 유형(A형 혈우병, B형 혈우병 등), 치료법(보충 요법, 유전자 치료 등), 제품 유형(재조합 응고 인자 농축 제제 등), 치료 환경(예방 요법 및 온디맨드 요법), 그리고 지역(북미, 유럽,아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 혈우병 시장 동향 및 인사이트
진단된 환자 수 증가 및 평균 수명 향상
신흥국의 검사 역량 지속적 확대에 힘입어 혈우병 사례 수가 급증하여, 2025년에는 전 세계 진단 환자 수가 약 110만 명에 달할 것으로 전망됩니다. 중국에서는 2008년부터 2018년 사이에 평균 진단까지 걸리는 기간이 13.3년에서 0.4년으로 단축되어 개선 속도가 나타나고 있습니다. 평균 수명의 연장은 예방 요법의 보급 확대와 밀접한 관련이 있습니다. CDC의 감시 자료에 따르면, 혈우병 치료 센터에서 관리받는 환자의 사망률은 감소 추세를 보이고 있습니다. 체계적인 치료 네트워크를 구축한 국가들에서는 현재 거의 일반인과 비슷한 평균 수명이 실현되고 있으며, 이로 인해 첨단 치료법에 대한 안정적인 수요가 뒷받침되고 있습니다.
반감기 연장(EHL) 재조합 응고 인자의 출시
ALTUVIIIO는 주 1회 투여가 가능하며, 표준 응고 인자에 비해 점적 횟수를 절반으로 줄여줍니다. 임상 데이터에 따르면, 예방 요법 중 출혈이 전혀 발생하지 않은 사용자는 65%에 달하며, 10년간의 독점권을 수반하는 유럽 내 승인은 규제 측면에서의 신뢰성을 높이고 있습니다. EHL 응고 인자는 기존 제품과 동등한 수술 안전성을 유지하면서 콜드체인의 부담을 줄이고, 관절 예후를 개선하며, 복용 순응도를 높입니다.
고액의 치료비와 지급 기관의 예산 압박
미국의 연간 치료비는 환자 1인당 21만 3,874달러에서 86만 9,940달러에 달하고, 예산을 압박하고 있습니다. 유전자 치료의 경우 정가가 350만 달러에 육박함에 따라 엄격한 감시의 대상이 되고 있습니다. 유럽에서는 혈장 공급 부족이 물가 상승 압력을 더욱 가중시키고 있는 반면, 중국의 도시 지역 환자들은 가처분 소득의 30%를 초과하는 본인 부담 비용을 감당하고 있어, 이로 인해 예방 요법의 보급이 제한되고 있습니다. 브라질에서는 환자 1인당 연간 지출이 평균 45만 831달러이며, 2025년에는 전국적으로 총 51억 9,000만 달러에 달할 것으로 전망됩니다.
부문 분석
2025년, A형 혈우병은 남성 출생아 5,000명당 약 1명의 비율이라는 높은 유병률로 인해 혈우병 시장 점유율의 74.65%를 차지했습니다. B형 혈우병은 제9인자의 반감기가 길어 유전자 치료의 효과가 지속되기 쉬우며, HEMGENIX를 통해 4년 만에 환자의 94%가 예방 요법을 중단할 수 있었기 때문에 더욱 빠르게 성장하고 있습니다. 혈우병 업계에서는 두 아형에 걸친 미충족 의료 수요를 해결하는 비인자 제제 분야에서도 상호 보완적인 진전이 나타나고 있습니다.
혈우병 A의 성장세는 ALTUVIIIO와 같은 EHL 인자나 에미시주맙과 같은 비인자 분자에 기인하며, 이들이 결합되어 복약 순응도와 출혈 조절을 개선하고 있습니다. 혈우병 B 분야의 병행된 획기적인 발전으로, 유전자 치료의 성공 사례가 투자를 촉진하는 한편, 확립된 응고 인자 농축 제제가 치료의 유연성을 유지함으로써 균형 잡힌 파이프라인이 형성되고 있습니다. 혈우병 C 및 기타 희귀 응고 인자 결핍증은 규모는 작지만 임상적으로 중요한 부문을 차지하고 있으며, 일본의 제VII인자 결핍증 연구에서는 재조합 활성화 제VII인자를 이용한 효과적인 관리가 입증되어, 45.7%가‘매우 양호’, 33.6%가 ‘양호’한 지혈 반응을 보였습니다. 전반적으로, 기존 치료법과 첨단 치료법의 융합을 통해 광범위한 혈우병 시장 내에서 역동적인 경쟁이 유지되고 있습니다.
2025년에는 보충 요법이 혈우병 시장 규모의 63.02%를 차지하며, 그 시장 규모는 91억 8,000만 달러에 달하고, 일상적인 치료에서 그 확고한 역할을 반영하고 있습니다. 그러나 젊은 층에게 매력적인 ‘1회 투여로 치료 효과를 기대할 수 있다’는 가능성에 힘입어, 유전자 치료는 2031년까지 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 의사들이 억제제 환자의 치료법을 우회제에서 편의성이 높은 피하 투여 요법으로 전환함에 따라, 비인자성 예방 요법은 급속히 확대되고 있습니다.
보충 요법은 투여 빈도를 줄여주는 EHL(경정맥적 하이퍼피브라틴 요법) 혁신의 혜택을 받고 있으며, 유전자 치료가 확대되는 가운데서도 시장 점유율을 유지하고 있습니다. 한편, 보험사는 평생 비용의 상쇄 효과를 신중하게 검토하고 있으며, 유전자 치료는 연간 60만 달러가 넘는 예방 요법 비용을 상쇄할 가능성이 있으므로, 내구성에 대한 신뢰가 확립된다면 도입을 위한 강력한 인센티브가 될 것입니다. 비인자 제제는 선택지를 더욱 다양화하여, 각 치료법이 서로 다른 임상적 요구를 충족시키는 다중 트랙 접근 방식을 강화하고 있습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 47.12%를 차지하며, 연방 정부의 자금을 지원받는 146개의 혈우병 치료 센터가 총 5만 2,000명 이상의 환자를 관리하고 있는 것이 그 기반이 되고 있습니다. 견고한 환급 체계에는 유전자 치료에 대한 메디케어 적용 및 의약품 조달을 지원하는 340B 프로그램이 포함됩니다. CDC의 ‘Community Counts’ 등록부 데이터는 13만 4,000명의 환자를 대상으로 한 모범 사례 지침 수립에 활용되고 있으며, 이를 통해 근거 기반의 신약 도입이 가속화되고 있습니다. 자금은 확보된 상태이지만, CSL Behring사는 HEMGENIX의 보급이 예상보다 더디다고 지적하고 있으며, 이는 고비용의 근치적 치료에 수반되는 미묘한 판단 과정을 여실히 보여주고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2026년부터 2031년까지 연평균 성장률(CAGR) 6.55%가 예상됩니다. 중국에서는 보험 적용 범위 확대에 따라 진단까지의 지연 기간이 0.4년으로 단축되었으며, 연간 응고 인자 소비량이 증가했습니다. 일본의 ‘HIKOBOSHI’ 연구에 따르면, 2005년부터 2019년까지 월간 제VIII인자 투여량은 5배 증가했으며, 이는 적극적인 예방 요법의 추세를 반영하고 있습니다. 그럼에도 불구하고, 중국의 A형 혈우병 환자 중 예방 요법을 받고 있는 비율은 고작 3.2%에 그치고 있어 경제적 격차가 두드러지고 있습니다. 지역별 워킹그룹은 치료 기준의 통일을 도모하기 위해 전국적인 등록 제도 및 연계 치료 프로그램의 도입을 추진하고 있습니다.
유럽은 성숙한 인프라와 선진적인 보험 적용 제도를 갖추고 있지만, 혈장 부족 문제에 직면해 있습니다. 이 지역은 혈장의 약 40%를 미국에서 수입하고 있으며, 공급을 안정화하기 위해 200만 명의 신규 기증자를 모집하고 있습니다. 중동 및 아프리카 및 남미에서는 의료 접근성 측면에서 심각한 부족에 직면해 있습니다. 아프리카에서는 환자의 고작 8%만이 진단을 받았으며, 전문 인력 부족도 계속되고 있습니다. 응고 인자 소비량은 여전히 치료 기준치를 크게 밑돌고 있어 미충족 수요가 지속되고 있습니다. 그러나 인프라와 보험 적용이 개선된다면, 이 지역들은 향후 성장 기회가 될 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, hemophilia market size in 2026 is estimated at USD 15.35 billion, growing from 2025 value of USD 14.56 billion with 2031 projections showing USD 19.97 billion, growing at 5.4% CAGR over 2026-2031.
This report is Segmented by Disease Type (Hemophilia A, Hemophilia B, and More), Therapy (Replacement Therapy, Gene Therapy, and More), Product Type (Recombinant Coagulation Factor Concentrates and More), Treatment Setting (Prophylaxis and On-Demand), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Hemophilia Market Trends and Insights
Rising Diagnosed Prevalence & Life-Expectancy Improvements
Identification of hemophilia cases has risen sharply, taking the global diagnosed population to roughly 1.1 million in 2025 after sustained expansion of testing capacity in emerging economies. China reduced its average diagnosis lag from 13.3 years to 0.4 years between 2008 and 2018, illustrating the pace of improvement. Higher life expectancy is tied to broader prophylaxis adoption; CDC surveillance shows mortality declines in patients managed through hemophilia treatment centers. Countries with structured care networks now deliver near-normal life expectancy, reinforcing steady demand for advanced therapies.
Launch of Extended Half-Life (EHL) Recombinant Factors
ALTUVIIIO enables once-weekly dosing, reducing infusion counts by half compared with standard factors. Clinical data show 65% of users experience zero bleeds during prophylaxis, and European approval with 10-year exclusivity adds regulatory confidence. EHL factors cut cold-chain burdens, improve joint outcomes and bolster adherence, while maintaining surgical safety comparable to legacy products.
High Treatment Cost & Payer Budget Pressure
Annual US costs range from USD 213,874 to USD 869,940 per patient, straining budgets. Gene therapies intensify scrutiny with list prices near USD 3.5 million. Plasma-supply shortages add further inflationary pressure in Europe, while Chinese urban patients bear out-of-pocket costs topping 30% of disposable income, limiting prophylaxis uptake. Brazil's annual spend averages USD 450,831 per patient, totaling USD 5.19 billion nationally in 2025.
Other drivers and restraints analyzed in the detailed report include:
- Commercial Availability of One-Time Gene Therapies
- Favorable Reimbursement & National Hemophilia Programs
- Care-Access Gaps in Low-/Middle-Income Countries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hemophilia A contributed 74.65% of hemophilia market share in 2025 due to its higher prevalence of roughly 1 in 5,000 male births. Hemophilia B is growing faster because factor IX's longer half-life supports durable gene-therapy efficacy; HEMGENIX enabled 94% of patients to stop prophylaxis over four years. The hemophilia industry sees complementary progress in non-factor agents that address unmet needs across both subtypes.
Momentum in hemophilia A derives from EHL factors such as ALTUVIIIO and non-factor molecules like emicizumab, which together improve adherence and bleed control. Parallel breakthroughs in hemophilia B create a balanced pipeline where gene-therapy success stories stimulate investment while established factor concentrates preserve treatment flexibility. Hemophilia C and other rare factor deficiencies represent a smaller but clinically significant segment, with factor VII deficiency studies in Japan demonstrating effective management with recombinant activated factor VII, achieving 45.7% excellent and 33.6% effective hemostatic responses. Overall, the convergence of traditional and advanced modalities maintains dynamic competition within the broader hemophilia market.
Replacement therapy retained 63.02% of the hemophilia market size in 2025, valued at USD 9.18 billion, reflecting its entrenched role in daily care. Yet gene therapy posts the highest CAGR to 2031, propelled by single-infusion curative potential that appeals to younger cohorts. Non-factor prophylactics expand quickly as physicians shift inhibitor patients from bypassing agents to convenient subcutaneous regimens.
Replacement therapy benefits from EHL innovations that lower infusion frequency, protecting share even as gene therapy scales. Conversely, payers weigh lifetime cost offsets-gene therapy could negate annual prophylaxis bills that surpass USD 600,000, creating strong incentives for adoption once durability comfort solidifies. Non-factor molecules further diversify choices, reinforcing a multitrack approach where each modality meets distinct clinical needs
Complete Report Scope:
- By Disease Type
- Hemophilia A
- Hemophilia B
- Hemophilia C & Others
- By Therapy
- Replacement Therapy
- Gene Therapy
- Non-Factor Therapy
- By Product Type
- Recombinant Coagulation Factor Concentrates
- Plasma-Derived Factor Concentrates
- Bypassing & Ancillary Agents
- By Treatment Setting
- Prophylaxis
- On-Demand
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 47.12% of global revenue in 2025, anchored by 146 federally funded hemophilia treatment centers that collectively manage more than 52,000 patients. Robust reimbursement frameworks include Medicare coverage for gene therapies and the 340B program that subsidizes drug acquisition. Data from the CDC's Community Counts registry informs best-practice guidelines across 134,000 individuals, accelerating evidence-based adoption of novel agents. Despite available funding, CSL Behring notes slower than anticipated uptake of HEMGENIX, illustrating the nuanced decision pathways that accompany high-cost curative therapies.
Asia-Pacific is the fastest-expanding region, projected at 6.55% CAGR from 2026-2031. China cut diagnosis delays to 0.4 years and increased annual factor consumption as reimbursement broadened. Japan's HIKOBOSHI study shows monthly factor VIII dosing climbed fivefold between 2005 and 2019, reflecting proactive prophylaxis trends. Nonetheless, only 3.2% of Chinese hemophilia A patients access prophylaxis, underscoring financial gaps. Regional working groups push for national registries and coordinated-care programs to harmonize treatment standards.
Europe enjoys mature infrastructure and progressive reimbursement but encounters plasma shortages; the bloc imports around 40% of plasma from the United States and seeks 2 million new donors to stabilize supply. Middle East & Africa and South America face pronounced access deficits; only 8% of African cases are diagnosed, and specialized staff shortages persist. Factor consumption remains well below therapeutic thresholds, sustaining unmet need and positioning these regions as future growth opportunities once infrastructure and reimbursement improve.
- Bayer
- Biomarin Pharmaceutical
- Catalyst Biosciences Inc.
- CSL Ltd. (CSL Behring)
- Roche
- Freeline Therapeutics
- GC Biopharma
- Grifols
- Kedrion Biopharma
- Medexus Pharmaceuticals Inc.
- Novo Nordisk
- Octapharma
- Opko Health
- Pfizer
- Regeneron Pharmaceuticals
- Sangamo Therapeutics
- Sanofi
- Silence Therapeutics plc
- Sobi AB
- Takeda Pharmaceuticals
- UniQure
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising diagnosed prevalence & life-expectancy improvements
- 4.2.2 Launch of extended half-life (EHL) recombinant factors
- 4.2.3 Commercial availability of one-time gene therapies
- 4.2.4 Favorable reimbursement & national hemophilia programs
- 4.2.5 Expansion of non-factor therapies for inhibitor patients
- 4.2.6 Real-world registries enabling precision dosing analytics
- 4.3 Market Restraints
- 4.3.1 High treatment cost & payer budget pressure
- 4.3.2 Care-access gaps in low-/middle-income countries
- 4.3.3 Durability-uncertainty of single-dose gene therapies
- 4.3.4 Plasma-collection shortages disrupting PD product supply
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Disease Type
- 5.1.1 Hemophilia A
- 5.1.2 Hemophilia B
- 5.1.3 Hemophilia C & Others
- 5.2 By Therapy
- 5.2.1 Replacement Therapy
- 5.2.2 Gene Therapy
- 5.2.3 Non-Factor Therapy
- 5.3 By Product Type
- 5.3.1 Recombinant Coagulation Factor Concentrates
- 5.3.2 Plasma-Derived Factor Concentrates
- 5.3.3 Bypassing & Ancillary Agents
- 5.4 By Treatment Setting
- 5.4.1 Prophylaxis
- 5.4.2 On-Demand
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Competitive Benchmarking
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Bayer AG
- 6.4.2 BioMarin Pharmaceutical Inc.
- 6.4.3 Catalyst Biosciences Inc.
- 6.4.4 CSL Ltd. (CSL Behring)
- 6.4.5 F. Hoffmann-La Roche AG
- 6.4.6 Freeline Therapeutics
- 6.4.7 GC Pharma
- 6.4.8 Grifols SA
- 6.4.9 Kedrion SpA
- 6.4.10 Medexus Pharmaceuticals Inc.
- 6.4.11 Novo Nordisk A/S
- 6.4.12 Octapharma AG
- 6.4.13 OPKO Health Inc.
- 6.4.14 Pfizer Inc.
- 6.4.15 Regeneron Pharmaceuticals Inc.
- 6.4.16 Sangamo Therapeutics
- 6.4.17 Sanofi SA
- 6.4.18 Silence Therapeutics plc
- 6.4.19 Sobi AB
- 6.4.20 Takeda Pharmaceutical Co. Ltd.
- 6.4.21 uniQure NV
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


