

|
시장보고서
상품코드
2123264
수막구균 백신 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Meningococcal Vaccines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
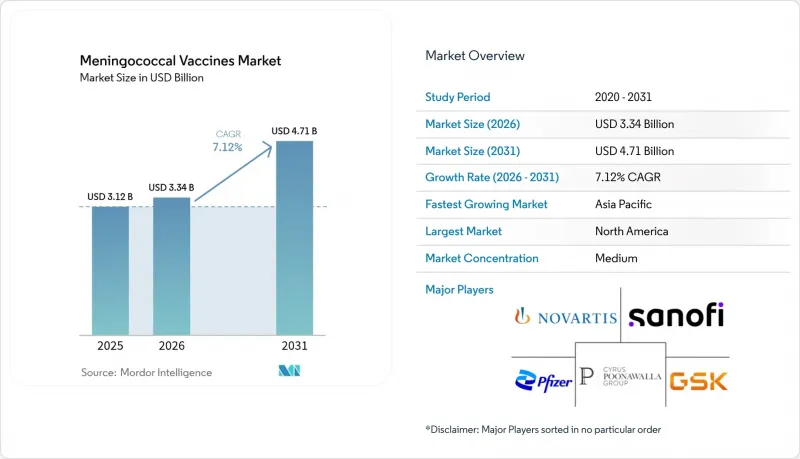
에 의하면, 2026년 수막구균 백신 시장 규모는 33억 4,000만 달러로 추정되고, 2025년 31억 2,000만 달러에서 확대해, 2031년에는 47억 1,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 7.12%로 성장할 것으로 전망됩니다.
본 보고서는 제품 유형별(2가, 4가 등), 백신 유형별(다당류 백신 등), 판매 채널별(공공·민간), 연령대별(영유아(0-2세), 소아 및 성인(2세 이상)), 그리고 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 수막구균 백신 시장 동향 및 인사이트
예방접종 프로그램 확대 및 정부 주도 노력
정부가 자금을 지원하는 백신 도입으로 인해 수막구균 백신이 정기 예방접종 일정 및 해외 여행 요건에 포함됨에 따라 수요가 확대되고 있습니다. 중국의 국가 예방접종 프로그램에서는 수막구균 결합 백신을 포함한 WHO가 권장하는 여러 백신이 전액 공비 부담 대상이 되어, 농촌 지역을 포함한 각 성에서 접근성이 확대되고 있습니다. 프랑스는 2024년, WHO가 주최한 ‘2030년까지 수막염 근절’ 로드맵에 관한 첫 번째 고위급 포럼을 개최하여, 합리적인 가격공급과 감시 체계의 조화를 위한 새로운 공약을 이끌어 냈습니다. 사우디아라비아가 하즈 및 움라 순례자들에게 MenACWY 백신 접종 증명서를 의무화하고 있는 것은 해외 여행객의 준수율이 감사 결과 54%에 그치고 있음에도 불구하고 계속해서 전 세계 수요를 자극하고 있습니다. 이러한 협력 프로그램을 통해 예측 가능한 입찰 주기가 형성되어, 제조업체는 생산 물량을 최적화하고 수익 전망을 세울 수 있게 됩니다.
민관 협력 증대로 개발 비용 절감
백신 개발 기업들은 학술적 발견과 산업적 규모 확대를 융합한 제휴를 통해 공동 자금 조달을 진행하는 사례가 늘고 있습니다. 인도의 세람 인스티튜트는 옥스퍼드 대학교로부터 키메라 단백질을 이용한 MenB 백신 후보에 대한 라이선스를 취득하여, Gavi의 대상 시장에 저비용 부스터 백신을 공급하는 것을 목표로 하고 있습니다. Gavi의 ‘아프리카 백신 제조 가속화 프로그램’은 2024년 현지 생산을 위해 12억 달러를 배정했으며, 이러한 전환을 통해 장기적인 공급이 안정화되고 리드타임이 단축될 것으로 기대됩니다. PATH와 세람 인스티튜트의 협력을 통해 Men5CV가 1회 접종당 약 3달러라는 서유럽 기준 가격보다 대폭 낮은 가격으로 시장에 출시되었습니다. 이는 위험 분담이 최종 사용자의 가격을 어떻게 낮추는지를 보여줍니다. 이러한 모델은 연구개발(R&D)의 리스크를 재분배하여, 소규모 생명공학 기업이 막대한 자본 지출 없이도 새로운 플랫폼 개발을 추진할 수 있도록 하고 있습니다.
콜드체인 보관 및 공급 물류 비용의 부담
전 구간에 걸친 냉장 보관은 여전히 주요 비용 요인으로, 특히 주변 온도가 30°C를 초과하는 지역에서 두드러집니다. 네팔에서 실시된 현장 조사에 따르면, 단열 캐리어 1대당 평균 운송 비용은 1,704달러였으며, 그 중 3분의 1 가량이 운송 중 동결로 인한 손상을 입었습니다. 인도에서 실시된 온도 관리형 콜드체인 시범 사업에서는 1회분당 물류 비용을 0.063달러에서 0.026달러로 절감했으나, 설비 갱신 및 대규모 교육이 필요했습니다. 액티브형 보온 컨테이너를 활용한 드론 배송은 유망한 것으로 평가되지만, 규제 당국의 인가 획득이라는 장벽과 적재량 제한에 직면해 있습니다. 인프라 부족이 만성화되어 있어 최종 비용이 높아지고, 정기적인 재고 부족이 발생하며, 적시 공급이 저해되고 있습니다.
부문 분석
2025년에는 4가 제제가 매출의 53.32%를 차지했으며, 북미 및 유럽의 청소년 부스터 접종 프로그램 전반에서 주도적인 위치를 유지했습니다. 이러한 주도적 지위는 오랜 기간에 걸친 임상적 친화성, 광범위한 보험 적용 범위, 그리고 수막구균 백신 시장을 뒷받침하는 견고한 입찰 체계를 반영한 것입니다. 그러나 표적화된 예방 효과와 저렴한 비용으로 평가받고 있는 2가 제제는 2031년까지 연평균 성장률(CAGR) 8.01%를 기록할 전망입니다. 의료 제공업체들이 1회의 접종으로 5가지 주요 혈청군을 모두 커버할 수 있는 것을 요구함에 따라, 5가 제제의 파이프라인은 ‘기타’ 부문에서 가장 빠르게 성장하고 있습니다.
5가 백신의 승인을 둘러싼 모멘텀은 구조적인 전환점을 시사하고 있습니다. 접종 일정의 간소화와 대상 균주의 확대가 맞물리면서, 미국의 일부 주에서는 학교 내 접종 요건에 대한 재검토가 진행되고 있습니다. 초기 모델 분석에 따르면, 2028년까지 5가 백신의 보급으로 인해 4가 백신 수요 약 30%가 대체될 가능성이 있으며, 수막구균 백신 시장 내 수익 분배가 재편될 전망입니다. CanSino Biologics는 2023년에 5억 6,170만 위안(7,850만 달러)의 2가 백신 매출을 기록하며 전년 대비 266% 증가라는 실적을 통해 이러한 변화를 여실히 보여주었습니다. 이는 현지 유력 기업들이 국내 입찰을 활용하여 시장 점유율을 확대하고 있음을 보여줍니다.
2025년에는 결합형 백신이 시장 점유율의 46.02%를 차지했습니다. 이는 소아용 프로토콜과 시너지를 발휘하는 지속적인 면역원성 및 집단 면역의 이점에 힘입은 결과입니다. 결합형 백신의 골격과 단백질 항원을 결합한 복합형 백신은 연평균 성장률(CAGR) 8.1%를 기록하며 성장 궤도에 올라섰고, 수막구균 백신 시장에서 수익성이 더 높은 SKU에 대한 수요 증가의 여지를 만들어내고 있습니다. 다당류 백신은 비용 면에서의 우위와 신속한 공급 개시가 가능하다는 점에서 감염 확산 시 긴급 대응에 있어 여전히 중요한 역할을 수행하고 있습니다.
최첨단 결합 화학 기술을 통해 현재는 5개의 다당류기를 변이형 디프테리아 단백질에 융합시키는 것이 가능해졌으며, 항원의 완전성을 유지하면서 10년 이상 지속되는 기억 면역 반응을 유지하고 있습니다. Men5CV의 상온 보관 특성은 특히 아프리카에서 Gavi의 자금 지원을 받는 예방접종 캠페인에 있어 유통상의 이점을 제공합니다. 외막 소포(OMV) 및 단백질 나노입자를 이용한 제제는 여전히 개발 단계에 있지만, 열 안정성과 교차 보호 효과가 기대되어 수막구균 백신 업계의 향후 선택지를 넓힐 가능성이 있습니다.
지역별 분석
북미에서는 청소년에 대한 보편적인 예방접종 일정, 광범위한 보험 적용 및 신속한 집단 발병 감지 시스템을 배경으로, 2025년에는 전 세계 매출의 40.05%를 차지했습니다. 미국에서는 11-12세 및 16세를 대상으로 MenACWY 백신을 2회 접종하고 있으며, 고위험군에게는 MenB 백신을 권장하고 있습니다. 캐나다와 멕시코도 유사한 접근 방식을 취하고 있지만, 주마다 차이가 있습니다. Penmenvy의 FDA 승인은 보험 적용 목록 재검토 및 민간 보험사와의 협상을 촉진하여 5가 백신의 보급을 가속화할 가능성이 있습니다. 최근 ST-1466에 의한 집단 감염은 고령층에 남아 있는 취약성을 부각시켰으며, 부스터 접종 대상 연령층 확대에 대한 논의를 촉발하고 있습니다.
유럽에서는 백신 접종률이 성숙 단계에 접어든 반면, 혈청군 동향은 역동적으로 변화하고 있습니다. 2022년 감시 결과 1,149건의 침습성 사례가 확인되었으며, 그중 혈청군 B가 62%를 차지해 여전히 주류를 이루었습니다. 프랑스가 WHO의 뇌수막염 정상회의를 주최함으로써 지역 간 협력이 다시 활성화된 반면, 독일이 MenB를 정기 예방접종 권장 대상에 포함시킨 것은 정책의 진화를 여실히 보여주고 있습니다. 중동 순례에 따른 여행 관련 집단 감염은 출발지 소재 클리닉에서의 4가 부스터 백신 수요를 지속적으로 견인하고 있습니다. 보험 급여 제도는 견조한 추세를 보이고 있으나, 추가적인 성장을 위해서는 5가 백신을 공동 조달 계약에 포함시키는 것이 핵심이 될 것입니다.
아시아태평양은 중국의 정책 강화, 인도의 물류 체계 정비, 그리고 동남아시아의 집단 발생에 대한 경계심에 힘입어 연평균 성장률(CAGR) 8.31%로 가장 빠르게 확대되고 있는 지역입니다. 이 지역의 ‘수막구균 백신 시장’ 동향은 공평한 접근성에 초점이 맞추어져 있습니다. 중국은 국가 계획에서 2028년까지 복합 백신의 완전 접종률 달성을 목표로 하고 있는 반면, 인도네시아는 외딴 섬들에 대한 드론 배송 노선의 시범 운영을 진행하고 있습니다. CanSino나 청두 연구소 등 국내 제조업체들은 비용을 조정한 2가 및 4가 백신을 공급하고 있는 반면, 다국적 기업들은 수입 관세를 회피하기 위해 현지에서 충전 및 마무리 라인 구축을 추진하고 있습니다. 폐렴구균 백신의 성공적인 도입은 다양한 질병에 걸친 확대를 위한 재현 가능한 청사진을 제시하고 있습니다.
중동 및 아프리카에는 상당한 잠재 수요가 있으며, 나이지리아에서의 Men5CV 도입은 수막염 벨트 지역에서 내열성 백신 접종 캠페인의 실현 가능성을 입증하고 있습니다. Gavi, 유니세프, WHO는 비상 비축분을 유지하고 있지만, 유행하기 쉬운 지역 이외의 정기 예방접종 프로그램에 대해서는 여전히 자금 부족이 과제로 남아 있습니다. 남미에서는 감시 체계의 격차로 인해 성장세가 완만하지만, 특히 브라질과 칠레에서 MenACWY 접종률 확대에 관한 지역 전문가들의 합의가 이를 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, meningococcal vaccines market size in 2026 is estimated at USD 3.34 billion, growing from 2025 value of USD 3.12 billion with 2031 projections showing USD 4.71 billion, growing at 7.12% CAGR over 2026-2031.
This report is Segmented by Product Type (Bivalent, Quadrivalent, and More), Vaccine Type (Polysaccharide Vaccines, and More), Sales Channel (Public and Private), Age Group (Infants (Aged 0-2 Years), and Children and Adults (Aged 2 Years and Above)) and Geography (North America, Europe, Asia-Pacific, and More). The Market and Forecasts are Provided in Terms of Value (USD).
Global Meningococcal Vaccines Market Trends and Insights
Rising Immunization Programs & Government Initiatives
Government-financed vaccine roll-outs are scaling demand by integrating meningococcal shots into routine schedules and travel requirements. China's National Immunization Program has moved several WHO-endorsed vaccines, including meningococcal conjugates, into fully funded status, widening access across rural provinces . France convened WHO's first high-level forum on the "Defeating Meningitis by 2030" roadmap in 2024, unlocking new pledges for affordable supply and surveillance harmonisation. Saudi Arabia's requirement for MenACWY proof among Hajj and Umrah pilgrims continues to stimulate global demand, even though compliance audits show only 54% adherence among foreign travellers. These coordinated programs create predictable tender cycles that allow manufacturers to optimise batch sizes and forecast revenue horizons.
Increase in Public-Private Partnerships Lowering Development Costs
Vaccine developers are increasingly co-funded through alliances that blend academic discovery with industrial scale-up. Serum Institute of India licensed a chimeric protein MenB candidate from the University of Oxford, aiming to supply lower-cost boosters to Gavi-eligible markets . Gavi's African Vaccine Manufacturing Accelerator earmarked USD 1.2 billion in 2024 to local production, a shift expected to stabilize long-term supply and reduce lead times. PATH's collaboration with Serum Institute brought Men5CV to market at roughly USD 3 per dose, well below Western benchmarks, illustrating how risk-sharing compresses end-user prices. These models redistribute R&D exposure, enabling smaller biotechnology firms to advance novel platforms without prohibitive capital outlays.
High Cost of Cold-Chain Storage & Supply Logistics
Full-range refrigeration remains a principal cost driver, especially where ambient temperatures exceed 30 °C. Field studies in Nepal reported the average shipment value per insulated carrier at USD 1,704, with nearly one-third subject to freeze damage during transit. Controlled temperature chain pilots in India cut logistics expense from USD 0.063 to USD 0.026 per dose but demanded capital upgrades and extensive training. Drone-enabled distribution with active thermal containers shows promise yet faces regulatory clearance hurdles and limited payload capacity. Persistent infrastructure gaps translate into higher landed costs and periodic stockouts, constraining timely coverage.
Other drivers and restraints analyzed in the detailed report include:
- Growing Incidence of Serogroup W & Y Outbreaks in High-Income Nations
- Introduction of Multivalent Men5CV & Pentavalent Conjugate Platforms
- Waning Adolescent Booster Compliance Post-COVID Vaccine Fatigue
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Quadrivalent formulations generated 53.32% revenue in 2025, maintaining primacy across adolescent booster programs in North America and Europe. This leadership reflects long-standing clinical familiarity, extensive insurance coverage and robust tender frameworks anchoring the meningococcal vaccines market. Yet bivalent solutions, prized for targeted protection and lower cost, post an 8.01% CAGR through 2031. Pentavalent pipelines represent the fastest-rising "other" category as providers seek single-visit coverage for all five major serogroups.
Momentum around pentavalent approvals marks a structural pivot. Confluences of simplified schedules and broader strain breadth have prompted several states in the United States to reassess school requirements. Early modelling suggests pentavalent uptake could displace nearly 30% of quadrivalent demand by 2028, reshaping revenue distribution inside the meningococcal vaccines market. CanSino Biologics highlighted this shift with RMB 561.7 million (USD 78.5 million) bivalent sales in 2023, a 266% annual rise, signalling how local champions exploit domestic tenders for share gains.
Conjugate products held a 46.02% stake in 2025, underpinned by enduring immunogenicity and herd-immunity benefits that dovetail with paediatric protocols. Combination formats combining conjugate backbones with protein antigens are on a trajectory to post an 8.1% CAGR, opening capacity for higher-margin SKUs within the meningococcal vaccines market size. Polysaccharide shots retain a tactical role in outbreak surges because of cost advantages and quicker release timelines.
Cutting-edge conjugation chemistries now fuse five polysaccharide moieties to mutant diphtheria proteins, preserving antigen integrity while sustaining memory responses for a decade or longer. Men5CV's room-temperature profile adds a distribution benefit, particularly for Gavi-funded drives in Africa. Outer-membrane vesicle (OMV) and protein-nanoparticle constructs remain developmental but promise thermostability and cross-protection, potentially widening the meningococcal vaccines industry's future tool kit.
Complete Report Scope:
- By Product Type
- Bivalent
- Quadrivalent
- Others
- By Vaccine Type
- Polysaccharide Vaccines
- Conjugate Vaccines
- Combination Vaccines
- Other Types
- By Sales Channel
- Public
- Private
- By Age Group
- Infants (Aged 0-2 Years)
- Children and Adults (Aged 2 Years and above)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 40.05% of global revenue in 2025 on the back of universal adolescent scheduling, broad payer coverage and rapid outbreak detection systems. The United States implements a two-dose MenACWY series at 11-12 and 16 years and recommends MenB for high-risk populations; Canada and Mexico track similar approaches with provincial variations. FDA approval of Penmenvy is expected to catalyse formulary reviews and private-payer negotiations, potentially accelerating pentavalent uptake. Recent ST-1466 outbreaks underscore residual vulnerability in older adults, prompting discussions on extending booster age brackets.
Europe displays mature uptake yet dynamic serogroup trends. Surveillance captured 1,149 invasive cases in 2022, of which serogroup B remained dominant at 62%. France's hosting of WHO's meningitis summit re-energised regional co-ordination, while Germany's inclusion of MenB into routine recommendations highlights policy evolution. Travel-linked clusters from Middle East pilgrimages continue to spur demand for quadrivalent boosters at point-of-departure clinics. Reimbursement frameworks remain robust, but incremental growth hinges on integrating pentavalent shots into joint procurement contracts.
Asia-Pacific is the fastest-expanding region at an 8.31% CAGR, driven by China's policy upgrades, India's logistic strengthening and Southeast Asian outbreak vigilance. The "meningococcal vaccines market" narrative in the region focuses on equitable access: China's national plan targets full conjugate coverage by 2028, while Indonesia pilots drone-delivery corridors to remote islands. Domestic producers such as CanSino and Chengdu Institute supply cost-adjusted bivalents and quadrivalents, whereas multinationals prepare local fill-finish lines to sidestep import tariffs. Successful pneumococcal roll-outs provide a replicable blueprint for cross-disease scale-up.
Africa and the Middle East represent sizeable latent demand, with Nigeria's Men5CV introduction providing proof of concept for thermostable campaigns in the meningitis belt. Gavi, UNICEF and WHO maintain emergency stockpiles, yet funding gaps persist for routine programs outside epidemic-prone corridors. South America records modest growth, constrained by surveillance disparities but buoyed by regional expert consensus on expanding MenACWY coverage, particularly in Brazil and Chile.
- GlaxoSmithKline
- Pfizer
- Sanofi
- Merck
- Novartis
- Cyrus Poonawala Group (Serum Institute of India Ltd.)
- Bio-Manguinhos
- Biomed Pvt. Ltd.
- Johnson & Johnson (Janssen Vaccines)
- Bharat Biotech Int. Ltd.
- CSL Seqirus
- Bavarian Nordic
- CanSino Biologics Inc.
- Incepta Vaccines Ltd.
- Moderna
- Valneva
- Chongqing Zhifei Biological Products Co.
- Sichuan Clover Biopharmaceuticals
- Panacea Biotec Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising immunization programs & government initiatives
- 4.2.2 Increase in public-private partnerships lowering development costs
- 4.2.3 Growing incidence of serogroup W & Y outbreaks in high-income nations
- 4.2.4 Introduction of multivalent Men5CV & pentavalent conjugate platforms
- 4.2.5 Room-temperature-stable Men5CV enabling last-mile delivery in Africa
- 4.2.6 mRNA / protein-nanoparticle pipeline accelerating MenB boosters
- 4.3 Market Restraints
- 4.3.1 High cost of cold-chain storage & supply logistics
- 4.3.2 Stringent regulatory & liability hurdles for novel serogroup combos
- 4.3.3 Waning adolescent booster compliance post-COVID vaccine fatigue
- 4.3.4 Cannibalization risk from pentavalent vaccines on legacy ACWY & B brands
- 4.4 Regulatory Landscape
- 4.5 Porters Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Bivalent
- 5.1.2 Quadrivalent
- 5.1.3 Others
- 5.2 By Vaccine Type
- 5.2.1 Polysaccharide Vaccines
- 5.2.2 Conjugate Vaccines
- 5.2.3 Combination Vaccines
- 5.2.4 Other Types
- 5.3 By Sales Channel
- 5.3.1 Public
- 5.3.2 Private
- 5.4 By Age Group
- 5.4.1 Infants (Aged 0-2 Years)
- 5.4.2 Children and Adults (Aged 2 Years and above)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 GSK plc
- 6.3.2 Pfizer Inc.
- 6.3.3 Sanofi SA
- 6.3.4 Merck & Co., Inc.
- 6.3.5 Novartis AG
- 6.3.6 Cyrus Poonawala Group (Serum Institute of India Ltd.)
- 6.3.7 Bio-Manguinhos
- 6.3.8 Biomed Pvt. Ltd.
- 6.3.9 Johnson & Johnson (Janssen Vaccines)
- 6.3.10 Bharat Biotech Int. Ltd.
- 6.3.11 CSL Seqirus
- 6.3.12 Bavarian Nordic A/S
- 6.3.13 CanSino Biologics Inc.
- 6.3.14 Incepta Vaccines Ltd.
- 6.3.15 Moderna Inc.
- 6.3.16 Valneva SE
- 6.3.17 Chongqing Zhifei Biological Products Co.
- 6.3.18 Sichuan Clover Biopharmaceuticals
- 6.3.19 Panacea Biotec Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


