

|
시장보고서
상품코드
2123268
폐색 기기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Occlusion Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
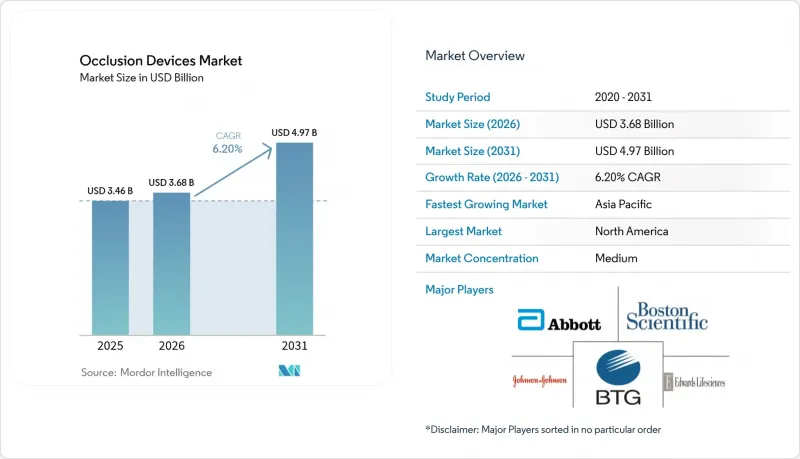
에 의하면, 폐색 기기 시장 규모는 2025년에 34억 6,000만 달러로 평가되었고, 2026년 36억 8,000만 달러에서 2031년까지 49억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.20%를 나타낼 전망입니다.
본 보고서는 제품별(폐색 기기, 색전 장치, 지지 장치), 소재별(니티놀, 백금 등), 용도별(말초 혈관 질환 등), 질환별(허혈성 뇌졸중 등), 최종 사용자별(병원 등), 지역별(북미, 유럽,아시아태평양 등)으로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 폐색 기기 시장 동향 및 인사이트
저침습적 폐색 시술에 대한 관심 증가
2024년에는 규제 당국이 삽입 용이성을 개선하고 합병증 발생률을 낮추는 여러 차세대 시스템을 승인했습니다. 이는 저침습적 접근법에 대한 신뢰도가 높음을 보여줍니다. 비교 연구에 따르면, 개복 수술 대신 폐색 장치를 사용할 경우 입원 기간이 1.5-2일 단축되고, 총 치료 비용이 15-20% 절감되는 것으로 나타났습니다. 이러한 임상적 및 경제적 이점은 특히 보험 환급에 민감한 환경에서 의료 제공업체들의 도입을 촉진하고 있습니다. 저침습 프로토콜이 일상화됨에 따라 외래 진료 센터에서는 시술 건수가 두 자릿수 증가세를 보이고 있으며, 당일 퇴원이 가능한 기기에 대한 수요가 높아지고 있습니다. 고령화에 따라 뇌졸중 및 말초동맥질환의 발생률이 증가하고 있으므로, 저침습적 폐색 치료 솔루션은 앞으로도 치료 알고리즘의 중심적인 위치를 계속 차지할 것입니다.
외래형 혈관내 치료 모델로의 전환
2025년에 개정된 CMS(미국 의료보험서비스센터)의 지급 규정에 따라 외래 환경에서의 혈관 내 시술에 대한 보험 적용 범위가 확대되었습니다. 이러한 변화로 인해 ASC(외래수술센터(ASC))는 병원에 비해 비용 면에서의 우위를 유지하면서 고품질의 폐색 플랫폼에 투자할 수 있게 되었습니다. 다기관 레지스트리 데이터에 따르면, ASC에서의 시술은 안전성 프로파일은 동등한 반면 총 비용이 25-30% 낮은 것으로 나타났습니다. 지급 기관은 시설 사용료 절감이라는 이점을 얻을 수 있기 때문에 보험사는 병원 외에서의 시술을 더 많이 승인하는 추세입니다. 이에 대응해 제조업체들은 더 좁은 시술실을 위해 설계된 콤팩트한 콘솔과 일회용 키트로 대응하고 있습니다. 혈관 내 시술 건수에서 외래 시술이 차지하는 비중이 높아짐에 따라, 휴대성, 사용 편의성, 그리고 확실한 임상 성능의 균형을 갖춘 의료기기에 대한 수요가 집중되고 있습니다.
자원이 제한된 환경에서의 높은 설비 투자 비용
신흥 경제국의 의료 제공업체들은 경쟁적인 지출 우선순위 속에서 고급 폐색 시스템에 대한 자금 조달에 어려움을 겪고 있습니다. 환율 변동과 공급업체가 구매자에게 전가하는 EU MDR 관련 규정 준수 비용으로 인해 구매 가격은 15-25% 상승했습니다. 리스나 공유 서비스 모델과 같은 자금 조달 방식의 혁신으로 장벽이 일부 완화되고 있지만, 뇌졸중 부담이 큰 지방 병원에서는 도입이 지연되고 있습니다. 의료기기에 대한 안정적인 접근이 없다면, 이러한 지역에서는 치료 성과 저하와 의료 격차 확대가 우려됩니다.
부문 분석
2025년, 폐색 치료 기기 시장에서 제거 기기는 42.10%의 점유율을 차지했습니다. 이는 신속한 혈관 재개통이 치료 성과를 좌우하는 뇌졸중 응급 치료에서 제거 기기가 필수적인 역할을 수행하고 있기 때문입니다. 확고한 임상 지침과 유리한 보험 환급 제도가 안정적인 수요를 뒷받침하고 있으며, 혈전 포집 성능을 향상시킨 스텐트 리트리버 등 반복적인 설계 개선을 통해 임상 성능이 더욱 향상되고 있습니다. 새롭게 등장한 소형 코일 리트리버는 치료 가능한 해부학적 범위를 넓혀 이 부문의 회복력을 강화하고 있습니다. 한편, 색전 장치는 종양학 및 예방적 동맥류 치료 워크플로우의 확대에 힘입어 2031년까지 연평균 성장률(CAGR) 7.88%를 나타낼 것으로 예측됩니다. 의료진은 색전제와 전달 카테터를 세트로 구성한 병용 요법 키트를 점점 더 선호하고 있으며, 이로 인해 시술 효율이 향상되고 있습니다. 지원 기기 시장도 마찬가지로 성장하고 있으며, 복잡한 혈관계에서 정확한 삽입을 가능하게 하는 마이크로카테터, 가이드와이어 및 보조 기기를 공급하고 있습니다.
임상의들에 따르면, 추적성이 매우 뛰어난 스텐트 리트리버 덕분에 과거에는 도달이 불가능하다고 여겨졌던 원위부 뇌졸중 영역에서도 제거 장치의 활용이 확대되고 있다고 합니다. 각 제조업체는 조영 마커와 비틀림에 강한 샤프트 설계를 도입하여 촉각 피드백을 유지하면서 전달성을 향상시키고 있습니다. 색전 요법의 혁신가들은 재개통률을 낮추면서도 확실한 폐색을 실현하는 생체활성 코일 및 액체 색전제에 주력하고 있습니다. 종양학 및 외상 분야의 적용 범위가 확대됨에 따라 수익 균형은 점차 색전 요법 쪽으로 기울고 있지만, 응급 신경혈관 분야에서의 응용을 통해 폐색 장치 시장 내 제거 시스템의 우위는 유지되고 있습니다.
2025년 시장 점유율 43.40%를 차지한 니티놀은 그 형상 기억 특성과 초탄성 특성이 구부러진 뇌혈관의 해부학적 구조에 적합하기 때문에 고성능 폐색 기기의 핵심 소재로 계속 자리 잡고 있습니다. 각 공급업체들은 니켈 이온의 방출을 억제하고 내피화를 촉진하기 위해 합금의 순도와 표면 처리를 개선하고 있습니다. 백금은 미세한 해부학적 구조를 시각화하기 위해 높은 방사선 불투과성이 요구되는 사례에서 계속해서 활용되고 있습니다. 대조적으로, 생체 흡수성 폴리머는 연평균 성장률(CAGR) 11.20%로 성장을 지속하고, 있으며, 이는 장기적인 영상 아티팩트를 피하고 향후 중재를 가능하게 하는 일시적인 스캐폴드에 대한 임상의들 수요를 반영하고 있습니다. 초기 임상 프로그램에서는 예측 가능한 분해 프로파일과 양호한 염증 반응이 확인되었으나, 제조 수율 및 멸균 프로토콜로 인해 여전히 비용이 높은 임베디드니다.
각 기기 제조업체들은 가시성과 흡수성을 동시에 확보하기 위해, 폴리머 매트릭스에 방사선 불투과성 섬유를 매립한 하이브리드 구조에 대한 연구를 진행하고 있습니다. 규제 당국은 엄격한 생체 내 분해 데이터를 요구하고 있어, 일부 개념의 경우 시장 진입이 지연되고 있습니다. 그러나 규모의 경제가 실현된다면, 생체 흡수성 의료기기는 영구 임플란트가 평생에 걸친 위험 관리상의 과제를 야기하는 적응증 영역을 확대할 것으로 기대됩니다. 금속의 내구성과 폴리머의 편의성 간의 상충은 예측 기간 동안 소재 연구 개발 예산 배분에 영향을 미칠 가능성이 높습니다.
지역별 분석
북미는 메디케어(Medicare)에 의한 보상 확실성, 밀집된 뇌졸중 치료 센터 네트워크, 그리고 대학 병원 및 업계 파트너에 걸친 성숙한 혁신 생태계의 뒷받침을 받아 2025년 매출의 42.60%를 차지했습니다. AI 및 생체 흡수성 소재에 대한 FDA의 정책이 계속해서 명확함에 따라, 새로운 폐색 치료 솔루션에 유리한 시장 진입 환경이 유지되고 있습니다. 캐나다의 단일 지불자 제도는 뇌졸중 예방에 대한 추가 자금을 유도하고 있는 반면, 멕시코에서는 민관 협력을 통한 병원 확장으로 치료 수행 능력이 점차 확대되고 있습니다. 인재의 집중과 지불자 및 의료 제공업체 간의 견고한 협력 덕분에, 비용 억제 압력이 높아지는 상황에서도 북미의 리더십은 유지되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 12.41%로 지역 중 가장 높으며, 병원 건설의 급속한 진전, 보험 제도의 확대, 그리고 고령화에 따른 뇌혈관 질환 유병률 상승이 이를 뒷받침하고 있습니다. 중국의 ‘치료 건수 기반 조달’ 체계로 인해 가격 수준은 압박을 받고 있지만, 방대한 시술 건수와 각 성에서 뇌졸중 센터가 확대됨에 따라 이익률에 가해지는 압박은 상쇄되고 있습니다. 일본은 고정밀 마이크로카테터 및 첨단 합금 조성에 대한 연구를 주도하고 있지만, 인구 통계학적 역풍으로 인해 장기적인 시술 건수 증가세는 완만해지고 있습니다. 인도에서는 신경 중재술 연수 체계가 정비되고 중산층의 보험 가입률도 상승하고 있어, 인프라 부족에도 불구하고 두 자릿수 후반대의 성장률을 달성하고 있습니다. 한국과 호주는 고도의 치료 능력을 갖춘 3차 의료기관과 활발한 임상시험 참여에 힘입어 안정적인 수요가 예상됩니다.
유럽에서는 견실한 국민건강보험 제도, 대륙 전체에 걸친 뇌졸중 치료 프로토콜, 그리고 여러 시장에서 제품 출시를 신속하게 하는 EU 전역의 규제 조화에 힘입어 안정적인 한 자릿수 중반대의 성장을 유지하고 있습니다. 독일의 공학 기술 강점은 현지 제조 클러스터를 뒷받침하고 있는 반면, 브렉시트 이후 조정을 진행 중인 영국은 진료 지침 수립 및 결과 연구에서 여전히 큰 영향력을 유지하고 있습니다. 남유럽 시장은 병원 현대화에 자금을 투입하는 EU의 결속 기금의 혜택을 받고 있는 반면, 동유럽에서는 환급 제도가 성숙해짐에 따라 장기적인 성장 여지가 예상됩니다. 유럽의약품청(EMA)과 미국 식품의약국(FDA) 간의 공동 이니셔티브를 통해 증거 공유가 가속화되면서 대서양을 가로지르는 제품 출시 기간이 단축되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the occlusion devices market size was valued at USD 3.46 billion in 2025 and estimated to grow from USD 3.68 billion in 2026 to reach USD 4.97 billion by 2031, at a CAGR of 6.20% during the forecast period (2026-2031).
This report is Segmented by Product (Occlusion Removal Devices, Embolization Devices, Support Devices), Material (Nitinol, Platinum, and More), Application (Peripheral Vascular Disease, and More), Disease Pathology (Ischemic Stroke, and More), End User (Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Occlusion Devices Market Trends and Insights
Growing Preference for Minimally Invasive Occlusive Procedures
Regulators cleared several next-generation systems in 2024 that improve deliverability and reduce complication rates, illustrating confidence in less-invasive approaches. Comparative studies show hospital stay reductions of 1.5-2 days and 15-20% total episode cost savings when occlusion devices replace open surgery. These clinical and economic benefits encourage provider adoption, especially in reimbursement-sensitive environments. Ambulatory centers report double-digit volume increases as minimally invasive protocols become routine, reinforcing demand for devices that support same-day discharge. With stroke and peripheral arterial disease incidence rising among ageing populations, minimally invasive occlusion solutions remain central to future treatment algorithms.
Shift Toward Ambulatory Endovascular Care Models
Updated 2025 CMS payment rules now reimburse a broader list of endovascular procedures in outpatient settings. This shift lets ASCs invest in premium occlusion platforms while maintaining cost advantages over hospitals. Data from multisite registries indicate equivalent safety profiles and 25-30% lower total costs for ASC procedures. Payers gain from reduced facility fees, prompting insurers to authorise more cases outside hospitals. Manufacturers respond with compact consoles and single-use kits engineered for smaller procedure rooms. As the outpatient share of endovascular volumes climbs, demand concentrates on devices that balance portability, ease of use, and robust clinical performance.
High Capital Costs in Resource-Limited Settings
Healthcare providers in emerging economies struggle to fund premium occlusion systems amid competing spending priorities. Currency volatility and EU MDR-related compliance costs that suppliers pass through to buyers raise acquisition prices by 15-25%. Financing innovations such as leasing and shared-service models partly ease barriers, yet uptake lags in rural hospitals where stroke burden is high. Without consistent device access, these regions risk poorer outcomes and widening care disparities.
Other drivers and restraints analyzed in the detailed report include:
- Integration of AI-Guided Imaging & Robotic Assistance
- Broader Insurance Coverage for Stroke Interventions
- Training Demands for Neuro-Occlusion Techniques
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Removal devices secured 42.10% of the occlusion devices market in 2025 owing to their indispensable role in emergency stroke care where rapid vessel recanalisation dictates outcomes. Robust clinical guidelines and favourable reimbursement sustain steady demand, while iterative design advances such as enhanced clot-engagement stent retrievers sharpen clinical performance. Emerging miniaturised coil retrievers broaden treatable anatomy, reinforcing segment resilience. Concurrently, Embolization devices post an 7.88% CAGR to 2031, propelled by growth in oncology and preventive aneurysm workflows. Providers increasingly prefer combination therapy kits that package embolic agents with delivery catheters, improving procedural efficiency. Support devices grow in tandem, supplying micro-catheters, guidewires, and ancillary tools that enable precise deployment across complex vasculature.
Clinicians report expanding utilisation of removal devices in distal stroke territories once considered unreachable, thanks to ultra-trackable stent retrievers. Manufacturers integrate radiopaque markers and kink-resistant shaft designs that maintain tactile feedback while improving deliverability. Embolization innovators focus on bio-active coils and liquid embolics that achieve definitive occlusion with lower re-canalisation rates. As oncologic and trauma indications broaden, the balance of revenue slowly tilts toward embolization, yet emergency neurovascular applications safeguard the primacy of removal systems within the occlusion devices market.
Nitinol, with 43.40% 2025 share, remains the backbone of high-performance occlusion devices because shape-memory and super-elastic characteristics match tortuous cerebrovascular anatomy. Suppliers refine alloy purity and surface treatments to mitigate nickel ion release and enhance endothelialisation. Platinum continues serving cases requiring high radiopacity for fine anatomical visualisation. In contrast, bio-resorbable polymers record an 11.20% CAGR, mirroring clinician appetite for temporary scaffolds that avoid long-term imaging artefacts and permit future interventions. Early clinical programs demonstrate predictable degradation profiles and favourable inflammatory responses, although manufacturing yields and sterilisation protocols still add cost premiums.
Device makers explore hybrid constructions, embedding radiopaque fibres into polymer matrices to marry visibility with resorption. Regulatory bodies require stringent in-vivo degradation data, delaying market entry for some concepts. Yet once scale efficiencies materialise, bio-resorbables promise to expand indications where permanent implants pose lifetime risk management challenges. The competition between metallic durability and polymer convenience is likely to shape materials R&D budgets throughout the forecast period.
Complete Report Scope:
- By Product
- Occlusion Removal Devices
- Coil Retrievers
- Stent Retrievers
- Other Removal Devices
- Embolization Devices
- Support Devices
- Occlusion Removal Devices
- By Material
- Nitinol
- Platinum
- Bio-resorbable Polymers
- By Application
- Peripheral Vascular Disease
- Neurology
- Oncology
- Urology
- Other Applications
- By Disease Pathology
- Ischemic Stroke
- Cerebral Aneurysm
- Peripheral Arterial Occlusion
- Tumor Embolization
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 42.60% of 2025 revenue, buoyed by Medicare reimbursement certainty, dense stroke-centre networks, and a mature innovation ecosystem spanning academic hospitals and industry partners. Continued FDA policy clarity around AI and bio-resorbables sustains a favourable launch environment for novel occlusion solutions. Canada's single-payer system channels incremental funding to stroke prevention, while Mexico's public-private hospital expansion gradually adds procedure capacity. Talent concentration and strong payer-provider alignment preserve North America's leadership despite intensifying cost-containment pressures.
Asia-Pacific posts the fastest regional CAGR at 12.41% through 2031, underpinned by rapid hospital construction, insurance expansion, and mounting cerebrovascular disease prevalence among ageing citizens. China's Volume-Based Procurement framework compresses price points, yet sheer procedural volume and provincial stroke-centre rollouts offset margin pressure. Japan leads research into high-precision micro-catheters and advanced alloy compositions, although demographic headwinds moderate long-term procedure growth. India, with improving neuro-interventional training pipeline and rising middle-class insurance coverage, delivers high-double-digit unit growth despite infrastructure gaps. South Korea and Australia provide stable demand anchored in high-acuity tertiary facilities and active clinical-trial participation.
Europe maintains steady, mid-single-digit growth driven by robust universal healthcare systems, continent-wide stroke care protocols, and pan-EU regulatory harmonisation that expedites multi-market launches. Germany's engineering strengths support local manufacturing clusters, while the United Kingdom, navigating post-Brexit adjustments, remains influential in guideline development and outcomes research. Southern European markets benefit from EU Cohesion Funds funnelling capital into hospital modernisation, whereas Eastern Europe offers long-term upside as reimbursement frameworks mature. Collaborative initiatives between the European Medicines Agency and FDA accelerate evidence sharing, shortening time-to-market for cross-Atlantic product launches.
- Medtronic
- Boston Scientific
- Abbott Laboratories
- Stryker
- Terumo
- Penumbra
- Merit Medical Systems
- Edward Lifesciences
- Johnson & Johnson
- BTG International
- Cook Group
- W. L. Gore & Associates
- MicroVention (Terumo)
- Kaneka Corp.
- Acandis
- Phenox
- Cardinal Health
- Balt Extrusion
- Asahi Intecc
- B. Braun
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Preference for Minimally Invasive Occlusive Procedures
- 4.2.2 Shift Toward Ambulatory Endovascular Care Models
- 4.2.3 Integration of AI-Guided Imaging & Robotic Assistance
- 4.2.4 Broader Insurance Coverage for Stroke Interventions
- 4.2.5 Rising Neuro-Oncology Demand Linked to SRS & Trans-Radial Techniques
- 4.2.6 Civilian Adoption of Military Hemorrhage Control Devices
- 4.3 Market Restraints
- 4.3.1 High Capital Costs in Resource-Limited Settings
- 4.3.2 Training Demands for Neuro-Occlusion Techniques
- 4.3.3 Material Safety Concerns in Flow-Diversion
- 4.3.4 Vulnerable Supply Chains for High-Grade Alloys
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product
- 5.1.1 Occlusion Removal Devices
- 5.1.1.1 Coil Retrievers
- 5.1.1.2 Stent Retrievers
- 5.1.1.3 Other Removal Devices
- 5.1.2 Embolization Devices
- 5.1.3 Support Devices
- 5.1.1 Occlusion Removal Devices
- 5.2 By Material
- 5.2.1 Nitinol
- 5.2.2 Platinum
- 5.2.3 Bio-resorbable Polymers
- 5.3 By Application
- 5.3.1 Peripheral Vascular Disease
- 5.3.2 Neurology
- 5.3.3 Oncology
- 5.3.4 Urology
- 5.3.5 Other Applications
- 5.4 By Disease Pathology
- 5.4.1 Ischemic Stroke
- 5.4.2 Cerebral Aneurysm
- 5.4.3 Peripheral Arterial Occlusion
- 5.4.4 Tumor Embolization
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centers
- 5.5.3 Specialty Clinics
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Medtronic
- 6.3.2 Boston Scientific Corporation
- 6.3.3 Abbott Laboratories
- 6.3.4 Stryker Corporation
- 6.3.5 Terumo Corporation
- 6.3.6 Penumbra Inc.
- 6.3.7 Merit Medical Systems
- 6.3.8 Edwards Lifesciences
- 6.3.9 Johnson & Johnson
- 6.3.10 BTG International Ltd
- 6.3.11 Cook Medical
- 6.3.12 W. L. Gore & Associates
- 6.3.13 MicroVention (Terumo)
- 6.3.14 Kaneka Corp.
- 6.3.15 Acandis GmbH
- 6.3.16 Phenox GmbH
- 6.3.17 Cardinal Health
- 6.3.18 Balt Extrusion
- 6.3.19 Asahi Intecc
- 6.3.20 B. Braun Melsungen
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


