|
시장보고서
상품코드
2123281
5G 서비스 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)5G Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
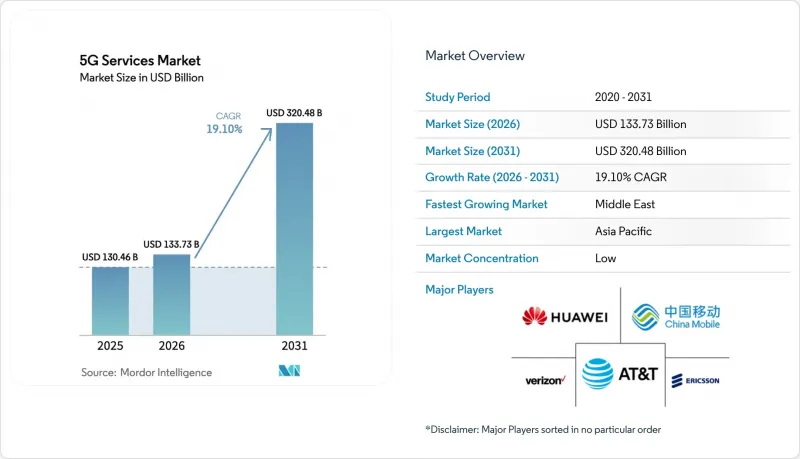
5G 서비스 시장 규모는 2025년 1,304억 6,000만 달러에서 2026년에는 1,337억 3,000만 달러로 확대되어 2031년까지 3,204억 8,000만 달러에 이를 것으로 예상되고 있어 2026년부터 2031년까지 CAGR 19.1%로 성장할 전망입니다.
본 보고서는 서비스 유형(고도 모바일 브로드밴드, 초고신뢰성·저지연 통신 등), 네트워크 아키텍처(비독립형 5G 및 독립형 5G), 주파수 대역(저대역, 중대역, mm파),최종 사용자 산업(IT 및 통신, 미디어 및 엔터테인먼트, 자동차·모빌리티 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 5G 서비스 시장 동향 및 인사이트
폭발적으로 증가하는 모바일 데이터 트래픽
월간 트래픽은 2025년 141 엑사바이트에서 2031년에는 추정 400 엑사바이트로 증가하여 교외의 매크로 계층에 부하를 가하고, 미드밴드 셀 분할 증가를 초래하고 있습니다. 북미에서는 고정 무선 회선이 전년 대비 2배로 증가하여 모바일 통신 채널에서 용량이 전용되는 한편, mm파 스몰 셀의 경제성이 입증되고 있습니다. 현재 다운링크 트래픽의 72%를 울트라 HD 동영상이 차지하는 반면, 클라우드 게임은 동적 스펙트럼 공유가 필요한 버스트 형태의 업링크 피크를 유발하고 있습니다. 상시 연결형 웨어러블 단말기와 자동차 텔레매틱스로 인해 세션 프로파일이 다양화되면서, 통신 사업자들은 혼잡 시에도 경험 품질(QoE)을 유지하기 위해 AI 기반 트래픽 스티어링을 도입해야 하는 상황에 직면해 있습니다.
eMBB 서비스에 대한 소비자의 높은 수요
무제한 기가비트 요금제는 5G 총 수익의 52.84%를 차지하고 있으며, 미국의 통신 사업자들은 요금제 전환을 통해 사용자 1인당 평균 수익이 4.20달러 증가했다고 보고하고 있습니다. 한국의 통신 사업자들은 클라우드 스토리지 및 스트리밍 혜택을 번들로 제공하여 6개월 이내에 프리미엄 요금제 채택률을 38% 이상으로 끌어올렸습니다. 스마트폰을 통한 8K 동영상 촬영은 대칭적인 트래픽의 급증으로 이어지고 있어, 업링크 캐리어 어그리게이션 및 추가 주파수 대역에 대한 투자를 불가피하게 만들고 있습니다. 통신 사업자들은 무이자 할부를 통해 단말기 교체를 촉진함으로써, 교체 주기를 단축하는 동시에 가입자를 수익성이 높은 요금제에 정착시켜 수익화를 도모하고 있습니다.
높은 도입 비용과 긴 ROI 회수 기간
스탠드얼론형 코어 네트워크, 고밀도 미드밴드 그리드 및 백홀 업그레이드로 인해 2024년부터 2027년까지 전 세계 지출은 1,500억 달러를 넘어설 전망이며, 투자 회수 기간은 7-9년에 달할 것으로 예측됩니다. 한 미국 통신 사업자는 C-밴드 밀도 향상을 위해 180억 달러의 추가 설비 투자가 필요하다고 밝혔습니다. 한편, 광섬유가 구축되지 않은 지방의 기지국에는 한 곳당 25만 달러의 비용이 소요되어 디지털 격차를 확대시키고 있습니다. 전력 요금은 4G에 비해 30-40% 상승했으며, 통신 사업자들은 탄소 감축 목표 달성과 운영 비용(OPEX) 절감을 위해 재생에너지 공급 계약을 체결해야 하는 상황에 놓여 있습니다. 자금 사정이 어려워 비용에 민감한 지역에서는 독립형(stand-alone) 방식으로의 전환이 지연되고 있습니다.
부문별 분석
2025년 매출의 52.84%를 ‘강화형 모바일 광대역’이 차지하고 있으며, 이는 기가비트급 소비자용 패키지와 교외 지역의 고정 무선 링크에 대한 수요를 반영합니다. 한편, ‘대규모 머신 유형 통신(MMC)’은 2031년까지 연평균 19.21%의 성장률을 보이며, 제조업, 유틸리티, 스마트 시티 네트워크에 널리 보급된 배터리 효율이 뛰어난 센서로 전환되고 있음을 시사합니다. 통신 사업자가 가드밴드나 레거시 2G 주파수 대역을 재할당하여 저전력 오버레이 통신에 활용함에 따라, 협대역 IoT 엔드포인트를 위한 5G 서비스 시장 규모는 확대되고 있습니다. 이를 통해 모듈 단가 5달러 미만으로 셀당 5만 대의 기기를 지원할 수 있게 됩니다.
URLLC는 여전히 틈새 분야에 머물러 있으며, V2X(차량과 모든 사물 간의 통신) 시범 사업이나 책임 소재에 관한 프레임워크 정비를 기다리고 있는 원격 조종 로봇 등으로 한정되어 있습니다. 하지만 2028년까지는 릴리스 18의 스케줄링과 엣지 컴퓨팅의 융합으로 인해 서비스 유형 간의 경계가 모호해질 것입니다. mMTC 슬라이스를 분석 플랫폼과 번들로 제공하는 통신 사업자는 지속성이 높은 기업용 수익을 창출하며, 5G 서비스 시장의 장기적인 성장을 뒷받침하고 있습니다.
2025년에는 LTE 코어 네트워크 덕분에 시장 출시까지의 시간이 단축됨에 따라, 비독립형(NSA) 구축이 63.72%의 점유율을 차지했습니다. 그러나 19.53%의 성장률을 보이는 스탠드얼론(SA) 네트워크는 슬라이싱, 결정론적 지연, 그리고 보이스 오버 뉴 라디오(VoNR) 서비스에 필수적인 전제조건입니다. 미국의 한 통신 사업자는 전국적인 SA 도입 후 통화 설정 시간을 35% 단축했습니다. 기업 고객들이 NSA에서는 보장할 수 없는 전용 SLA를 요구함에 따라 5G 서비스 시장 점유율 변화는 가속화되고 있습니다.
자본 지출(Capex)의 장벽은 여전히 남아 있지만, 레거시 패킷 코어를 폐지하는 통신 사업자들은 데이터센터 통합 및 클라우드 네이티브 자동화를 통해 운영 비용(OpEx)을 절감하고 있습니다. 신흥 시장에서는 NSA가 더 오랫동안 유지될 가능성이 있지만, LTE의 부정적인 유산을 지니지 않은 신규 진출기업들은 단숨에 클라우드 네이티브 SA로 도약하여, 서비스가 충분히 제공되지 않는 지역의 5G 서비스 시장 확대를 주도하고 있습니다.
지역별 분석
아시아태평양은 중국의 400만 개 사이트에 달하는 중대역 네트워크와 인도의 2대 통신 사업자에 의한 급속한 도시 지역 커버리지 확대에 힘입어 2025년 매출의 40.92%를 차지했습니다. 차이나모바일은 2025년 하반기, 300개 도시에서 ‘5G-Advanced’ 서비스를 시작하며 10Gbps 프리미엄 요금제와 게임 전용 패스를 번들로 제공했습니다. 일본에서는 Open RAN 도입으로 지방 기지국 비용이 28% 절감된 반면, 한국은 5G 보급률이 72%로 세계 최고 수준을 자랑하고 있습니다.
중동은 연평균 성장률(CAGR) 20.01%로 가장 빠르게 성장하고 있는 지역입니다. 아랍에미리트(UAE)의 통신 사업자는 2025년 중반까지 인구의 95%를 커버하며, 자율주행 셔틀과 AI 기반 교통 관제를 도입한 스마트 시티 시범 사업을 지원하고 있습니다. 사우디아라비아의 통신 사업자는 ‘비전 2030’의 목표에 따라 석유, 물류, 의료 등 산업 분야를 대상으로 주요 도시권에서 독립형 코어 네트워크를 구축했습니다. 한편, 튀르키예는 고정 무선과의 경쟁을 염두에 두고 국내 3대 도시에서 5G 서비스를 시작했습니다.
북미와 유럽에서는 가입자 주도 성장 속도가 둔화되고 있지만, 기업용 및 고정 무선 사업 확대로 무게중심을 옮기고 있습니다. 한 미국 통신사업자의 C-밴드 네트워크는 2025년 12월까지 2억 3,000만 명을 커버하며, 400만 회선의 고정 무선 서비스를 통해 수익을 창출하고 있습니다. 도이치 텔레콤의 국경을 초월한 슬라이스 제공으로 기업용 매출은 전년 대비 14% 증가했습니다. 남미와 아프리카는 주파수 경매 지연, 단말기 가격 격차, 백홀 부족으로 인해 뒤처지고 있지만, 브라질과 남아프리카공화국에서의 선택적 확장을 통해 기존 이동통신 사업자들은 광섬유로의 전환 흐름으로부터 입지를 지키고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the 5G services market size is expected to increase from USD 130.46 billion in 2025 to USD 133.73 billion in 2026 and reach USD 320.48 billion by 2031, growing at a CAGR of 19.1% over 2026-2031.
This report is Segmented by Service Type (Enhanced Mobile Broadband, Ultra-Reliable Low-Latency Comms, and More), Network Architecture (Non-Standalone 5G and Standalone 5G), Frequency Band (Low-Band, Mid-Band, and Millimetre-Wave), End-User Industry (IT and Telecom, Media and Entertainment, Automotive and Mobility, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global 5G Services Market Trends and Insights
Exploding Mobile Data Traffic
Monthly traffic rose from 141 exabytes in 2025 to an estimated 400 exabytes by 2031, straining suburban macro layers and triggering extra mid-band cell splits. Fixed-wireless lines doubled year-on-year in North America, diverting capacity from mobility channels and validating the economics of millimeter-wave small cells. Ultra-HD video now represents 72% of downlink volumes, while cloud gaming introduces bursty uplink peaks that require dynamic spectrum sharing. Always-connected wearables and automotive telematics diversify session profiles, pushing carriers toward AI-driven traffic steering that sustains quality of experience during congestion events.
High Consumer Demand for eMBB Services
Unlimited gigabit plans account for 52.84% of total 5G revenue, and U.S. operators report average revenue per user uplifts of USD 4.20 from plan migration. South Korean carriers bundled cloud storage and streaming perks, boosting premium-tier adoption to more than 38% within 6 months. Smartphone-based 8K capture creates symmetrical traffic bursts, forcing investment in uplink carrier aggregation and supplemental spectrum blocks. Operators monetize handset upgrades through zero-interest financing that shortens replacement cycles and locks subscribers into higher-margin tiers.
High Deployment Cost and Long ROI Horizons
Standalone cores, dense mid-band grids, and upgraded backhaul exceed USD 150 billion in global outlays over 2024-2027, stretching payback to 7-9 years. A U.S. carrier revealed USD 18 billion incremental capex for C-band densification, while rural sites without fiber need USD 250,000 each, widening digital divides. Energy bills rise 30-40% versus 4G, pushing operators to sign renewable power agreements to satisfy carbon pledges and control opex. Capital pressure delays stand-alone migration in cost-sensitive regions.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise Digital-Transformation Use Cases
- Government Spectrum-Release Initiatives
- Fragmented and Delayed Spectrum Policy
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Enhanced Mobile Broadband accounted for 52.84% of 2025 revenue, reflecting demand for gigabit-rate consumer packages and suburban fixed-wireless links. Massive Machine-Type Communications, however, is expanding at 19.21% through 2031, signaling a pivot toward battery-efficient sensors that flood manufacturing, utilities, and smart-city grids. The 5G services market size for narrowband IoT endpoints is rising as operators refarm guard bands and legacy 2G spectrum for low-power overlays, enabling support for 50,000 devices per cell at module prices below 5 USD.
URLLC remains niche, limited to vehicle-to-everything pilots and remote control robotics awaiting mature liability frameworks. Still, by 2028, Release 18 scheduling and edge-compute convergence will blur the lines between service types. Operators bundling mMTC slices with analytics platforms generate sticky enterprise revenue, bolstering long-term growth of the 5G services market.
Non-Standalone deployments held 63.72% share in 2025 because LTE cores enabled quick time-to-market. Yet Standalone networks, growing at 19.53%, are a prerequisite for slicing, deterministic latency, and voice-over-new-radio services. A U.S. carrier trimmed call set-up times 35% after national SA activation. The 5G services market share shift accelerates as enterprise clients demand dedicated SLAs that NSA cannot guarantee.
Capex hurdles remain, but operators retiring legacy packet cores realize opex savings from data-center consolidation and cloud-native automation. Emerging markets may retain NSA longer, yet greenfield entrants without LTE baggage leapfrog straight to cloud-native SA, expanding the 5G services market footprint in underserved geographies.
Complete Report Scope:
- By Service Type
- Enhanced Mobile Broadband (eMBB)
- Ultra-Reliable Low-Latency Comms (URLLC)
- Massive Machine-Type Comms (mMTC)
- By Network Architecture
- Non-Standalone (NSA) 5G
- Standalone (SA) 5G
- By Frequency Band
- Low-Band (Less than 1 GHz)
- Mid-Band (1- 6 GHz)
- Millimetre-Wave (Greater than 24 GHz)
- By End-User Industry
- IT and Telecom
- Media and Entertainment
- Automotive and Mobility
- Energy and Utilities
- Aerospace and Defense
- Manufacturing
- Healthcare
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific supplied 40.92% of 2025 revenue, anchored by China's four-million-site mid-band footprint and India's rapid urban coverage by two national carriers. China Mobile launched 5G-Advanced in 300 cities late in 2025, bundling 10 Gbps premium tiers and gaming passes. Japan's Open RAN buildouts cut rural site costs 28%, while South Korea boasts 72% 5G penetration, the world's highest.
The Middle East is the fastest-growing territory at a 20.01% CAGR. United Arab Emirates operators achieved 95% population reach by mid-2025, underpinning smart-city pilots with autonomous shuttles and AI traffic controls. Saudi carriers launched standalone cores across major metros to serve oil, logistics, and healthcare verticals in line with Vision 2030 ambitions, while Turkey switched on 5G in its three largest cities, targeting fixed-wireless competition
North America and Europe exhibit slower subscriber-driven growth but pivot to enterprise and fixed-wireless scaling. A U.S. carrier's C-band network covered 230 million people by December 2025, monetizing 4 million fixed-wireless lines. Deutsche Telekom's cross-border slices boosted enterprise revenue 14% year-on-year. South America and Africa trail because of auction delays, device affordability gaps, and backhaul shortfalls, although selective rollouts in Brazil and South Africa defend mobile incumbents against fiber overtures.
- China Mobile Ltd.
- Verizon Communications Inc.
- AT&T Inc.
- T-Mobile US Inc.
- China Telecom Corp. Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corp.
- Huawei Technologies Co. Ltd.
- Deutsche Telekom AG
- Vodafone Group Plc
- Orange S.A.
- Telefonica S.A.
- BT Group plc
- Swisscom AG
- Telstra Corp. Ltd.
- SK Telecom Co. Ltd.
- KT Corp.
- Rakuten Mobile Inc.
- Reliance Jio Infocomm Ltd.
- Qualcomm Inc.
- Samsung Electronics Co. Ltd.
- ZTE Corp.
- NTT Docomo Inc.
- Bharti Airtel Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Exploding Mobile Data Traffic
- 4.2.2 High Consumer Demand For eMBB Services
- 4.2.3 Enterprise Digital-Transformation Use-Cases
- 4.2.4 Government Spectrum-Release Initiatives
- 4.2.5 Private-5G Uptake in CBRS and Local-Licence Bands
- 4.2.6 Monetisation Via Network Slicing and SLA Tiers
- 4.3 Market Restraints
- 4.3.1 High Deployment Cost and Long ROI Horizons
- 4.3.2 Fragmented and Delayed Spectrum Policy
- 4.3.3 Limited 5G Device Readiness In Emerging Markets
- 4.3.4 Geopolitical Vendor Restrictions and Trade Bans
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Enhanced Mobile Broadband (eMBB)
- 5.1.2 Ultra-Reliable Low-Latency Comms (URLLC)
- 5.1.3 Massive Machine-Type Comms (mMTC)
- 5.2 By Network Architecture
- 5.2.1 Non-Standalone (NSA) 5G
- 5.2.2 Standalone (SA) 5G
- 5.3 By Frequency Band
- 5.3.1 Low-Band (Less than 1 GHz)
- 5.3.2 Mid-Band (1- 6 GHz)
- 5.3.3 Millimetre-Wave (Greater than 24 GHz)
- 5.4 By End-User Industry
- 5.4.1 IT and Telecom
- 5.4.2 Media and Entertainment
- 5.4.3 Automotive and Mobility
- 5.4.4 Energy and Utilities
- 5.4.5 Aerospace and Defense
- 5.4.6 Manufacturing
- 5.4.7 Healthcare
- 5.4.8 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 China Mobile Ltd.
- 6.4.2 Verizon Communications Inc.
- 6.4.3 AT&T Inc.
- 6.4.4 T-Mobile US Inc.
- 6.4.5 China Telecom Corp. Ltd.
- 6.4.6 Telefonaktiebolaget LM Ericsson
- 6.4.7 Nokia Corp.
- 6.4.8 Huawei Technologies Co. Ltd.
- 6.4.9 Deutsche Telekom AG
- 6.4.10 Vodafone Group Plc
- 6.4.11 Orange S.A.
- 6.4.12 Telefonica S.A.
- 6.4.13 BT Group plc
- 6.4.14 Swisscom AG
- 6.4.15 Telstra Corp. Ltd.
- 6.4.16 SK Telecom Co. Ltd.
- 6.4.17 KT Corp.
- 6.4.18 Rakuten Mobile Inc.
- 6.4.19 Reliance Jio Infocomm Ltd.
- 6.4.20 Qualcomm Inc.
- 6.4.21 Samsung Electronics Co. Ltd.
- 6.4.22 ZTE Corp.
- 6.4.23 NTT Docomo Inc.
- 6.4.24 Bharti Airtel Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment