

|
시장보고서
상품코드
2123294
적응 광학 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Adaptive Optics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
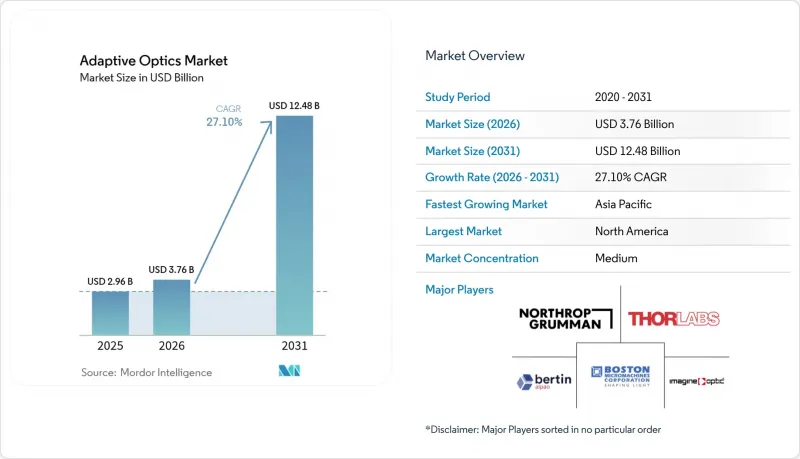
적응 광학 시장 규모는 2026년에 37억 6,000만 달러로 추정되고 있어 2025년 29억 6,000만 달러에서 확대해, 2031년에는 124억 8,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 27.10%가 될 것으로 전망됩니다.
본 보고서는 구성 요소별(파면 센서, 변형 미러 등), 최종 사용자별(국방, 의료, 산업, 소비자용 전자기기 등), 용도별(천문학, 안과, 레이저 통신, 반도체, AR/VR 등),기술별(MEMS DM, 압전식 DM, LC SLM 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 적응 광학 시장 동향 및 인사이트
고해상도 망막 영상 진단 분야에서 적응 광학의 급속한 보급
안과 기기 제조업체들은 현재 세포 수준의 망막 영상을 촬영하기 위해 다공액형 적응 광학을 통합하고 있으며, 이를 통해 질환의 조기 발견이 가능해졌습니다. 2024년 FDA가 초음파 사이클로데스트럭티브 디바이스를 클래스 III에서 클래스 II로 재분류한 것은 첨단 이미징 플랫폼에 대해 보다 예측 가능한 로드맵이 제시되었음을 의미합니다. 알콘(Alcon)의 ‘Unity VCS’ 및 ‘Unity CS’ 승인은 상용화 준비가 점차 갖춰지고 있음을 보여주는 한편, AI를 활용한 파면 알고리즘을 통해 진료대에서의 보정 시간이 단축되고 있습니다. Profundus Imaging과 같은 스타트업 기업들은 여러 개의 변형 가능한 거울을 사용하여 보정 시야를 확대하는 프로토타입을 개발하고 있습니다. 이러한 발전으로 인해 주요 학술 기관 이외의 진료소에서도 도입 장벽이 낮아지면서, 적응 광학 시장의 의료 분야로의 확산이 가속화되고 있습니다.
지향성 에너지 및 자유 공간 레이저 통신 프로그램으로의 도입
미국 국방부는 고에너지 레이저 시스템에 연간 10억 달러 이상을 투자하고 있으며, 록히드 마틴사는 장거리에서 빔 품질을 확보하기 위해 적응 광학에 의존하는 300kW급 장비 개발을 진행하고 있습니다. 우주개발청(SDA)의 ‘Proliferated Warfighter Space Architecture’ 계획에는 2029년까지 350억 달러의 예산이 편성되어 있으며, 정밀한 파면 제어가 필요한 레이저 크로스링크가 포함되어 있습니다. 오타와 대학의 TAROQQO와 같은 AI 기반 난류 예측 도구를 통해 현재 자유 공간 양자 채널의 최적화가 실시간으로 이루어지고 있습니다. 이러한 프로그램들이 결합되어 개발 주기가 단축되고, 공급망이 강화되며, 군사 및 보안 통신 용도를 위한 적응 광학 시장이 확대되고 있습니다.
액추에이터 수가 많은 변형 미러의 높은 설비 투자(CapEx)
120×120개의 액추에이터를 갖춘 변형 미러는 단가를 끌어올려, 소규모 제조업체의 경우 수익성을 확보하기 어려운 상황입니다. 게르마늄 및 갈륨의 수출 규제를 포함한 공급망 압박으로 인해 광학 기판의 원자재 가격이 상승하고 있습니다. BDNL4와 같은 대체 칼코게나이드 소재는 규제 대상 금속에 대한 의존도를 낮추지만, 생산 설비 교체가 필요해 단기적인 비용 증가로 이어집니다. 2024년에 230억 달러로 평가되는 플랫 포토닉스·레이저 시장의 침체는 공급업체가 설비 투자를 감당할 여지를 좁히고 있습니다. 이러한 요인들로 인해 가격에 민감한 수직 시장의 성장이 억제되고 있으며, 적응 광학 시장에 신규 진입을 고려 중인 기업들에게는 신중한 태도가 요구되고 있습니다.
부문 분석
2025년, 파면 센서는 적응 광학 시장의 37.45%를 차지했으며, 하류 제어 시스템에 실시간 수차 데이터를 전송하는 섀크-하트만 어레이가 핵심을 담당했습니다. 샤크-하트만 어레이는 구조가 단순하여 비용을 절감할 수 있지만, 극한 적응 광학 천문학 분야에서는 피라미드형 센서가 주목을 받고 있습니다. 제어 시스템 및 소프트웨어는 연평균 성장률(CAGR) 30.20%를 나타낼 것으로 예측됩니다. 시공간 가우스 과정 모델은 비예측 루프에 비해 파면 위상의 편차를 최대 3.5배까지 감소시킵니다. 기계적 주력 제품인 변형 미러는 소비자용 가격대에 대응하는 MEMS 아키텍처로 전환되고 있으며, 그 기술 점유율은 41.52%를 차지하고 있습니다. 팁-틸트 미러를 포함한 기타 구성 요소는 레이저 통신에서 특수한 미세 조준 작업을 수행합니다.
제어 소프트웨어에는 현재 난류 조건에서 게인 스케줄을 최적화하는 강화 학습 에이전트가 통합되어 있어, 대역폭을 유지하면서 오버슈트를 줄이고 있습니다. SPHERE사의 SAXO+ 업그레이드를 통해 테스트된 주파수 기반 데이터 구동형 컨트롤러는 볼록 최적화를 통해 시스템의 안정성을 보장합니다. 각 공급업체는 모듈형 하드웨어에 AI 지원 펌웨어를 통합하고 있으며, 이를 통해 통합 업체의 개발 주기가 단축되고 있습니다. 예측 제어가 보편화됨에 따라 제어 플랫폼용 적응 광학 시장 규모는 2031년까지 매출에서 더 큰 비중을 차지할 것으로 예측됩니다.
방위 및 보안 분야는 2025년에 매출 점유율의 31.05%를 차지할 것으로 보이며, 이는 레이저 빔의 코히어런스를 유지하기 위해 적응 광학에 의존하는 미국 국방부(DoD)의 프로그램에 힘입은 것입니다. 정부의 구매 규모는 여전히 크지만, 가장 빠른 성장이 예상되는 분야는 소비자용 전자기기 분야로, AR/VR 헤드셋 및 스마트폰 카메라에 소형 파면 변조기가 필요함에 따라 연평균 성장률(CAGR) 31.30%로 확대될 것으로 전망됩니다. 애플의 헤드마운트 디스플레이는 제조 공정에서 적응 광학에 의한 검사가 필요한 고화소 밀도의 마이크로 OLED 패널을 보급시켰습니다.
산업 제조 분야에서는 반도체 계측 라인에서 MEMS 미러가 활용되고 있으며, 검사 스테이션에서는 서브나노미터 단위의 편차를 측정하고 있습니다. 의료 및 생명과학 분야는 세포 수준의 망막 진단 플랫폼을 통해 성장세를 보이고 있으며, 적응 광학 시장의 추가적인 다각화를 촉진하고 있습니다. 연구·학술 분야에서는 메타표면 기반 파면 센서 등 혁신적인 기술 개발이 지속적으로 이루어지고 있으며, 이는 지적 재산권의 안정적인 공급원이 되고 있습니다.
지역별 분석
북미는 미국 국방부(DoD)의 10억 달러 규모의 지향성 에너지 예산과 NASA의 레이저 통신 이니셔티브를 견인력으로 삼아 2025년 매출의 37.45%를 차지했습니다. 노스롭 그루먼(Northrop Grumman)의 Xinetics와 같은 공급업체들은 여러 군종을 대상으로 니오브산 납 마그네슘 재질의 변형 미러를 공급하고 있습니다. 우주개발청(SDA)은 350억 달러 규모의 아키텍처 프로그램에서 위성 간 크로스링크를 위해 적응형 거울을 통합하고 있습니다. 대기 왜곡에 관한 캐나다의 연구는 미국의 프로그램을 보완하며, 이 두 가지가 결합되어 북미의 적응 광학 시장을 강화하고 있습니다.
아시아태평양은 일본의 ‘우주 전략 기금’이 발사 로켓 및 위성 군집 계획을 촉진하고, 중국이 우주 상황 인식 위성을 위한 광학 페이로드를 확대함에 따라 연평균 성장률(CAGR) 29.60%로 가장 빠르게 성장하는 지역입니다. 중국의 원격 감지 분야는 2033년까지 550억-680억 달러 규모로 확대될 것으로 예측되어, 정밀 광학 기기에 대한 수요를 더욱 높이고 있습니다. JAXA의 XRISM 미션에서는 적응형 미러에 의존하는 연X선 센서의 검증이 진행되고 있으며, 이는 우주 탑재 계측 장비 분야에서 해당 지역의 기술력을 보여주고 있습니다.
유럽의 대구경 망원경 및 방위 연구 컨소시엄이 지속적인 수주를 주도하고 있습니다. ESO의 ELT 조달을 통해 유럽 대륙공급업체들은 장기 계약을 확보하고 있습니다. 남미, 중동 및 아프리카은 현지 우주 프로그램이 성숙해짐에 따라 아직 발전 단계에 있지만 유망한 것으로 평가받고 있습니다. 그러나 기술 인력과 자본 예산이 제한적이기 때문에 주요 지역에 비해 도입 속도는 둔화되고 있습니다. 이러한 동향들이 맞물려, 보상광학 시장은 특정 지역에 대한 과도한 의존을 초래하지 않으면서도 여러 지역에 걸친 성장 궤도를 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, adaptive optics market size in 2026 is estimated at USD 3.76 billion, growing from 2025 value of USD 2.96 billion with 2031 projections showing USD 12.48 billion, growing at 27.10% CAGR over 2026-2031.
This report is Segmented by Component (Wavefront Sensors, Deformable Mirrors, and More), End-User (Defense, Medical, Industrial, Consumer Electronics, and More), Application (Astronomy, Ophthalmology, Laser Communication, Semiconductor, AR/VR, and More), Technology (MEMS DMs, Piezoelectric DMs, LC SLMs, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Adaptive Optics Market Trends and Insights
Rapid Adoption of Adaptive Optics for High-Resolution Retinal Imaging
Ophthalmic device makers now integrate multi-conjugate adaptive optics to capture cellular-level retinal images, enabling earlier disease detection. FDA reclassification of ultrasound cyclodestructive devices from Class III to Class II in 2024 signals a more predictable pathway for advanced imaging platforms. Alcon's Unity VCS and Unity CS clearances illustrate growing commercial readiness, while AI-powered wavefront algorithms reduce chair-time calibration. Start-ups such as Profundus Imaging are developing prototypes that widen corrected fields of view through multiple deformable mirrors. These advances lower ownership hurdles for clinics beyond major academic centers and accelerate the adaptive optics market's healthcare reach.
Deployment in Directed-Energy & Free-Space Laser Communication Programs
The U.S. Department of Defense channels more than USD 1 billion annually into high-energy laser systems, with Lockheed Martin scaling to 300 kW devices that rely on adaptive optics for beam quality over long distances. The Space Development Agency's Proliferated Warfighter Space Architecture budgets USD 35 billion through 2029, embedding laser cross-links that need precise wavefront control. AI-enabled turbulence-forecasting tools such as TAROQQO from the University of Ottawa now refine free-space quantum channels in real time. Together these programs shorten development cycles, reinforce supply chains, and enlarge the adaptive optics market for military and secure-communication uses.
High CapEx of High-Actuator Deformable Mirrors
Deformable mirrors with 120 X 120 actuators raise unit costs that small manufacturers struggle to justify. Supply chain pressures, including export restrictions on germanium and gallium, inflate raw-material pricing for optical substrates. Alternative chalcogenide materials, such as BDNL4, lower dependence on restricted metals but require re-tooling that adds near-term expenses. The flat photonics-laser market, valued at USD 23 billion in 2024, narrows suppliers' ability to absorb capital outlays. These factors trim growth in price-sensitive verticals and impose caution on prospective entrants to the adaptive optics market.
Other drivers and restraints analyzed in the detailed report include:
- Large-Aperture Telescope Upgrades (ELT, TMT)
- Commercial Semiconductor Wafer & EUV Mask Inspection
- Complex Closed-Loop Design & Calibration Skills Gap
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wavefront Sensors dominated 37.45% of the adaptive optics market share in 2025, anchored by Shack-Hartmann arrays that feed real-time aberration data to downstream controls. Shack-Hartmann's simplicity keeps cost low, while pyramid sensors gain traction for extreme adaptive optics astronomy. Control Systems & Software are projected to grow at 30.20% CAGR; spatiotemporal Gaussian process models cut wavefront phase variance by up to 3.5X versus non-predictive loops. Deformable Mirrors, the mechanical workhorses, are shifting toward MEMS architectures with 41.52% technology share that supports consumer price points. Other components, including tip-tilt mirrors, address specialized fine-pointing tasks in laser communications.
Control software now embeds reinforcement-learning agents that optimize gain schedules under turbulent conditions, reducing overshoot while preserving bandwidth. Frequency-based data-driven controllers, tested on SPHERE's SAXO+ upgrade, safeguard system stability through convex optimization. Suppliers bundle AI-ready firmware within modular hardware, shortening development cycles for integrators. As predictive control proliferates, the adaptive optics market size for control platforms is forecast to capture a larger revenue slice through 2031.
Defense & Security held 31.05% revenue share in 2025, underpinned by DoD programs that depend on adaptive optics to maintain laser-beam coherence. Government purchases remain sizable, but the fastest growth comes from Consumer Electronics, which will advance at 31.30% CAGR as AR/VR headsets and smartphone cameras require compact wavefront modulators. Apple's head-mounted displays have popularized high-pixel-density micro-OLED panels that rely on adaptive optics testing during fabrication.
Industrial Manufacturing leverages MEMS mirrors in semiconductor metrology lines, with inspection stations measuring sub-nanometer deviations. Medical & Life Sciences gain momentum from cellular-level retinal diagnosis platforms, further diversifying the adaptive optics market. Research & Academia continue to pioneer innovations such as metasurface-based wavefront sensors, ensuring a steady pipeline of intellectual property.
Complete Report Scope:
- By Component
- Wavefront Sensors
- Deformable Mirrors
- Control Systems and Software
- Others (Beam Expanders, Tip-Tilt Mirrors)
- By End-User Industry
- Defense and Security
- Medical and Life Sciences
- Industrial Manufacturing
- Consumer Electronics Brands and OEMs
- Research and Academia
- Other End-Users
- By Application
- Astronomy and Space Observation
- Ophthalmology / Retinal Imaging
- Laser Communication and Directed Energy
- Semiconductor Inspection and Metrology
- AR/VR Optical Testing
- Others (Microscopy, Free-Space Optics RandD)
- By Technology
- MEMS-Based Deformable Mirrors
- Piezoelectric (PZT) Deformable Mirrors
- Liquid-Crystal Spatial Light Modulators
- Magnetic / Voice-Coil Mirrors
- Others (Hybrid and Novel Actuation)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Gulf Co-operation Council (GCC) Countries
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America contributed 37.45% of 2025 revenue, anchored by the DoD's billion-dollar directed-energy budget and NASA laser-communications initiatives. Suppliers such as Northrop Grumman's Xinetics deliver lead-magnesium-niobate deformable mirrors for multiple military branches. The Space Development Agency integrates adaptive mirrors into satellite cross-links within its USD 35 billion architecture program. Canadian research on atmospheric distortion complements United States programs, jointly reinforcing the North American adaptive optics market.
Asia-Pacific is the fastest-growing region at 29.60% CAGR as Japan's Space Strategy Fund stimulates launch-vehicle and constellation programs, and China expands optical payloads for space-situational-awareness satellites. China's remote-sensing sector is projected to escalate toward USD 55-68 billion by 2033, magnifying demand for precision optics. JAXA's XRISM mission validates soft-X-ray sensors that depend on adaptive mirrors, illustrating regional competence in space-borne instrumentation.
Europe's large-aperture telescopes and defense research consortia drive sustained orders. ESO's procurements for the ELT secure long-term contracts for continental suppliers. South America and the Middle East & Africa are nascent but promising as local space programs mature, yet limited technical talent and capital budgets slow adoption relative to leading regions. Collectively, these dynamics keep the adaptive optics market on a multi-regional growth path without over-reliance on a single geography.
- Northrop Grumman Corp. (AOA Xinetics)
- Thorlabs Inc.
- Boston Micromachines Corp.
- ALPAO SAS
- Imagine Optics SA
- Flexible Optical B.V.
- Iris AO Inc.
- Phasics SA
- CILAS (ArianeGroup)
- Active Optical Systems
- Optos Plc
- AKA Optics SAS
- Trex Enterprises Corp.
- MKS Instruments Inc. (Newport)
- HOLOEYE Photonics AG
- Jenoptik AG
- Teledyne e2v
- Wavefront Dynamics LLC
- Physik Instrumente (PI) GmbH
- Sacher Lasertechnik GmbH
- Ophir Optronics Solutions Ltd.
- First Light Imaging SAS
- OptoCraft GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Adaptive Optics for High-Resolution Retinal Imaging in North America
- 4.2.2 Deployment in Directed-Energy and Free-Space Laser Communication Programs by U.S. DoD
- 4.2.3 Large-Aperture Telescope Upgrades (ELT, TMT) Accelerating Demand in Europe
- 4.2.4 Commercial Semiconductor Wafer and EUV Mask Inspection Requiring Sub-Nanometer Precision
- 4.2.5 Emergence of AR/VR Waveguide Display Manufacturing Using AO-Enhanced Metrology
- 4.2.6 National Space Agencies Funding for Space Debris Tracking (Asia and Middle East)
- 4.3 Market Restraints
- 4.3.1 High CapEx of High-Actuator Deformable Mirrors Limiting Wider Industrial Adoption
- 4.3.2 Complex Closed-Loop Design and Calibration Skills Gap in Emerging Markets
- 4.3.3 Long Qualification Cycles for AO-Enabled Optical Payloads in Defense Sector
- 4.3.4 Miniaturization Challenges for Consumer-Grade Modules (less than 5 mm Aperture)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Industry Value-Chain Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Wavefront Sensors
- 5.1.2 Deformable Mirrors
- 5.1.3 Control Systems and Software
- 5.1.4 Others (Beam Expanders, Tip-Tilt Mirrors)
- 5.2 By End-User Industry
- 5.2.1 Defense and Security
- 5.2.2 Medical and Life Sciences
- 5.2.3 Industrial Manufacturing
- 5.2.4 Consumer Electronics Brands and OEMs
- 5.2.5 Research and Academia
- 5.2.6 Other End-Users
- 5.3 By Application
- 5.3.1 Astronomy and Space Observation
- 5.3.2 Ophthalmology / Retinal Imaging
- 5.3.3 Laser Communication and Directed Energy
- 5.3.4 Semiconductor Inspection and Metrology
- 5.3.5 AR/VR Optical Testing
- 5.3.6 Others (Microscopy, Free-Space Optics RandD)
- 5.4 By Technology
- 5.4.1 MEMS-Based Deformable Mirrors
- 5.4.2 Piezoelectric (PZT) Deformable Mirrors
- 5.4.3 Liquid-Crystal Spatial Light Modulators
- 5.4.4 Magnetic / Voice-Coil Mirrors
- 5.4.5 Others (Hybrid and Novel Actuation)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Gulf Co-operation Council (GCC) Countries
- 5.5.5.2 Turkey
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, Funding, Partnerships)
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Northrop Grumman Corp. (AOA Xinetics)
- 6.4.2 Thorlabs Inc.
- 6.4.3 Boston Micromachines Corp.
- 6.4.4 ALPAO SAS
- 6.4.5 Imagine Optics SA
- 6.4.6 Flexible Optical B.V.
- 6.4.7 Iris AO Inc.
- 6.4.8 Phasics SA
- 6.4.9 CILAS (ArianeGroup)
- 6.4.10 Active Optical Systems
- 6.4.11 Optos Plc
- 6.4.12 AKA Optics SAS
- 6.4.13 Trex Enterprises Corp.
- 6.4.14 MKS Instruments Inc. (Newport)
- 6.4.15 HOLOEYE Photonics AG
- 6.4.16 Jenoptik AG
- 6.4.17 Teledyne e2v
- 6.4.18 Wavefront Dynamics LLC
- 6.4.19 Physik Instrumente (PI) GmbH
- 6.4.20 Sacher Lasertechnik GmbH
- 6.4.21 Ophir Optronics Solutions Ltd.
- 6.4.22 First Light Imaging SAS
- 6.4.23 OptoCraft GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


