|
시장보고서
상품코드
2123308
광섬유 시험 장비(FOTE) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Fiber Optic Test Equipment (FOTE) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 광섬유 시험 장비(FOTE) 시장 규모는 2025년에 11억 7,000만 달러로 평가되었고 2026년 12억 5,000만 달러에서 2031년까지 17억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.44%를 나타낼 전망입니다.
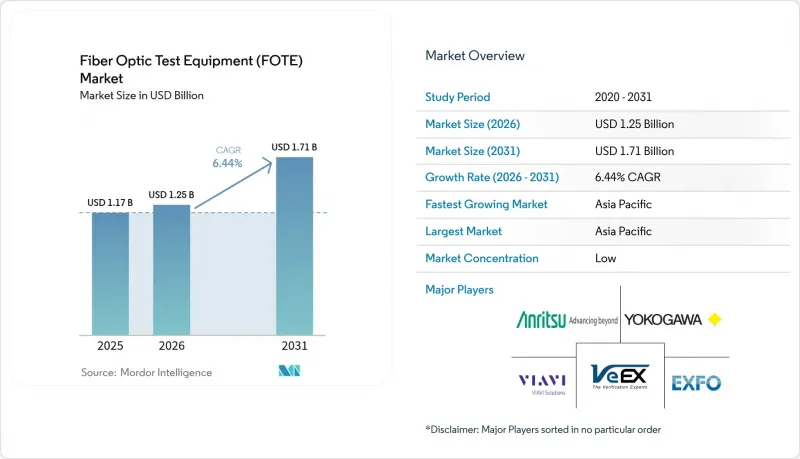
본 보고서는 장비 유형(광원, 광 파워·손실 측정기, 광 시간 영역 반사계 등), 폼 팩터(휴대용, 벤치탑형, 랙/모듈형), 광섬유 모드(싱글모드, 멀티모드), 최종 사용자(통신 서비스 제공업체 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 광섬유 시험 장비(FOTE) 시장 동향 및 인사이트
5G 프론트홀 및 백홀용 광섬유 도입 확대
5G 매크로셀 및 스몰셀 1기당 4G에 비해 광섬유 수가 10배 증가함에 따라, 10밀리초 미만의 지연,고차 변조의 무결성, 그리고 DWDM 채널 간격을 검증하는 코히런트 OTDR 플랫폼에 대한 전례 없는 수요를 유발하고 있습니다. Saudi Telecom Company는 2024년에 5G 전용 광섬유 백홀 경로를 8,035개 추가했으며, 이는 현재 Tier 1 통신 사업자들 사이에서 일상화되고 있는 인프라 구축 규모를 여실히 보여줍니다. 밀집된 도시 지역에서의 구축에서는 토목 공사로 인한 중단이 빈번하게 발생하기 때문에 서비스 수준 준수를 위해서는 자동화된 장애 지점 파악과 실시간 반사율 측정이 필수적입니다. 벤더들은 업스트림과 다운스트림을 동시에 테스트할 수 있는 듀얼 포트 설계로 이에 대응하고 있으며, 이를 통해 현장 방문 횟수를 줄이고 평균 복구 시간(MTTR)을 단축하고 있습니다. 5.5G 및 6GHz 대역의 주파수 재할당 움직임은 더 높은 대역폭의 광섬유에 대한 수요를 지속시키고 있으며, 이를 통해 통신 사업자의 전체 서비스 영역에 걸친 계측기 교체 주기를 뒷받침하고 있습니다.
신흥 경제국에서의 FTTH/B 도입 급증
공공 부문의 디지털 포용 목표가 주요 도시권을 훨씬 뛰어넘는 다국적 FTTH 확장을 뒷받침하고 있습니다. 백본 광섬유를 35,000km에서 125,000km로 확장하겠다는 나이지리아의 로드맵은 그 규모가 얼마나 큰지를 여실히 보여주고 있으며, 기술자가 최소한의 교육만으로도 조작할 수 있는 가볍고 배터리 효율이 뛰어난 측정 기기에 대한 수요가 증가하고 있습니다. BICSI의 Installer 2-Optical Fiber 교육 과정 등록자 수가 급증하고 있는데, 이는 인증 취득이 호환 가능한 시험 장비 조달을 직접 촉진하고 있음을 반영합니다. 걸프협력회의(GCC) 회원국의 현지 조달 의무로 인해, 장비 리드타임을 단축하고 서비스 물류를 현지에서 처리할 수 있는 지역 조립 파트너십이 우대받고 있습니다. 광섬유 구축이 교외 및 농촌 지역으로 확대됨에 따라, 정부 보조금과 연계된 계약상 KPI를 충족하기 위해 광 손실 측정 및 자동 단면 검사가 필수적입니다.
코히런트 지원 OTDR 및 OSA 플랫폼에 대한 고액의 설비 투자(CAPEX)
코히런트 광 시스템으로의 전환에 따라, 통신 사업자는 고가의 고속 DSP 및 초협대역 레이저를 탑재한 분석기에 투자할 수밖에 없습니다. 소규모 통신 사업자는 대여 풀이나 관리형 테스트 서비스에 의존하는 경우가 많아, 그 결과 새로운 하드웨어 조달 주기가 장기화되고 있습니다. 이러한 부담은 필수적인 교정 작업과 고도의 사용자 교육으로 인해 더욱 커져 총소유비용(TCO)을 상승시키고 있습니다. 각 벤더들은 펌웨어 업데이트, 자동 교정, AI 기반 장애 분석을 묶은 구독 모델을 시범적으로 도입하여 진입 장벽을 낮추고 있지만, 판매 대수가 증가하기 전까지는 Tier 2/3 사업자들의 가격 민감도는 여전히 지속되고 있습니다.
부문 분석
원격 광섬유 시험 시스템은 출하 대수에서 차지하는 비중이 16%에 불과하지만, 연평균 성장률(CAGR) 7.98%를 기록하며 가장 빠르게 성장하는 카테고리가 되었습니다. 통신 사업자들은 작업자를 파견하지 않고도 수천 킬로미터에 걸친 장애를 파악할 수 있는 이 기능을 높이 평가하고 있으며, 이는 생산성 지표 향상과 네트워크 가용성 향상으로 이어지고 있습니다. 그럼에도 불구하고, 광 파워 및 손실 측정기는 2025년에도 광섬유 시험 장비 시장에서 28.95%의 점유율을 유지하고 있으며, 초기 설치 및 정기 인증 분야에서 그 보급률이 두드러지고 있습니다. EXFO의 OTH-7000은 측정 패킷을 통신 사업자의 OSS 제품군으로 스트리밍하는 클라우드 API를 도입했는데, 이 기능은 분석 구독의 업셀링을 목표로 하는 경쟁사들에 의해서도 모방되고 있습니다.
자동화로의 전환은 원격 모니터링 노드와 수정 작업용 핸드헬드 키트를 세트로 구성한 조달 프레임워크에서 더욱 두드러지고 있습니다. SLA 벌칙이 엄격해지는 가운데, 통신 사업자들은 메트로 링이나 장거리 회선 자산 모두에서 실시간 OTDR 스캔이 필수적이라고 생각합니다. 스펙트럼 분석기에 통합된 DWDM 채널 분석 기능은 400G 및 800G 도입이 가속화되고 있는 지역에서 지지를 얻고 있는 반면, 시각적 장애 위치 파악 장치는 문제 티켓 시스템에 이미지를 자동으로 첨부하는 스마트폰 앱 제어형 장치로 진화하고 있습니다.
2025년에도 핸드헬드형 제품 시장 점유율은 51.45%를 유지했습니다. 이는 현장 작업자가 여전히 장애 파악 및 인수 시험의 최전선을 담당하고 있기 때문입니다. 기술자가 여러 거점에서 업무를 수행하는 동안 여러 측정기를 동시에 다뤄야 하기 때문에 무게 1kg 미만 및 8시간의 배터리 구동 시간은 이제 기본 사양이 되었습니다. 한편, 랙/모듈형은 하이퍼스케일 사업자가 톱 오브 랙 스위치에 테스트 블레이드를 직접 통합하여 상시 가시성을 실현하고 있는 데 힘입어 연평균 성장률(CAGR) 7.62%로 확대되고 있습니다. 이 방식은 오케스트레이션 소프트웨어가 예방적인 광섬유 청소 및 경로 변경을 촉발하는 폐쇄 루프 자동화를 뒷받침합니다.
벤치탑형 시스템은 휴대성보다 측정 동적 범위 및 스펙트럼 충실도가 중시되는 제조 및 연구 개발(R&D) 환경을 위해 제공됩니다. 안리츠의 μOTDR 모듈은 이러한 소형화 추세를 구현한 것으로, PXI 섀시에 통합되어 OEM 제조업체에 인라인 생산 테스트 기능을 제공합니다. 각 벤더들은 폼 팩터에 관계없이 공통 펌웨어를 채택하는 경향이 강해지고 있으며, 이를 통해 기업은 디바이스 등급에 관계없이 단일 분석 콕핏을 활용할 수 있게 되어, 운영자의 숙련 기간 단축 및 지원 부담 경감으로 이어지고 있습니다.
지역별 분석
2025년, 아시아태평양은 광섬유 시험 장비 시장 규모에 4억 5,000만 달러를 기여했습니다. 이는 중국, 일본, 한국 등 시장의 끊임없는 백본 네트워크 확장과 GPON에서 10G PON으로의 전환을 반영한 것입니다. 지역 내 제조 역량을 통해 신속한 맞춤화가 가능한 반면, 국가 안보 지침에 따라 국내 생산 광 장비로의 조달 경향이 강해지고 있습니다. 아세안(ASEAN) 국가에서는 디지털 경제 정책에 따라 FTTH 보급 범위가 확대되고, 휴대용 OTDR 판매가 촉진되면서 수요가 더욱 증가하고 있습니다. 일본 연구 기관과 한국 공공기관 간의 학술적 협력을 통해 코히런트 플러그어블(coherent pluggable) 등의 혁신이 가속화되고 있으며, 고정밀 측정 벤치에 대한 지역 수요가 유지되고 있습니다.
중동 및 아프리카은 2025년 시장 규모가 9,000만 달러에 그치지만, 안전하고 대용량의 백본을 필요로 하는 기가 프로젝트를 배경으로 연평균 성장률(CAGR) 7.88%라는 지역 내 가장 높은 성장률을 기록하고 있습니다. Saudi Telecom Company의 ORYX 지상 시스템만 해도 수백 킬로미터에 달하는 광섬유 경로가 구축되어 있으며, 이를 위해서는 지속적인 모니터링 플랫폼과 견고한 검사용 스코프가 필수적입니다. 걸프 지역 통신 사업자들은 50G PON 시범 프로젝트와 400G 전송을 결합하여, 통합된 사용자 인터페이스(UI)를 통해 액세스 회선 및 장거리 회선 테스트를 지원할 수 있는 듀얼 모드 분석기에 대한 하류 수요를 창출하고 있습니다. 신흥 아프리카 시장은 나이지리아의 전국 백본 구축 목표를 참고하여, 장비 OEM 제조업체와 협력하여 테스트 리드 및 어댑터와 같은 소모품에 대한 맞춤형 교육 및 현지화를 추진하고 있습니다.
북미와 유럽은 코히런트 지원 OTDR 및 광 스펙트럼 분석 분야에서 기술적 리더십을 유지하고 있으며, 2025년에는 시험 장비에 총 4억 7,000만 달러를 지출할 것으로 예측됩니다. 미국에서는 연방 정부의 보조금을 통해 ‘Build America, Buy America’ 기준을 충족하는 장비 구매가 장려되고 있으며, 국내에서 조립을 수행하는 공급업체가 우대받고 있습니다. 유럽연합(EU)의 에너지 효율이 높은 데이터센터 추진은 실시간 전력 소비 데이터를 오케스트레이션 스택으로 전송하는 랙 내 모니터링 모듈에 대한 새로운 수요를 창출하고 있습니다. 한편, 남미의 통신 사업자들은 대량 구매를 통한 할인 및 물류 공유를 확보하기 위해 공동 조달을 진행하고 있으며, 이러한 동향은 수입 관세 부담을 경감시켜 주는 모듈형 멀티밴드 테스터에 유리하게 작용하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액, 10억 달러)
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the fiber optic test equipment market size was valued at USD 1.17 billion in 2025 and estimated to grow from USD 1.25 billion in 2026 to reach USD 1.71 billion by 2031, at a CAGR of 6.44% during the forecast period (2026-2031).
This report is Segmented by Equipment Type (Optical Light Sources, Optical Power & Loss Meters, Optical Time-Domain Reflectometers, and More), Form Factor (Hand-Held, Benchtop, Rack/Module-based), Fiber Mode Tested (Single-Mode, Multi-Mode), End-User Application (Telecommunications Service Providers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Fiber Optic Test Equipment (FOTE) Market Trends and Insights
Proliferation of 5G Fronthaul and Backhaul Fiber Deployment
Each standalone 5G macro or small cell multiplies fiber strands tenfold compared with 4G, triggering unprecedented demand for coherent OTDR platforms that validate sub-10 ms latency, high-order modulation integrity, and DWDM channel spacing. Saudi Telecom Company added 8,035 dedicated fiber backhaul routes for 5G in 2024, illustrating the infrastructure intensity now routine among Tier-1 operators. Dense urban builds face frequent civil-works disruptions, making automated fault-localization and real-time reflectometry indispensable for service-level compliance. Equipment vendors answer with dual-port designs that support simultaneous upstream and downstream testing, reducing truck rolls and accelerating mean-time-to-repair. The push toward 5.5G and even 6 GHz spectrum refarming sustains the need for higher-bandwidth fiber, thereby underpinning test-instrument replacement cycles across operator footprints.
Explosion of FTTH/B Roll-outs in Emerging Economies
Public-sector digital-inclusion targets are fueling multi-country FTTH extensions well beyond primary metros. Nigeria's roadmap to stretch backbone fiber from 35,000 km to 125,000 km underscores the scale, demanding lightweight, battery-efficient meters technicians can operate after minimal training. Enrollment in BICSI's Installer 2-Optical Fiber curriculum has surged, reflecting how certification uptake directly boosts procurement of compatible test gear. Local-content mandates in Gulf Cooperation Council economies reward regional assembly partnerships that keep device lead times short and service logistics local. As fiber footprints permeate suburban and rural clusters, optical loss and automated end-face inspection become mandatory to meet contractual KPIs tied to government subsidies.
High CAPEX for Coherent-Ready OTDR and OSA Platforms
Transitioning to coherent optical systems obliges operators to invest in analyzers containing costly high-speed DSPs and ultra-narrow-linewidth lasers. Smaller carriers often resort to rental pools or managed-test services, elongating procurement cycles for new hardware. The burden is magnified by mandatory calibration routines and advanced user training that compound total cost of ownership. Vendors experiment with subscription models that bundle firmware updates, automated calibration, and AI fault-analytics to lower entry barriers, but price sensitivity among Tier-2/3 players persists until unit volumes rise.
Other drivers and restraints analyzed in the detailed report include:
- Government Stimulus for Rural Broadband and Power-Grid Digitalization
- Shift to PAM4 and 800 G Optics in Hyperscale Data Centers
- Shortage of Certified Fiber Technicians in Tier-2/3 Cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Remote fiber test systems, though only 16% of shipments, posted an 7.98% CAGR to become the fastest-expanding category. Operators prize their ability to localize faults across thousands of kilometers without dispatching crews, elevating productivity metrics and boosting network availability. Optical power and loss meters nonetheless retained a 28.95% fiber optic test equipment market share in 2025, underscoring their ubiquity during initial installation and periodic certification. EXFO's OTH-7000 introduced cloud APIs that stream measurement packets into operator OSS suites, a capability replicated by rivals aiming to upsell analytics subscriptions.
The pivot toward automation is even clearer in procurement frameworks that now bundle remote monitoring nodes with hand-held kits for corrective work. As SLA penalties tighten, carriers consider real-time OTDR sweeps indispensable for metro rings and long-haul assets alike. Integrated DWDM channel analysis inside spectrum analyzers wins favor in regions where 400 G and 800 G deployments accelerate, while visual fault locators evolve into smartphone-app-controlled devices that auto-attach images to trouble-ticket systems.
Hand-held testers maintained a 51.45% stake in 2025 because field crews still constitute the frontline of fault isolation and acceptance testing. Weight reduction below 1 kg and eight-hour battery lives are now baseline specifications as technicians juggle multiple instruments during multi-site assignments. The rack/module-based class, however, is expanding at a 7.62% CAGR, propelled by hyperscale operators embedding test blades directly into top-of-rack switches to deliver always-on visibility. This practice supports closed-loop automation where orchestration software triggers pre-emptive fiber cleaning or rerouting.
Benchtop systems serve manufacturing and RandD environments where measurement dynamic range and spectral fidelity trump portability. Anritsu's μOTDR module exemplifies miniaturization trends, slotting into PXI chassis to furnish OEMs with in-line production tests. Vendors increasingly adopt common firmware across form factors, allowing enterprises to leverage a single analytics cockpit regardless of device class, thereby reducing operator learning curves and support effort.
Complete Report Scope:
- By Equipment Type
- Optical Light Sources
- LED Sources
- Laser Sources
- Optical Power and Loss Meters
- Optical Time-Domain Reflectometers
- Optical Spectrum Analyzers
- Remote Fiber Test Systems
- Others (Inspection Microscopes, VFL, etc.)
- Optical Light Sources
- By Form Factor
- Hand-held
- Benchtop
- Rack/Module-based
- By Fiber Mode Tested
- Single-mode
- Multi-mode
- By End-user Application
- Telecommunications Service Providers
- Hyperscale and Enterprise Data Centers
- Industrial and Manufacturing
- Energy and Utilities (Smart-grid, Oil and Gas)
- Government and Defense
- Others (Broadcast, Healthcare, RandD)
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- North America
Geography Analysis
Asia-Pacific contributed USD 0.45 billion to the fiber optic test equipment market size in 2025, reflecting unrelenting backbone expansion and the migration from GPON to 10G PON in markets such as China, Japan, and South Korea. Regional manufacturing capacity allows quick-turn customization, while national-security directives tilt procurement toward domestically produced optics. ASEAN countries add incremental demand as digital-economy policies broaden FTTH coverage, catalyzing hand-held OTDR sales. Academic collaboration between research labs in Japan and public institutes in South Korea accelerates innovations like coherent pluggables, sustaining local demand for high-precision measurement benches.
Middle East and Africa, though accounting for just USD 0.09 billion in 2025, registers the highest regional growth at 7.88% CAGR on the back of giga-projects requiring secure, high-capacity backbones. Saudi Telecom Company's ORYX terrestrial system alone contributes hundreds of fiber-route-kilometers that mandate continuous monitoring platforms and ruggedized inspection scopes. Gulf operators pair 50G PON pilots with 400 G transport, creating downstream demand for dual-mode analyzers able to handle access and long-haul tests using a unified UI. Emerging African markets take cues from Nigeria's national backbone targets, collaborating with equipment OEMs for tailored training and localization of consumables such as test leads and adaptors.
North America and Europe retain technological leadership in coherent-ready OTDR and optical-spectrum-analysis, collectively spending USD 0.47 billion on test gear in 2025. Federal grants in the United States incentivize purchase of devices that pass Build America, Buy America criteria, favoring vendors with domestic assembly. The European Union's push for energy-efficient data centers triggers fresh demand for in-rack monitoring modules that feed real-time power-consumption data to orchestration stacks. South American carriers, meanwhile, pool procurement to secure volume discounts and shared logistics, a trend benefiting modular, multi-band testers that alleviate import-duty burdens.
- EXFO Inc.
- VIAVI Solutions Inc.
- Anritsu Corporation
- Yokogawa Electric Corporation
- AFL Global (Fujikura)
- Fluke Networks
- Keysight Technologies
- VeEX Inc.
- Kingfisher International
- Tektronix (Fortive)
- Deviser Instruments
- Trend Communications
- Corning Inc.
- Photon Kinetics
- Terahertz Technologies
- GAO Tek
- OptoTest
- Luna Innovations
- Tempo Communications
- VI-Systems GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of 5G fronthaul and backhaul fiber deployment
- 4.2.2 Explosion of FTTH/B roll-outs in emerging economies
- 4.2.3 Government stimulus for rural broadband and power grid digitalization
- 4.2.4 Shift to PAM4 and 800 G optics in hyperscale data centers
- 4.2.5 Defense adoption of tactical ruggedized fiber links
- 4.2.6 Growing need for automated, AI-driven remote fiber test systems (under-reported)
- 4.3 Market Restraints
- 4.3.1 High CAPEX for coherent-ready OTDR and OSA platforms
- 4.3.2 Shortage of certified fiber technicians in Tier-2/3 cities
- 4.3.3 Displacement by integrated DSP-based self-test in transceiver modules (under-reported)
- 4.3.4 Geo-political export controls on advanced photonic components (under-reported)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of COVID-19 and Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD BN)
- 5.1 By Equipment Type
- 5.1.1 Optical Light Sources
- 5.1.1.1 LED Sources
- 5.1.1.2 Laser Sources
- 5.1.2 Optical Power and Loss Meters
- 5.1.3 Optical Time-Domain Reflectometers
- 5.1.4 Optical Spectrum Analyzers
- 5.1.5 Remote Fiber Test Systems
- 5.1.6 Others (Inspection Microscopes, VFL, etc.)
- 5.1.1 Optical Light Sources
- 5.2 By Form Factor
- 5.2.1 Hand-held
- 5.2.2 Benchtop
- 5.2.3 Rack/Module-based
- 5.3 By Fiber Mode Tested
- 5.3.1 Single-mode
- 5.3.2 Multi-mode
- 5.4 By End-user Application
- 5.4.1 Telecommunications Service Providers
- 5.4.2 Hyperscale and Enterprise Data Centers
- 5.4.3 Industrial and Manufacturing
- 5.4.4 Energy and Utilities (Smart-grid, Oil and Gas)
- 5.4.5 Government and Defense
- 5.4.6 Others (Broadcast, Healthcare, RandD)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Russia
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 EXFO Inc.
- 6.4.2 VIAVI Solutions Inc.
- 6.4.3 Anritsu Corporation
- 6.4.4 Yokogawa Electric Corporation
- 6.4.5 AFL Global (Fujikura)
- 6.4.6 Fluke Networks
- 6.4.7 Keysight Technologies
- 6.4.8 VeEX Inc.
- 6.4.9 Kingfisher International
- 6.4.10 Tektronix (Fortive)
- 6.4.11 Deviser Instruments
- 6.4.12 Trend Communications
- 6.4.13 Corning Inc.
- 6.4.14 Photon Kinetics
- 6.4.15 Terahertz Technologies
- 6.4.16 GAO Tek
- 6.4.17 OptoTest
- 6.4.18 Luna Innovations
- 6.4.19 Tempo Communications
- 6.4.20 VI-Systems GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment