

|
시장보고서
상품코드
2123310
밸브 및 액추에이터 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Valves And Actuators - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 밸브 및 액추에이터 시장 규모는 2026년에 759억 달러가 되어, 2031년까지 연평균 복합 성장률(CAGR) 7.34%로 1,081억 5,000만 달러에 이를 것으로 예측됩니다.
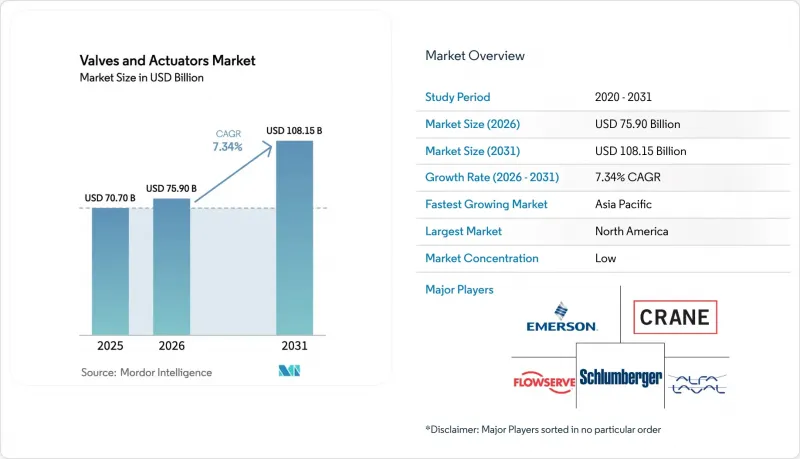
본 보고서는 밸브 제품 유형(볼 밸브, 버터플라이 밸브, 게이트/글로브/체크 밸브 등), 액추에이터 유형(유압식, 공압식, 전동식 등), 최종 이용 산업(석유 및 가스,발전, 화학제품 및 석유화학제품 등), 재질(스테인리스 스틸, 탄소강, 합금계, 주철 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 밸브 및 액추에이터 시장 동향과 인사이트
인더스트리 4.0에 대응하는 스마트 밸브 및 액추에이터의 급속한 보급
사업자들은 토크 편차나 씰 마모를 감지하기 위해 밸브 어셈블리에 엣지 프로세서나 무선 센서를 통합하고 있으며, 이를 통해 사후 대응형 유지보수에서 상태 모니터링형 프로그램으로 전환함으로써 정유시설의 가동 중단 시간을 하루당 50만 달러 상당 줄이고 있습니다. Emerson의 Fisher FIELDVUE DVC7K 디지털 컨트롤러는 진동 특성을 포착하는 반면, Siemens 및 ABB의 유사한 포지셔너는 HART 및 PROFIBUS를 통해 레거시 DCS 플랫폼과 통신합니다. 에너지 수확 모듈을 통해 배터리 없이도 진단 기능에 전력을 공급할 수 있게 되어, 외딴 지역의 파이프라인 회랑에서 총 소유 비용을 절감하고 있습니다. ISO 50001 준수에 따라 스마트 공압 장비의 도입이 가속화되고 있습니다. 이는 공기 소비량을 15%-20% 절감할 수 있기 때문입니다. 그 결과로 인한 생산성 향상은 밸브 및 액추에이터 시장의 연평균 성장률(CAGR)에 1.4%의 긍정적 영향을 미치고 있습니다.
전 세계 해수 담수화 능력 확대
중동의 유틸리티자들은 물 부족을 완화하기 위해 역삼투법을 활용한 메가 프로젝트를 발주하고 있으며, 2028년까지 총 1,200만 m³/일의 처리 용량이 추가될 전망입니다. 예를 들어, 두바이의 하얌(Hassyan) 플랜트에서는 염수 분무 부식에 대한 IP68 보호 등급을 갖춘 전동 버터플라이 밸브가 채택되었습니다. 이집트와 알제리의 유사한 프로젝트들도 이러한 사양을 따르고 있어, 밸브 및 액추에이터 시장을 뒷받침하는 듀플렉스강 볼 밸브와 니켈-알루미늄-청동 합금의 안정적인 수주 전망을 뒷받침하고 있습니다.
기존 석유 및 가스 정제 분야의 설비 투자 장기적 둔화
대형 종합 기업들은 재생 가능 연료 및 탄소 포집 기술로 자본을 전환하고 있으며, 2025년에는 정유시설 프로젝트가 전년 대비 12% 감소할 전망입니다. 유동 접촉 분해(FCC) 설비의 업그레이드가 연기됨에 따라 고온용 게이트 밸브 및 글로브 밸브에 대한 단기 수주가 사라져, 탄화수소 사이클에 의존하는 공급업체의 이익률이 압박받고 있습니다. 각 공급업체들은 애프터마켓 서비스 및 디지털화를 통한 개조 사업으로 전환하고 있지만, 이러한 침체로 인해 밸브 및 액추에이터 시장의 연평균 성장률(CAGR)은 0.9% 하락했습니다.
부문 분석
2025년, 볼 밸브는 밸브 및 액추에이터 시장의 28.73%를 차지했습니다. 이는 1/4 회전이라는 간편함과, 유정 격리에 필수적인 기포 누출이 없는 차단 성능이 높이 평가된 결과입니다. 또한, 주목을 받은 과압 사고를 계기로 석유화학 단지가 API 520 규격에 부합하는 설계로 업그레이드를 추진함에 따라, 압력 방출 밸브 및 안전 밸브는 2031년까지 연평균 8.21%의 성장이 예상됩니다.
제품 라인업은 API 607 내화 규격이나 BS 6364 극저온 규격과 같은 틈새 인증으로 세분화가 진행되고 있으며, 여러 시험 장비를 도입할 자금을 조달할 수 있는 기업을 중심으로 공급업체 기반이 재편되고 있습니다. 제어용 밸브와 버터플라이 밸브는 해수 담수화 및 HVAC 네트워크 분야에서 점유율을 확대하고 있는 반면, 슬러리 처리 용도에서의 플러그 밸브 채택은 칠레의 광미 댐에서 인도네시아의 보크사이트 광산으로 확대되고 있습니다. 이러한 변화가 밸브 및 액추에이터 시장의 성장세를 유지하고 있습니다.
2025년에는 공압식 액추에이터가 매출 점유율 37.63%로 1위를 차지하며, 폭발성 구역에서의 본질 안전성과 기존 에어 루프와의 호환성이 높이 평가받고 있습니다. 그러나 자산 성능 관리 소프트웨어를 통해 스트로크 수와 토크 프로파일을 실시간으로 추적할 수 있게 됨에 따라, 스마트 전동 모델 시장은 연평균 성장률(CAGR) 8.44%로 급속히 확대되고 있습니다.
에너지 감사를 통해 압축 공기 비용이 주목받고 있는 수도 유틸리티 분야에서는 전동 유닛이 공압식을 대체하고 있지만, 완전 전동 시스템이 보급되기 전까지는 해저 생산 설비(서브시 트리)에서 유압식 설계가 여전히 자리 잡고 있습니다. 진동 에너지를 회수하여 탑재된 센서에 전력을 공급하는 ABB의 MotorSense 액추에이터는 비용 절감으로 이어지는 혁신 기술의 한 예입니다. 이러한 양극화가 밸브 및 액추에이터 시장에서 건전한 경쟁을 유지하고 있습니다.
지역별 분석
북미는 2025년 전 세계 매출의 38.73%를 차지하며 계속해서 주도적인 위치를 유지했습니다. 이는 셰일가스 개발의 수익화와 멕시코만 연안의 LNG 프로젝트로 인해 총 50만 개에 달하는 밸브가 필요했기 때문입니다. 설치된 설비를 대상으로 한 서비스가 지역 매출의 거의 절반을 차지하고 있어, 프로젝트가 정체된 시기에도 공급업체를 보호하는 역할을 하고 있습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.55%를 나타낼 것으로 예측됩니다. 이는 중국의 석탄 화학 복합 시설이나 인도의 스마트 시티용 상수도망과 같은 동향에 힘입은 것으로, 이러한 동향이 해당 지역의 밸브 및 액추에이터 시장 규모를 꾸준히 끌어올릴 것입니다.
유럽의 밸브 수요는 확장보다는 교체가 주된 요인으로 작용하고 있습니다. 이는 산업 배출 지침에 따라 화학 플랜트가 6개월마다 저배출형 스템으로 개조해야 할 의무가 있기 때문입니다. 그러나 정유시설는 폐쇄되거나 바이오연료로 전환되면서 대구경 차단 밸브의 수주는 감소하고 있습니다. 남미에서는 브라질의 프레솔트 유전이나 아르헨티나의 바카 무에르타 파이프라인과 관련하여 일시적인 수요 급증이 나타나고 있지만, 지방자치단체의 상수도 관련 지출은 재정적 역풍으로 인해 여전히 억제되고 있습니다.
중동 및 아프리카는 해수 담수화 및 석유화학 메가 프로젝트에 크게 의존하고 있습니다. 높은 염분 농도의 급수로 인해 버터플라이 밸브의 수명이 5-7년으로 단축되므로, 안정적인 애프터마켓이 보장됩니다. 나이지리아의 단고테 정유시설나 이집트의 졸 가스전은 대규모 조달의 선례가 되고 있지만, 지역 유통망은 여전히 성숙 단계에 있습니다. 이러한 지역별 동향이 어우러져 밸브 및 액추에이터 시장의 장기적인 성장 전망을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the valves and actuators market size stood at USD 75.9 billion in 2026 and is projected to reach USD 108.15 billion by 2031 at a 7.34% CAGR.
This report is Segmented by Valve Product Type (Ball, Butterfly, Gate/Globe/Check, and More), Actuator Type (Hydraulic, Pneumatic, Electric, and More), End-Use Industry (Oil and Gas, Power Generation, Chemical and Petrochemical, and More), Material (Stainless Steel, Carbon Steel, Alloy-Based, Cast Iron, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Valves And Actuators Market Trends and Insights
Rapid Adoption of Industry 4.0-Enabled Smart Valves and Actuators
Operators are embedding edge processors and wireless sensors in valve assemblies to detect torque deviations and seal wear, converting reactive maintenance into condition-based programs that cut refinery downtime worth USD 500,000 per day. Emerson's Fisher FIELDVUE DVC7K digital controller captures vibration signatures, while similar positioners from Siemens and ABB communicate over HART and PROFIBUS to legacy DCS platforms. Energy-harvesting modules now power diagnostics without the need for batteries, thereby lowering ownership costs in remote pipeline corridors. Compliance with ISO 50001 is accelerating the adoption of smart pneumatics, as they can reduce air consumption by 15%-20%. The resulting productivity gains reinforce the positive 1.4% impact on the Valves and actuators market CAGR.
Expansion of Global Desalination Capacity
Middle Eastern utilities are contracting reverse-osmosis megaprojects to ease water scarcity, adding a combined 12 million m3-per-day capacity by 2028. Dubai's Hassyan plant, for example, specified motorized butterfly valves with IP68 protection against salt-spray corrosion. Similar projects in Egypt and Algeria mirror these specifications, reinforcing a steady pipeline for duplex-steel ball valves and nickel-aluminum-bronze alloys that support the Valves and actuators market.
Prolonged CAPEX Slowdown in Conventional Oil and Gas Refining
Integrated majors are diverting capital toward renewable fuels and carbon capture, reducing refinery projects by 12% year-on-year in 2025. Deferred fluid catalytic cracking upgrades eliminate near-term orders for high-temperature gate and globe valves, squeezing margins for suppliers tied to the hydrocarbon cycle. Vendors are pivoting to aftermarket services and digital retrofits, yet the chill subtracts 0.9% from the Valves and actuators market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- LNG Infrastructure Build-Out
- Retrofit Demand From Fugitive-Emission Rules
- Supply-Chain Bottlenecks for Castings and Forgings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ball valves accounted for 28.73% of the Valves and actuators market in 2025, highlighting their quarter-turn simplicity and bubble-tight shutoff, which is essential for wellhead isolation. Pressure relief and safety valves are forecast to grow at a rate of 8.21% through 2031, as petrochemical complexes upgrade to API 520 designs following high-profile overpressure incidents.
The product spectrum is splintering into niche certifications such as API 607 fire-safe and BS 6364 cryogenic approvals, consolidating supplier bases around firms that can finance multiple test rigs. Control and butterfly valves are gaining ground in desalination and HVAC networks, while plug-valve adoption in slurry services spreads from Chilean tailings dams to Indonesian bauxite mines. These shifts preserve the momentum of the Valves and actuators market.
Pneumatic actuators led with 37.63% revenue share in 2025, favored for intrinsic safety in explosive zones and compatibility with existing air loops. Smart electric models, however, are accelerating at an 8.44% CAGR as asset-performance software tracks stroke counts and torque profiles in real time.
Electric units are displacing pneumatics in water utilities where energy audits spotlight compressed-air costs, while hydraulic designs remain entrenched in subsea trees until all-electric systems scale. ABB's MotorSense actuator, which harvests vibration energy to power onboard sensors, exemplifies cost-saving innovation. This bifurcation sustains healthy competition within the Valves and actuators market.
Complete Report Scope:
- By Valve Product Type
- Ball
- Butterfly
- Gate/Globe/Check
- Plug
- Control
- Pressure Relief / Safety
- Other Valve Product Types
- By Actuator Type
- Hydraulic
- Pneumatic
- Electric
- Electro-hydraulic
- Mechanical
- Smart / Intelligent
- Other Actuator Types
- By End-Use Industry
- Oil and Gas
- Power Generation
- Chemical and Petrochemical
- Water and Wastewater
- Mining and Metals
- Pharmaceuticals
- Food and Beverage
- Pulp and Paper
- HVAC and Building Services
- Marine and Shipbuilding
- Other End-Use Industries
- By Material
- Stainless Steel
- Carbon Steel
- Alloy-based (Duplex, Inconel, etc.)
- Cast Iron
- Plastic and Composite
- Cryogenic-service Materials
- Other Materials
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained leadership in 2025 with 38.73% of global revenue as shale play monetization and Gulf Coast LNG projects collectively required up to 500,000 valves. Installed-base services generate nearly half of regional turnover, cushioning suppliers from project lulls. Asia Pacific is forecast to register an 8.55% CAGR through 2031, propelled by China's coal-to-chemicals complexes and India's smart-city water grids, trends that will steadily lift the Valves and actuators market size in the region.
Europe's valve demand is driven more by replacement than expansion as the Industrial Emissions Directive compels chemical plants to retrofit low-emission stems every six months. Refineries, however, are shuttering or converting to biofuels, trimming orders for large-bore isolation valves. South America shows episodic spikes tied to Brazil's pre-salt fields and Argentina's Vaca Muerta pipelines, yet municipal water spending remains constrained by fiscal headwinds.
The Middle East and Africa rely heavily on desalination and petrochemical megaprojects. High-salinity feedwater cuts butterfly-valve life cycles to five-seven years, guaranteeing a steady aftermarket. Nigeria's Dangote refinery and Egypt's Zohr gas field have set precedents for large-scale procurement, though regional distributor networks are still maturing. These geographic dynamics collectively reinforce long-term growth prospects for the Valves and actuators market.
- Emerson Electric Co.
- Schlumberger Limited
- Alfa Laval AB
- Flowserve Corporation
- Crane Company
- Rotork plc
- Metso Corporation
- KITZ Corporation
- IMI plc
- Samson AG
- Honeywell International Inc.
- Danfoss A/S
- Burkert GmbH and Co. KG
- Neway Valve (Suzhou) Co., Ltd.
- CIRCOR International, Inc.
- KSB SE and Co. KGaA
- Velan Inc.
- Spirax-Sarco Engineering plc
- General Electric Company
- ABB Ltd
- Siemens AG
- Curtiss-Wright Corporation
- Pentair plc
- Yokogawa Electric Corporation
- AVK Holding A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid adoption of Industry 4.0-enabled smart valves and actuators
- 4.2.2 Expansion of global desalination capacity, especially in MENA
- 4.2.3 LNG infrastructure build-out in North America and APAC
- 4.2.4 Retrofit demand driven by fugitive-emission regulations
- 4.2.5 Shift to all-electric subsea production systems
- 4.2.6 Hydrogen-ready valve designs for green-H2 projects
- 4.3 Market Restraints
- 4.3.1 Prolonged CAPEX slowdown in conventional OandG refining
- 4.3.2 Supply-chain bottlenecks for castings and forgings
- 4.3.3 Skills gap in digital valve commissioning and maintenance
- 4.3.4 Cyber-hardening costs for connected flow-control assets
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Valve Product Type
- 5.1.1 Ball
- 5.1.2 Butterfly
- 5.1.3 Gate/Globe/Check
- 5.1.4 Plug
- 5.1.5 Control
- 5.1.6 Pressure Relief / Safety
- 5.1.7 Other Valve Product Types
- 5.2 By Actuator Type
- 5.2.1 Hydraulic
- 5.2.2 Pneumatic
- 5.2.3 Electric
- 5.2.4 Electro-hydraulic
- 5.2.5 Mechanical
- 5.2.6 Smart / Intelligent
- 5.2.7 Other Actuator Types
- 5.3 By End-Use Industry
- 5.3.1 Oil and Gas
- 5.3.2 Power Generation
- 5.3.3 Chemical and Petrochemical
- 5.3.4 Water and Wastewater
- 5.3.5 Mining and Metals
- 5.3.6 Pharmaceuticals
- 5.3.7 Food and Beverage
- 5.3.8 Pulp and Paper
- 5.3.9 HVAC and Building Services
- 5.3.10 Marine and Shipbuilding
- 5.3.11 Other End-Use Industries
- 5.4 By Material
- 5.4.1 Stainless Steel
- 5.4.2 Carbon Steel
- 5.4.3 Alloy-based (Duplex, Inconel, etc.)
- 5.4.4 Cast Iron
- 5.4.5 Plastic and Composite
- 5.4.6 Cryogenic-service Materials
- 5.4.7 Other Materials
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Emerson Electric Co.
- 6.4.2 Schlumberger Limited
- 6.4.3 Alfa Laval AB
- 6.4.4 Flowserve Corporation
- 6.4.5 Crane Company
- 6.4.6 Rotork plc
- 6.4.7 Metso Corporation
- 6.4.8 KITZ Corporation
- 6.4.9 IMI plc
- 6.4.10 Samson AG
- 6.4.11 Honeywell International Inc.
- 6.4.12 Danfoss A/S
- 6.4.13 Burkert GmbH and Co. KG
- 6.4.14 Neway Valve (Suzhou) Co., Ltd.
- 6.4.15 CIRCOR International, Inc.
- 6.4.16 KSB SE and Co. KGaA
- 6.4.17 Velan Inc.
- 6.4.18 Spirax-Sarco Engineering plc
- 6.4.19 General Electric Company
- 6.4.20 ABB Ltd
- 6.4.21 Siemens AG
- 6.4.22 Curtiss-Wright Corporation
- 6.4.23 Pentair plc
- 6.4.24 Yokogawa Electric Corporation
- 6.4.25 AVK Holding A/S
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


