

|
시장보고서
상품코드
2123318
5G 연결 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)5G Connection - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
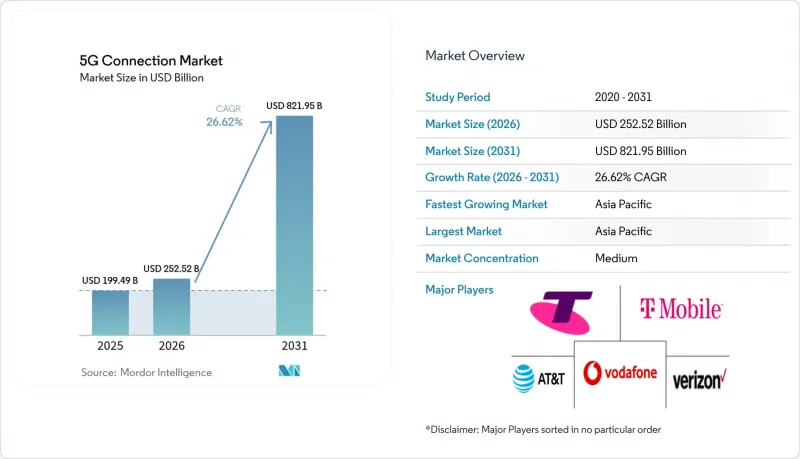
에 의하면, 5G 연결 시장 규모는 2025년에 1,994억 9,000만 달러로 평가되었고 2026년 2,525억 2,000만 달러에서 2031년까지 8,219억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 26.62%를 나타낼 전망입니다.
본 보고서는 연결 유형(모바일 브로드밴드, 고정 무선 액세스 등), 최종 사용자(소비자 및 기업), 주파수 대역(Sub-1GHz, 1-6GHz, 기타),네트워크 아키텍처(비스탠드얼론 및 스탠드얼론), 기기 카테고리(스마트폰 및 태블릿, FWA CPE, 기타), 서비스 유형(확장 모바일 브로드밴드(eMBB), 대규모 머신 유형 통신(mMTC), 기타), 지역별로 분류되어 있습니다.
전 세계 5G 연결 시장 동향 및 인사이트
모바일 데이터 트래픽의 급증으로 인해 대용량 네트워크가 요구되고 있습니다.
클라우드 게임 및 확장 현실(XR) 서비스에 힘입어 5G 회선 1회선당 월간 데이터 사용량은 평균 70GB에 육박하며, 이는 4G의 4배에 해당합니다. 중국 내 440만 개의 5G 기지국은 이러한 부하를 처리하는 데 필요한 규모를 여실히 보여주고 있으며, 중파 대역 주파수 대역은 여전히 필수적이지만, 현재 중국 이외의 기지국 중 이를 도입한 곳은 4분의 1에 불과합니다. 트래픽이 전환되는 가운데, 통신 사업자들은 추가적인 캐리어 어그리게이션, Massive MIMO 업그레이드 및 동적 주파수 대역 공유를 우선시하고 있습니다. 이러한 투자는 5G 연결 시장의 수익 성장을 뒷받침하는 한편, 네트워크의 에너지 효율을 최적화해야 할 시급성을 높이고 있습니다.
고정 무선 액세스(FWA)가 광대역의 주류 대안으로 부상하고 있습니다.
미국 통신 사업자들은 총 1,150만 회선의 FWA를 제공하고 있으며, 다운로드 속도의 중앙값이 200 Mbps를 초과함에 따라 2028년까지 2,000만 회선에 달할 것으로 예측됩니다. 인도의 통신 사업자들은 제한된 광섬유 구축에 비해 비용 면에서의 우위를 활용하여, 2027년까지 3,000만 명의 FWA 가입자를 확보하는 것을 목표로 하고 있습니다. 버라이즌은 2024년 1분기에 FWA로 4억 5,200만 달러의 매출을 기록하며, 이 방식의 단기적인 수익성을 입증했습니다. mm파(mmWave)의 도입으로 도시 지역의 통신 용량이 증가하고 있으며, 고객 설문조사 결과 44%가 가정용 광대역으로 무선 연결을 선호하는 것으로 나타났습니다. 이러한 동향이 맞물려 사용자 1인당 평균 수익(ARPU)이 향상되고, 5G 연결 시장의 잠재 고객 기반이 확대되고 있습니다.
막대한 설비 투자(CAPEX)와 중파 대역 주파수 비용
2022년부터 2025년까지 전 세계 인프라 투자액은 6,000억 달러를 넘어설 전망이지만, 유럽의 주파수 경매는 과도한 자금 부담을 초래하고 있으며, 그 결과 SA 코어를 채택한 지역 사업자는 2%에 불과한 반면, 중국에서는 80%에 달할 전망입니다. 신흥 시장의 통신 사업자들은 부채 비율 상승을 완화하기 위해 경매를 연기하고 타워 공유를 검토하고 있습니다. 북유럽 국가들의 네트워크 공유는 좋은 사례가 되고 있지만, 자금 면에서의 압박이 여전히 5G 연결 시장으로의 전면적인 진입을 방해하고 있습니다.
부문 분석
2025년에는 스마트폰 보급과 동영상 소비 증가에 힘입어 모바일 브로드밴드가 5G 연결 시장의 61.35%를 차지했습니다. 동시에 스마트 공장, 병원, 물류 허브에서의 사설 5G 네트워크 도입에 힘입어 M2M 및 IoT 연결은 연평균 성장률(CAGR) 27.9%로 확대되고 있습니다. 기업용 시장으로의 전환에 따라 네트워크 슬라이싱 분야의 5G 연결 시장 규모는 현저히 확대되고 있으며, 특히 미션 크리티컬 통신 및 FWA(고정 무선 액세스) 가입자가 트래픽 증가에 기여하고 있습니다. 하드웨어 벤더들은 산업용 센서의 전력 소비를 줄여주는 RedCap 칩셋을 도입하여 M2M 프로젝트의 실현 가능성을 가속화하고 있습니다. 경쟁이 치열한 제조업에서 실시간 분석이 필수 조건이 되는 가운데, 엣지 네이티브 아키텍처는 M2M의 수익화를 더욱 촉진하고 있습니다.
셀룰러 IoT 엔드포인트의 지속적인 보급으로 2028년까지 기기 수가 2배로 증가할 것으로 예상되며, 이에 따라 비용 최적화된 모듈과 간소화된 도입 도구에 대한 끊임없는 수요가 발생하고 있습니다. 미국의 FirstNet 확대에서 한국의 전국적인 공공 안전 네트워크에 이르기까지, 미션 크리티컬 통신의 이용 사례는 서비스 차별화 기회를 넓히고 있습니다. 그 결과로 발생하는 다양성은 소비자 트래픽이 여전히 큰 비중을 차지하는 한편, 미래 5G 연결 시장의 성장에서 기업 트래픽이 과반수 점유율을 차지한다는 새로운 균형을 확립하고 있습니다.
2025년에는 스트리밍과 게임이 모바일 광대역 트래픽을 지탱함에 따라, 5G 연결 시장 규모의 75.32%를 소비자용도가 차지했습니다. 그럼에도 불구하고, 자동차, 의료, 에너지 분야의 디지털 전환 추진에 힘입어 기업용 회선은 2031년까지 연평균 성장률(CAGR) 29.6%를 달성할 것으로 예측됩니다. 특히 제조업에서는 1,000건 이상의 진행 중인 프로젝트에서 프라이빗 5G로 전환한 후 생산 라인의 효율이 15-20% 향상된 것으로 보고되고 있습니다. 싱가포르와 스웨덴의 병원에서는 초저지연 영상 연결이 도입된 결과, 수술 시간 단축과 환자 치료 성과 향상이 확인되었습니다.
스마트 시티 사업에서도 감시 카메라, 커넥티드 가로등, 환경 모니터가 도입되어 각각 기업 가입자 기반의 확대에 기여하고 있습니다. 유틸리티자들은 실시간 전력 계통의 균형 조정을 위해 5G를 채택하고 있으며, 석유 및 가스 사업자들은 자동 점검 드론을 우선적으로 도입하고 있습니다. 이러한 요인들이 복합적으로 작용하여 장기적인 수익의 중심이 기업용으로 이동하고, 연결당 평균 수익이 증가하는 동시에 5G 연결 시장에서 고객의 충성도도 높아지고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 가입자 수의 51.64%를 차지하며, 중국의 440만 개 기지국과 인도에서 스탠드얼론 방식의 급속한 확대에 힘입어 2031년까지 연평균 성장률(CAGR) 29.4%로 성장할 것으로 전망됩니다. 중국의 디지털 경제 기여도는 2030년까지 2조 달러에 달할 전망이며, 이는 제조, 소매, 서비스 산업에서의 5G 플랫폼의 광범위한 도입을 반영한 것입니다. 인도의 Reliance Jio는 100만 곳 이상의 클라우드 네이티브 기지국을 운영하고 있으며, FWA 회선 수는 2027년까지 500만 회선에서 3,000만 회선으로 증가할 것으로 예측됩니다. 일본과 한국의 5G Advanced 조기 상용화는 해당 지역의 혁신 리더십을 유지하고 있으며, 동남아시아에서는 2030년까지 GDP에 1300억 달러 증가 효과를 가져올 것으로 전망됩니다.
북미는 성숙해가고 있지만 여전히 혁신 중심 시장이며, 인구의 98%가 이미 5G 통신 서비스 범위에 포함되어 있습니다. T-Mobile의 전국적인 SA(스탠드얼론) 구축과 643만 회선의 FWA는 소비자 및 기업용 서비스의 다양화를 여실히 보여주고 있습니다. Verizon은 AST SpaceMobile과의 위성 제휴를 통해 농촌 지역에 남아 있는 통신 격차 해소를 목표로 하고 있는 반면, 캐나다 및 멕시코의 통신 사업자들은 RedCap과 같은 5G Advanced 기능을 통합하고 있습니다. 현재는 네트워크 API, 엣지 컴퓨팅, AI를 활용한 서비스 오케스트레이션의 수익 창출로 초점이 이동하고 있으며, 이를 통해 5G 연결 시장 전체에서 사이트당 수익 밀도의 향상이 촉진되고 있습니다.
유럽에서는 진척 상황에 편차가 보입니다. 독일, 덴마크, 핀란드에서는 인구의 95% 이상을 커버하고 있지만, SA 코어에서 운영되는 계약은 고작 2%에 그치고 있습니다. 영국에서는 보다폰과 스리의 합병을 통해 농촌 지역의 통신 격차 해소를 목적으로 한 네트워크 업그레이드에 148억 6,000만 달러가 투입되고 있으며, 북유럽 국가들에서는 주파수 공유 모델을 통해 저비용으로 더 높은 가용성을 실현하고 있습니다. 현재 유럽 대륙의 통신 사업자들은 투자 주기를 유지하기 위해 규제 당국에 경매 효율화와 라이선스료 인하를 강력히 요구하고 있으며, SA 보급 격차를 해소하고 5G 연결 시장에서 더 큰 가치를 창출하는 것을 목표로 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the 5G connections market size was valued at USD 199.49 billion in 2025 and estimated to grow from USD 252.52 billion in 2026 to reach USD 821.95 billion by 2031, at a CAGR of 26.62% during the forecast period (2026-2031).
This report is Segmented by Connection Type (Mobile Broadband, Fixed Wireless Access, and More), End-User (Consumer and Enterprise), Spectrum Band (Sub-1 GHz, 1-6 GHz, and More), Network Architecture (Non-Standalone and Standalone), Device Category (Smartphones and Tablets, FWA CPE, and More), Service Type (Enhanced Mobile Broadband (eMBB), Massive Machine-Type Communications (mMTC), and More), and Geography.
Global 5G Connection Market Trends and Insights
Surge in mobile data traffic requiring higher-capacity networks
Monthly data usage per 5G line averages close to 70 GB-four times the 4G figure-fueled by cloud gaming and extended-reality services. China's 4.4 million 5G base stations illustrate the scale needed to carry this load, and mid-band spectrum remains vital, although only one quarter of non-Chinese sites currently deploy it. As traffic migrates, operators prioritize additional carrier aggregation, Massive MIMO upgrades, and dynamic spectrum sharing. These investments underpin revenue growth in the 5G connections market while raising the urgency to optimize network energy efficiency.
Fixed Wireless Access (FWA) emerging as mainstream broadband alternative
US operators collectively serve 11.5 million FWA lines, with projections of 20 million by 2028 as median download speeds exceed 200 Mbps. Operators in India aim for 30 million FWA subscribers by 2027 by exploiting cost advantages over limited fiber roll-outs. Verizon generated USD 452 million in Q1 2024 FWA revenue, demonstrating the format's near-term profitability. mmWave deployments increase urban capacity, and customer surveys show 44% preference for wireless home broadband. Collectively, these developments boost average revenue per user and broaden the 5G connections market addressable base.
High CAPEX and mid-band spectrum costs
Global infrastructure outlays will exceed USD 600 billion during 2022-2025, and European auctions drive disproportionate financing burdens that leave only 2% of regional operators with SA cores versus 80% in China. Emerging-market carriers postpone auctions and explore tower-sharing to mitigate rising leverage. Network sharing in Nordic economies shows positive examples, but capital pressures still curb full participation in the 5G connections market.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise digitization and IoT accelerating 5G adoption
- Generative-AI-driven uplink surge spurring early 5G-SA roll-outs
- Rural coverage economics remain unattractive
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mobile broadband accounted for 61.35% of the 5G connections market in 2025, underpinned by smartphone adoption and video consumption growth. At the same time, M2M and IoT links are expanding at a 27.9% CAGR, encouraged by private 5G network deployments across smart factories, hospitals, and logistics hubs. The enterprise tilt is materially increasing the 5G connections market size for network slicing, particularly as mission-critical communications and FWA subscriptions contribute incremental traffic. Hardware vendors have introduced RedCap chipsets that lower power draw for industrial sensors, accelerating M2M project viability. Edge-native architectures further catalyze M2M monetization as real-time analytics become table stakes in competitive manufacturing.
Continued proliferation of cellular IoT endpoints is projected to double device counts by 2028, creating relentless demand for cost-optimized modules and simplified onboarding tools. Mission-critical communication use cases, from FirstNet expansion in the US to nationwide public-safety networks in Korea, widen service differentiation opportunities. The resulting diversity cements a new equilibrium in which consumer traffic remains large, yet enterprise traffic captures the outsized share of future 5G connections market growth.
Consumer use retained 75.32% share of the 5G connections market size in 2025 as streaming and gaming sustained mobile broadband traffic. Nonetheless, enterprise lines will deliver a 29.6% CAGR through 2031, powered by digital-transformation mandates in automotive, healthcare, and energy. Manufacturing stands out: more than 1,000 active projects report 15-20% gains in line efficiency after switching to private 5G. Hospitals in Singapore and Sweden show reduced surgery times and enhanced patient outcomes once ultra-low-latency video links are integrated.
Smart-city programs are also deploying surveillance cameras, connected streetlights, and environmental monitors, each adding to the enterprise subscriber base. Utilities turn to 5G for real-time grid balancing, and oil-and-gas operators prioritize automated inspection drones. These converging drivers tilt long-term revenue concentration toward the enterprise, increasing average revenue per connection and deepening stickiness within the 5G connections market.
Complete Report Scope:
- By Connection Type
- Mobile Broadband
- Fixed Wireless Access
- M2M and IoT
- Mission-critical Communications
- Private Networks
- By End-user
- Consumer
- Enterprise
- Manufacturing
- Healthcare
- Automotive and Transportation
- Smart Cities and Public Safety
- Energy and Utilities
- Retail and Logistics
- By Spectrum Band
- Sub-1 GHz (Low-Band)
- 1-6 GHz (Mid-Band)
- above 24 GHz (mmWave / High-Band)
- By Network Architecture
- Non-Standalone (NSA)
- Standalone (SA)
- By Device Category
- Smartphones and Tablets
- FWA CPE
- IoT Modules and Gateways
- Wearables and AR/VR Devices
- Industrial Routers and Rugged Modules
- By Service Type
- Enhanced Mobile Broadband (eMBB)
- Massive Machine-Type Communications (mMTC)
- Ultra-Reliable Low-Latency Communications (URLLC)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific accounted for 51.64% of global subscriptions in 2025 and is forecast to grow at a 29.4% CAGR through 2031, led by China's 4.4 million base stations and India's rapid standalone expansion. China's digital-economy contribution is set to reach USD 2 trillion by 2030, reflecting widespread 5G platform adoption in manufacturing, retail, and services. India's Reliance Jio operates over 1 million cloud-native cell sites, while expected FWA lines could climb from 5 million to 30 million by 2027. Japan's and South Korea's early commercial 5G Advanced launches sustain regional innovation leadership, and Southeast Asia projects USD 130 billion in incremental GDP impact by 2030.
North America is a mature yet innovation-centric arena where 98% of the population already has 5G coverage. T-Mobile's nationwide SA deployment and 6.43 million FWA lines illustrate consumer and enterprise diversification. Verizon's satellite partnership with AST SpaceMobile seeks to close residual rural gaps, while Canadian and Mexican carriers integrate 5G Advanced features such as RedCap. Focus now turns to monetizing network APIs, edge compute, and AI-assisted service orchestration, driving higher revenue density per site across the 5G connections market.
Europe displays mixed progress: Germany, Denmark and Finland exceed 95% population coverage, yet only 2% of subscriptions run on SA cores. The United Kingdom's Vodafone-Three merger injects USD 14.86 billion into network upgrades aimed at rural inclusion, and Nordic spectrum-sharing models yield higher availability at lower cost. Continental operators now press regulators to streamline auctions and lower license fees to sustain investment cycles, seeking to close the SA gap and unlock greater value in the 5G connections market.
- AT&T Inc.
- Verizon Communications Inc.
- Vodafone Group Plc
- China Mobile Ltd.
- China Telecommunications Corp.
- T-Mobile US Inc.
- Telstra Corp. Ltd.
- Telefonica SA
- Deutsche Telekom AG
- Reliance Jio Infocomm Ltd.
- SK Telecom Co. Ltd.
- NTT Docomo Inc.
- KT Corp.
- Orange SA
- KDDI Corp.
- Bharti Airtel Ltd.
- Saudi Telecom Company (stc)
- Rakuten Mobile Inc.
- Etisalat by eand
- MTN Group Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in mobile data traffic requiring higher-capacity networks
- 4.2.2 Fixed Wireless Access (FWA) emerging as mainstream broadband alternative
- 4.2.3 Enterprise digitization and IoT accelerating 5G adoption
- 4.2.4 Generative-AI-driven uplink surge spurring early 5G-SA roll-outs
- 4.2.5 Monetization via Open-API ecosystems
- 4.3 Market Restraints
- 4.3.1 High CAPEX and mid-band spectrum costs
- 4.3.2 Rural coverage economics remain unattractive
- 4.3.3 Fiber price wars dampen urban FWA uptake
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Connection Type
- 5.1.1 Mobile Broadband
- 5.1.2 Fixed Wireless Access
- 5.1.3 M2M and IoT
- 5.1.4 Mission-critical Communications
- 5.1.5 Private Networks
- 5.2 By End-user
- 5.2.1 Consumer
- 5.2.2 Enterprise
- 5.2.2.1 Manufacturing
- 5.2.2.2 Healthcare
- 5.2.2.3 Automotive and Transportation
- 5.2.2.4 Smart Cities and Public Safety
- 5.2.2.5 Energy and Utilities
- 5.2.2.6 Retail and Logistics
- 5.3 By Spectrum Band
- 5.3.1 Sub-1 GHz (Low-Band)
- 5.3.2 1-6 GHz (Mid-Band)
- 5.3.3 above 24 GHz (mmWave / High-Band)
- 5.4 By Network Architecture
- 5.4.1 Non-Standalone (NSA)
- 5.4.2 Standalone (SA)
- 5.5 By Device Category
- 5.5.1 Smartphones and Tablets
- 5.5.2 FWA CPE
- 5.5.3 IoT Modules and Gateways
- 5.5.4 Wearables and AR/VR Devices
- 5.5.5 Industrial Routers and Rugged Modules
- 5.6 By Service Type
- 5.6.1 Enhanced Mobile Broadband (eMBB)
- 5.6.2 Massive Machine-Type Communications (mMTC)
- 5.6.3 Ultra-Reliable Low-Latency Communications (URLLC)
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 France
- 5.7.3.3 United Kingdom
- 5.7.3.4 Rest of Europe
- 5.7.4 Asia Pacific
- 5.7.4.1 China
- 5.7.4.2 India
- 5.7.4.3 Japan
- 5.7.4.4 South Korea
- 5.7.4.5 ASEAN
- 5.7.4.6 Rest of Asia Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 Saudi Arabia
- 5.7.5.1.2 UAE
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AT&T Inc.
- 6.4.2 Verizon Communications Inc.
- 6.4.3 Vodafone Group Plc
- 6.4.4 China Mobile Ltd.
- 6.4.5 China Telecommunications Corp.
- 6.4.6 T-Mobile US Inc.
- 6.4.7 Telstra Corp. Ltd.
- 6.4.8 Telefonica SA
- 6.4.9 Deutsche Telekom AG
- 6.4.10 Reliance Jio Infocomm Ltd.
- 6.4.11 SK Telecom Co. Ltd.
- 6.4.12 NTT Docomo Inc.
- 6.4.13 KT Corp.
- 6.4.14 Orange SA
- 6.4.15 KDDI Corp.
- 6.4.16 Bharti Airtel Ltd.
- 6.4.17 Saudi Telecom Company (stc)
- 6.4.18 Rakuten Mobile Inc.
- 6.4.19 Etisalat by eand
- 6.4.20 MTN Group Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


