|
시장보고서
상품코드
2123336
태국의 접이식 카톤 및 골판지 포장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Thailand Folding Cartons And Corrugated Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
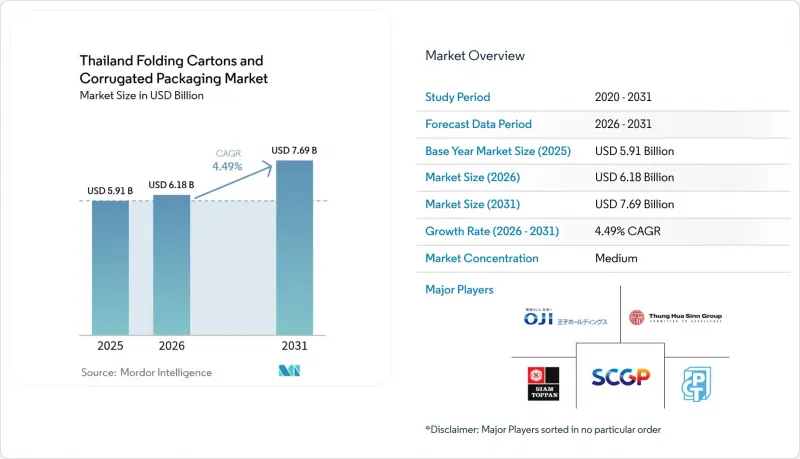
에 의하면, 태국 접이식 카톤 및 골판지 포장 시장 규모는 2025년에 59억 1,000만 달러로 평가되었고 2026년 61억 8,000만 달러에서 2031년까지 76억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.49%를 나타낼 전망입니다.
본 보고서는 소재(버진 섬유, 재생 섬유 등), 포장 유형(접이식 카톤, 골판지 상자), 판지 유형(싱글월 등), 인쇄 기술(오프셋 평판 인쇄, 플렉소 인쇄 등), 최종 사용자 산업(식품 및 음료, 의료 및 제약 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
태국 접이식 카톤 및 골판지 포장 시장 동향과 인사이트
전자상거래 주문 처리 수요의 급증
온라인 소매의 확대로 인해 빈번한 물품 취급을 견딜 수 있는 적절한 크기의 골판지 우편용 상자에 대한 수요가 가속화되고 있으며, 이에 따라 물류 사업자들은 현장에서 치수를 맞춤 설정할 수 있는 자동 골판지 성형 라인에 대한 투자를 진행하고 있습니다. 신선 식품을 위한 콜드체인 소포의 경우, 내습성 층이 요구되므로 폴리 코팅된 라이너나 3중 벽 골판지의 채택이 증가하고 있습니다. 브랜드 소유주들은 가정 쓰레기로 재활용이 가능하다는 점을 이유로 플라스틱보다 종이를 선호하고 있으며, 이에 따라 각 변환 업체들은 산림관리협의회(FSC) 인증 제도에 따른 자재 인증 취득을 서두르고 있습니다. 급속한 도시화로 인해 풀필먼트 센터가 방콕 및 EEC(동부 경제 회랑) 각 주에 집중되고 있어 배송 시간대가 엄격해지는 한편, 적시(JIT) 포장 서비스에 대한 가치 제안이 강화되고 있습니다. 이러한 동향이 판매량 성장을 뒷받침하며, 재활용 가능한 배리어 코팅의 혁신을 촉진하고 있습니다.
태국으로의 OEM 이전
‘차이나 플러스 원(China Plus One)’ 전략을 채택한 전자기기, 자동차, 가전 제조업체들은 라용주나 촌부리주의 산업단지로 생산을 이전하고 있으며, 이에 따라 정전기 방지 골판지 인서트, 재사용 가능한 내부 완충재, 수출용 팔레트에 대한 수요가 증가하고 있습니다. 외국 직접 투자 유입은 현지 가공 업체에 안정적인 수주량을 가져다주는 한편, ISO 9001 및 ISTA 시험과 같은 세계 수준의 품질 관리 시스템 도입을 촉진하고 있습니다. 정부는 EEC 구역 내 통관 절차를 신속화하고 있으며, 이로 인해 리드 타임이 단축됨에 따라 포장 공급업체들은 재고 관리를 ‘저스트-인-시퀀싱(Just-in-Sequence)’ 방식의 조립 공정에 맞추도록 압박받고 있습니다. 많은 OEM 업체들이 여전히 중국에서 크라프트 라이너를 수입하고 있지만, 운임 변동이 심하기 때문에 공급망의 현지화가 진행되고 있으며, 안정적인 국내 회수 네트워크를 갖춘 태국의 수직 통합형 제지 제조업체들이 유리한 입장에 있습니다.
재활용지 공급의 변동성
사용 후 골판지(OCC) 가격은 운송상의 제약과 아시아 내 다른 제지 공장 수요 급증에 따라 변동하며, 현물 구매에 의존하는 독립 가공업체의 이익률을 압박하고 있습니다. 통합형 기업들은 해외 재활용 사업 인수 및 베일의 품질을 확보하는 국내 재구매 프로그램을 통해 위험을 헤지하고 있습니다. 폴리머 기재에 대한 정부의 반덤핑 관세는 기재 전환 비용을 더욱 상승시켜, 가격 변동에도 불구하고 현지산 재생 섬유에 대한 수요를 뒷받침하고 있습니다. 향후 2년 동안 재고 완충 확보와 장기 계약은 위험을 완화하기 위한 필수적인 수단이 될 것입니다.
부문별 분석
2025년, 태국의 접이식 카톤 및 골판지 포장 시장에서 재생 섬유는 47.86%의 점유율을 차지했습니다. 이는 확립된 OCC 회수 네트워크와 비용 경쟁력에 힘입은 결과입니다. 태국 시장의 참여 기업들은 사용 후 제품 회수와 산업 폐기물을 결합한 듀얼 루프 회수 모델을 활용하고 있으며, 이를 통해 베일 수율이 향상되고 매립지의 부담이 경감되고 있습니다. 대나무 및 농업 잔여물의 혼합은 아직 초기 단계이지만, 태국 투자위원회(BOI)의 우대 조치와 ESG 관련 자금 조달을 통해 바이오매스 소화조 및 펄프 생산 라인의 투자 회수 기간이 단축되어 연평균 성장률(CAGR) 6.01%로 확대되고 있습니다.
의약품 첨부 문서나 인스턴트 식품용 트레이 등 품질이 중시되는 용도에서는 여전히 버진 섬유의 사양이 유지되고 있지만, 가공업체들은 비용 절감을 위해 2차 층에 재생 섬유를 대체재로 사용하고 있습니다. 태국의 한 대학은 제지 공장과 제휴하여 재생 섬유의 인장 강도를 높이는 효소 처리를 최적화함으로써 성능 면에서의 격차를 좁히고 있습니다. 브랜드 소유주들이 스코프 3 배출량 목표를 공표하는 가운데, 저탄소 대나무 보드는 전자기기 수출업체로부터 시범적인 주문을 확보하고 있습니다. 태국의 접이식 카톤 및 골판지 포장 시장 규모는 농업 폐기물의 유효 활용으로 인해 판매량이 점차 확대되고 있으며, 이를 통해 농촌 지역의 경제적 연계가 강화되고 원자재 수입 의존도도 완화되고 있습니다.
2025년, 태국의 접이식 카톤 및 골판지 포장 시장 규모 중 54.47%를 골판지 운송 상자가 차지하고 있으며, 이는 견조한 수출 및 전자상거래 흐름을 반영하고 있습니다. 한편, 접이식 카톤은 화장품 및 건강기능식품 업계에서 높이 평가받는 인쇄 재현성, 질감 있는 마감, 그리고 무단 개봉 방지 구조를 제공함으로써 2031년까지 연평균 성장률(CAGR) 5.07%를 나타낼 것으로 전망됩니다. 디지털 스팟 니스 가공 및 메탈릭 호일은 재활용성을 저해하지 않으면서 진열대에서의 가시성을 높여, 명품 브랜드가 한정판 상품을 현지에서 생산할 수 있게 해줍니다.
영양 보충제 및 허브 요법 분야의 브랜드 소유자 통합이 진행됨에 따라, 가공업체와의 공동 개발 계약이 촉진되고, 공급망 수요 예측과 적시(JIT) 배송이 통합되고 있습니다. 산소 차단 기능을 갖춘 내열성 골판지 등급은 상온 보관이 가능한 디저트의 보급을 뒷받침하며, 총 이용 가능 시장을 확대되고 있습니다. 태국의 접이식 카톤 및 골판지 포장 시장은 대량 생산형 범용 골판지와 고수익률 특수 골판지로 양극화가 진행되고 있으며, 다수의 공장 네트워크와 하이브리드 인쇄 워크플로우를 통해 두 분야를 모두 아우를 수 있는 사업자들이 혜택을 보고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the Thailand folding cartons and corrugated packaging market size was valued at USD 5.91 billion in 2025 and estimated to grow from USD 6.18 billion in 2026 to reach USD 7.69 billion by 2031, at a CAGR of 4.49% during the forecast period (2026-2031).
This report is Segmented by Material (Virgin Fiber, Recycled Fiber, and More), Packaging Type (Folding Cartons, Corrugated Boxes), Board Type (Single Wall, and More), Printing Technology (Offset Lithography, Flexography, and More), End-User Industry (Food and Beverage, Healthcare and Pharmaceutical, and More). The Market Forecasts are Provided in Terms of Value (USD).
Thailand Folding Cartons And Corrugated Packaging Market Trends and Insights
E-commerce fulfillment surge
Online retail accelerates demand for right-sized corrugated mailers that withstand high parcel-handling cycles, prompting logistics operators to invest in automated box-forming lines capable of customizing dimensions on the fly. Cold-chain parcels for fresh groceries add a moisture-resistant layer requirement, which lifts uptake of poly-coated liners and triple-wall board. Brand owners favor paper over plastic for its curbside recyclability, pushing converters to certify supplies under Forest Stewardship Council (FSC) schemes. Rapid urbanization concentrates fulfillment centers around Bangkok and EEC provinces, tightening delivery windows and reinforcing value propositions around just-in-time packaging services. These dynamics sustain volume growth and catalyze innovation in recyclable barrier coatings.
OEM relocation to Thailand
Electronics, automotive, and appliance producers adopting "China-plus-one" strategies shift production to Rayong and Chonburi industrial estates, boosting demand for anti-static corrugated inserts, returnable interior cushions, and export-grade pallets. Foreign direct investment flows create captive volumes for local converters while incentivizing world-class quality systems such as ISO 9001 and ISTA testing. Government fast-tracks customs procedures in EEC zones, shortening lead times and compelling packaging suppliers to align inventory management with just-in-sequence assembly. Although many OEMs still import kraft liner from China, volatile freight rates motivate supply-chain localization and favor vertically integrated Thai paper producers with stable domestic collection networks.
Recycled paper supply volatility
Old corrugated containers (OCC) prices fluctuate with shipping constraints and demand spikes from other Asian mills, pressuring margins for independent converters that rely on spot purchases. Integrated players hedge risk through overseas recycling acquisitions and domestic buy-back programs that lock in bale quality. Government anti-dumping duties on polymer substrates further elevate substrate switching costs, sustaining demand for local recycled fiber despite price swings. Inventory buffering and long-term contracts become essential risk-mitigation levers over the next two years.
Other drivers and restraints analyzed in the detailed report include:
- Government incentives for sustainable packaging
- Thai SMEs' shift to short-run digital printing
- Kraft-liner import tariff swings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Recycled fiber held 47.86% of Thailand folding cartons and corrugated packaging market share in 2025, underpinned by well-established OCC collection networks and cost competitiveness. Thailand folding cartons and corrugated packaging market participants leverage dual-loop recovery models that combine post-consumer pick-ups and industrial scrap, boosting bale yields and reducing landfill pressure. Bamboo and agro-residue blends, though nascent, scale at 6.01% CAGR as BOI incentives and ESG-linked financing reduce payback periods for biomass digesters and pulping lines.
Quality-sensitive applications such as pharma inserts and ready-to-eat meal trays retain virgin fiber specifications, but converters substitute recycled furnish in secondary layers to trim costs. Thai universities partner with mills to optimize enzyme treatments that raise recycled fiber tensile strength, narrowing performance gaps. As brand owners publish Scope 3 emissions targets, low-carbon bamboo boards secure pilot orders from electronics exporters. Thailand folding cartons and corrugated packaging market size gains incremental volume from agro-waste valorization, reinforcing rural economic linkages and mitigating raw-material import exposure.
Corrugated shippers constituted 54.47% of Thailand folding cartons and corrugated packaging market size in 2025, reflecting robust export and e-commerce flows. Yet folding cartons register a 5.07% CAGR through 2031 by delivering print fidelity, tactile finishes, and tamper-evident structures valued by cosmetics and nutraceuticals. Digital spot-varnish effects and metallic foils elevate shelf visibility without compromising recyclability, allowing upscale brands to localize limited-edition runs.
Brand-owner consolidation in food supplements and herbal remedies drives joint development agreements with converters, integrating supply-chain forecasting and just-in-time delivery. Temperature-stable cartonboard grades with integrated oxygen barriers support ambient shelf-stable desserts, expanding total available market. Thailand folding cartons and corrugated packaging market continues to bifurcate into high-volume commodity corrugate and high-margin specialty cartons, rewarding players able to straddle both ends through multi-plant networks and hybrid print workflows.
Complete Report Scope:
- By Material
- Virgin Fiber
- Recycled Fiber
- Bamboo and Agro-residue Fiber Blends
- By Packaging Type
- Folding Cartons
- Corrugated Boxes
- By Board Type
- Single Wall
- Double Wall
- Triple Wall
- Folding Boxboard (FBB)
- Other Board Types
- By Printing Technology
- Offset Lithography
- Flexography
- Digital Printing
- Other Printing Technologies
- By End-User Industry
- Food and Beverage
- Healthcare and Pharmaceutical
- Personal Care and Cosmetics
- Electronics and Appliances
- Other End-user Industries
List of Companies Covered in this Report:
- Siam Toppan Packaging Co., Ltd.
- Thai Containers Group Co., Ltd. (SCG Packaging)
- Thung Hua Sinn Group Co., Ltd.
- Continental Packaging (Thailand) Co., Ltd.
- Oji Holdings Corporation
- ASA Group Company Limited
- Sarnti Packaging Co., Ltd.
- Balance Packing Co., Ltd.
- BG Packaging Company Limited
- Tri-Wall Ltd.
- Cand H Paperbox (Thailand) Co., Ltd.
- Hong Thai Packaging Company Limited
- Rengo Co., Ltd.
- Amcor plc
- Print Master Co., Ltd.
- Eastern Printing Public Co., Ltd.
- DS Smith Plc
- SC International Paper and Packaging Co., Ltd.
- Great Oriental Packaging Co., Ltd.
- Visy Industries Holdings Pty. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce fulfilment surge
- 4.2.2 OEM relocation post-US/China trade war
- 4.2.3 Government incentives for sustainable packaging
- 4.2.4 Thai SMEs shift to short-run digital carton printing
- 4.2.5 Growth of refrigerated grocery delivery requiring moisture-resistant corrugate
- 4.2.6 Adoption of bamboo-based fiber to meet ESG lender criteria
- 4.3 Market Restraints
- 4.3.1 Recycled paper supply volatility
- 4.3.2 Fluctuating kraft-liner import tariffs
- 4.3.3 Land-use protests slowing new corrugator installations
- 4.3.4 Rising adoption of reusable plastic crates in produce logistics
- 4.4 Industry Value Chain Analysis
- 4.5 Porters Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Intensity of Competitive Rivalry
- 4.5.5 Threat of Substitutes
- 4.6 The Impact of Macroeconomic Factors on the Market
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Virgin Fiber
- 5.1.2 Recycled Fiber
- 5.1.3 Bamboo and Agro-residue Fiber Blends
- 5.2 By Packaging Type
- 5.2.1 Folding Cartons
- 5.2.2 Corrugated Boxes
- 5.3 By Board Type
- 5.3.1 Single Wall
- 5.3.2 Double Wall
- 5.3.3 Triple Wall
- 5.3.4 Folding Boxboard (FBB)
- 5.3.5 Other Board Types
- 5.4 By Printing Technology
- 5.4.1 Offset Lithography
- 5.4.2 Flexography
- 5.4.3 Digital Printing
- 5.4.4 Other Printing Technologies
- 5.5 By End-User Industry
- 5.5.1 Food and Beverage
- 5.5.2 Healthcare and Pharmaceutical
- 5.5.3 Personal Care and Cosmetics
- 5.5.4 Electronics and Appliances
- 5.5.5 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Siam Toppan Packaging Co., Ltd.
- 6.4.2 Thai Containers Group Co., Ltd. (SCG Packaging)
- 6.4.3 Thung Hua Sinn Group Co., Ltd.
- 6.4.4 Continental Packaging (Thailand) Co., Ltd.
- 6.4.5 Oji Holdings Corporation
- 6.4.6 ASA Group Company Limited
- 6.4.7 Sarnti Packaging Co., Ltd.
- 6.4.8 Balance Packing Co., Ltd.
- 6.4.9 BG Packaging Company Limited
- 6.4.10 Tri-Wall Ltd.
- 6.4.11 Cand H Paperbox (Thailand) Co., Ltd.
- 6.4.12 Hong Thai Packaging Company Limited
- 6.4.13 Rengo Co., Ltd.
- 6.4.14 Amcor plc
- 6.4.15 Print Master Co., Ltd.
- 6.4.16 Eastern Printing Public Co., Ltd.
- 6.4.17 DS Smith Plc
- 6.4.18 SC International Paper and Packaging Co., Ltd.
- 6.4.19 Great Oriental Packaging Co., Ltd.
- 6.4.20 Visy Industries Holdings Pty. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

(주말 및 공휴일 제외)


