

|
시장보고서
상품코드
2123353
폰빌레브란트병 치료 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Von Willebrand Disease Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 폰빌레브란트병 치료 시장 규모는 2025년에 24억 달러로 평가되었고 2026년 25억 5,000만 달러에서 2031년까지 34억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.15%를 나타낼 전망입니다.
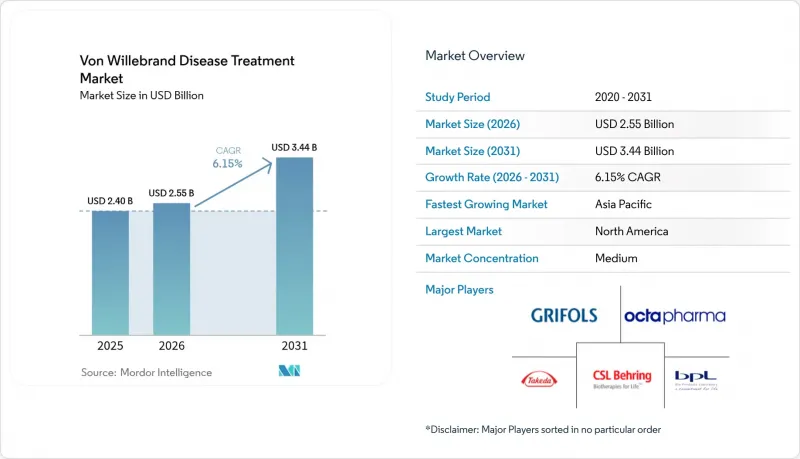
본 보고서는 질환 유형(유형 1, 유형 2, 유형 3 및 후천성 폰빌레브란트병), 치료 유형(데스모프레신, VWF/FVIII 병용 농축 제제, 재조합 VWF 단독 농축 제제 등), 투여 경로(경구, 정맥 내 등), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
전 세계 폰빌레브란트병 치료 시장 동향 및 인사이트
확대되는 환자 지원 및 자선 접근 제도
141곳의 혈우병 치료 센터에 대한 연방 정부의 자금 지원으로, 의료 제공업체는 340B 프로그램에 따라 할인된 가격의 응고 인자 제제를 처방할 수 있게 되어, 환자의 본인 부담금이 경감되고 치료 순응도가 향상되고 있습니다. 캘리포니아주의 ‘All Copays Count’ 법과 같은 주 차원의 노력을 통해 경제적 장벽이 더욱 낮아지고 있는 한편, CMS(미국 의료보험서비스센터)는 응고 인자 공급 수수료를 꾸준히 인상하여 예측 가능한 상환을 보장하고 있습니다. 이러한 조치 덕분에 충분한 의료 서비스를 받지 못하고 있던 환자들도 치료를 받을 수 있게 되어, 폰빌레브란트병 치료 시장 전체 수요가 유지되고 있습니다. 이 다자간 협력 모델이 유럽이나 신흥 경제국에서도 도입된다면, 전 세계적인 보급 범위가 확대될 것으로 예측됩니다. 또한, 자선 재단도 무보험 성인을 대상으로 한 예방 치료에 자금을 지원하고 있어, 치료 건수 증가에 기여하고 있습니다.
예방적 유전자 선별 검사의 확대로 인한 진단 건수 증가
신생아 선별 검사에 건조 혈액 샘플(DBS) 바이오마커 패널을 도입한 국가들에서는 일반 검사에서는 간과되기 쉬운 출혈성 질환에 대해 95%의 검출 정확도를 달성하고 있습니다. 아시아태평양의 보건부는 유사한 프로그램을 확대하고 있으며, 시범 실시 지역에서는 폰빌레브란트병(VWD)의 확진 환자 수가 2배로 증가했습니다. 스웨덴이 NT-proBNP 및 IL-1 RL1 바이오마커를 검사에 포함시킨 것은 조기 발견을 통해 진단 시기가 영아기로 앞당겨지고, 적시의 개입을 촉진하며, 폰빌레브란트병 치료 시장을 확대하고 있음을 보여줍니다. ATHN의 자연 경과 등록부와 더불어, 실제 임상 환경에서의 결과 데이터가 현재 예방적 치료에 대한 보험 적용을 뒷받침하고 있습니다. 진단 건수의 급증으로 인해, 평생 치료나 근치적 치료가 필요한 환자에 대한 안정적인 공급원이 구축되고 있습니다.
저소득 지역에서의 지속적인 진단 부족
많은 개발도상국에서는 예상 사례의 10% 미만이만 확인되고 있어, 치료법에 대한 수요 증가가 억제되고 있습니다. 검사 역량의 한계, 응고 검사 시약의 부족, 그리고 임상의의 인식 부족으로 인해 폰빌레브란트병의 증상은 종종 부인과 질환이나 감염증으로 오인되고 있습니다. 투자 우선순위가 감염성 질환에 치우쳐 있어 전문적인 진단법의 도입이 지연되고 있습니다. 국제 기부자들과의 파트너십은 여전히 소규모에 그치고 있어 의료 서비스 격차가 당장 해소될 전망은 희박하며, 이는 전 세계 폰빌레브란트병 치료 시장에 큰 부담으로 작용하고 있습니다.
부문 분석
2025년에는 제1형 VWD가 전 세계 매출의 71.78%를 차지하며, 같은 해 폰빌레브란트병 치료 시장 규모의 기반을 형성했습니다. 유병률이 높은 경증형의 경우, 가격 부담이 적은 데스모프레신이 사용되고 있어 예측 가능한 판매량을 유지하고 있습니다. 후천성 폰빌레브란트병은 현재 규모는 작지만, 종양내과 전문의와 순환기내과 전문의가 시술 전에 환자를 검사하기 때문에 2031년까지 연평균 성장률(CAGR) 10.78%로 가장 빠른 성장이 예상됩니다. 2형 아형은 농축 제제를 이용한 예방 요법이 필요하기 때문에 임상적 복잡성이 증가하고 있습니다. 특히 2A형 사례에서는 고분자량 멀티머를 회복시키는 재조합 VWF 단독 제제의 혜택을 받고 있어, 연간 출혈률 감소로 이어지고 있습니다.
중증이지만 드문 제3형 환자군은 집중적인 응고 인자 주입이나 정형외과 수술로 인해 불균형적으로 높은 비용이 발생하고 있어, 신흥국에서의 보험 급여 문제가 부각되고 있습니다. 의료기관의 장기적인 경험에 따르면, 모든 유형에서 여전히 진단 미비 현상이 지속되고 있는 것으로 나타나, 등록 시스템 확대와 유전자 검사에 대한 보험사 측의 지원을 요구하는 목소리가 높아지고 있습니다. 고령화 사회에서 약물 유발성 폰빌레브란트병에 대한 인식이 높아짐에 따라, 폰빌레브란트병 치료 시장도 더욱 확대되고 있습니다.
지역별 분석
북미는 2025년 매출의 38.36%를 차지하고 있으며, 그 배경에는 340B 할인 제도와 제품에 대한 접근을 보장하는 종합적인 치료 센터 네트워크가 있습니다. 유전자 치료의 보험 급여 체계는 미국에서 최초로 마련되어 조기 도입을 가능하게 했으며, 높은 가격 책정을 뒷받침하고 있습니다. 캐나다는 주별 처방약 목록 재검토로 인해 다소 뒤처지고 있지만, 혈장 조달의 일원화라는 이점을 누리고 있습니다.
유럽에서는 각국의 보험사가 무바이러스 농축 제제를 요구하고 있어 재조합 제제의 채택률이 높은 반면, 엄격한 의료 기술 평가로 인해 일부 신규 치료법의 도입이 지연되고 있습니다. 서유럽 시장에서는 유전자 치료에 관한 위험 분담 계약이 협상 중이며, 지급이 지속 가능한 요인 자립과 연동되어 있어 이것이 폰빌레브란트병 치료 시장의 구매 동향을 형성하고 있습니다. 동유럽에서는 예산 부족과 진단법 보급 지연에 직면해 있어, 지역 내 양극화된 상황이 발생하고 있습니다.
아시아태평양은 규제 당국이 심사 절차를 합리화하고 각국 정부가 현지 생산에 투자하고 있어, 2031년까지 연평균 성장률(CAGR) 10.12%로 성장을 주도하고 있습니다. 중국, 인도, 한국에서는 신생아 선별 검사의 항목을 확대하고 농축 제제의 수입에 보조금을 지급하고 있어, 이것이 판매량의 두 자릿수 증가를 이끌고 있습니다. 남미, 특히 브라질에서는 경제적 제약이 있음에도 불구하고, 중앙 집중식 조달과 임상 프로토콜의 표준화를 활용하여 접근성 확대를 도모하고 있습니다. 반면, 중동 및 아프리카에서는 진단 기술과 콜드체인의 부족으로 인해 진전이 저해되고 있으나, 재조합 제제의 가격 하락으로 인해 예측 기간 후반에는 잠재적 수요가 유발될 가능성이 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the von willebrand disease treatment market size was valued at USD 2.40 billion in 2025 and estimated to grow from USD 2.55 billion in 2026 to reach USD 3.44 billion by 2031, at a CAGR of 6.15% during the forecast period (2026-2031).
This report is Segmented by Disease Type (Type 1, Type 2, Type 3, and Acquired VWD), Treatment Type (Desmopressin, VWF/FVIII Combination Concentrates, Recombinant VWF-Only Concentrates, and More), Route of Administration (Oral, Intravenous, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Von Willebrand Disease Treatment Market Trends and Insights
Growing Patient-Assistance & Charitable-Access Schemes
Federal funding for 141 Hemophilia Treatment Centers lets providers dispense discounted factor products under the 340B program, reducing out-of-pocket costs and improving adherence. State action, such as California's All Copays Count law, further lowers financial hurdles, while CMS has steadily raised the clotting-factor furnishing fee, ensuring predictable reimbursement. These measures make therapies accessible to underserved patients, sustaining demand across the Von Willebrand disease treatment market. Replication of this multi-stakeholder model in Europe and emerging economies is expected to widen global reach. Charitable foundations also finance prophylaxis for uninsured adults, boosting treatment volume.
Rising Diagnosis From Wider Prophylactic Genetic Screening
Countries adding dried-blood-spot biomarker panels to newborn screening achieve 95% detection accuracy for bleeding disorders that routine tests miss. Asia-Pacific health ministries are scaling similar programs, doubling the recognized VWD population in pilot provinces. Sweden's inclusion of NT-proBNP and IL-1 RL1 biomarkers illustrates how early detection shifts identification to infancy, prompting timely intervention and enlarging the Von Willebrand disease treatment market. Together with ATHN's natural-history registry, real-world outcome data now drives payer coverage for proactive treatments. The diagnostic surge builds a stable pipeline of patients requiring lifelong or curative therapies.
Persistent Under-Diagnosis In Low-Income Geographies
Many developing countries identify fewer than 10% of expected cases, curbing demand growth for therapies. Limited laboratory capacity, scarce coagulation reagents, and low clinician awareness mean VWD symptoms are often misattributed to gynecological or infectious conditions. Investment priorities favor communicable diseases, delaying introduction of specialist diagnostics. International donor partnerships remain small-scale, so coverage gaps are unlikely to close quickly, weighing on the global Von Willebrand disease treatment market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Hospital Adoption Of Recombinant VWF-Only Concentrates
- FDA Fast-Track For Sub-Cutaneous DDAVP Nano-Formulations
- High Lifetime Therapy Cost Despite Biosimilar Entries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Type 1 VWD generated 71.78% of global revenue in 2025, anchoring the Von Willebrand disease treatment market size for that year. Prevalent mild phenotypes rely on affordable desmopressin, sustaining predictable volumes. Acquired VWD, while smaller today, delivers the fastest expansion at 10.78% CAGR through 2031 as oncologists and cardiologists test patients pre-procedure. Type 2 sub-variants together add clinical complexity because they require concentrate prophylaxis; Type 2A cases especially benefit from recombinant VWF-only products that restore high-molecular-weight multimers, reducing annual bleed rate.
The severe but rare Type 3 cohort incurs disproportionate costs due to intensive factor infusions and orthopedic surgeries, highlighting reimbursement challenges in emerging economies. Long-term center experience shows persistent under-diagnosis across all types, prompting calls for registry expansion and payer support for genetic testing. Growing awareness of drug-induced VWD in aging populations further enlarges the Von Willebrand disease treatment market.
Complete Report Scope:
- By Disease Type
- Type 1
- Type 2 (2A, 2B, 2M, 2N)
- Type 3
- Acquired VWD
- By Treatment Type
- Desmopressin (DDAVP)
- VWF/FVIII Combination Concentrates
- Recombinant VWF-only Concentrates
- Antifibrinolytics (e.g., Tranexamic Acid)
- Topical & Adjunctive Agents
- By Route of Administration
- Intravenous
- Intranasal
- Oral
- Sub-cutaneous
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 38.36% of 2025 revenue, underpinned by 340B discounts and comprehensive treatment-center networks that guarantee product access. Gene therapy reimbursement frameworks emerge first in the United States, enabling earlier adoption and supporting premium pricing. Canada trails slightly due to provincial formulary reviews but benefits from centralized plasma procurement.
Europe exhibits high recombinant uptake as national payers demand virus-safe concentrates, yet stringent health-technology assessments delay some novel therapies. Western European markets negotiate risk-sharing deals for gene therapy, tying payment to sustained factor independence, which shapes purchasing dynamics in the Von Willebrand disease treatment market. Eastern Europe faces tighter budgets and slower diagnostic rollout, creating a two-tier landscape within the region.
Asia-Pacific leads growth with a 10.12% CAGR through 2031 because regulators are streamlining review pathways and governments are investing in local manufacturing. China, India, and South-Korea expand newborn-screening panels and subsidize concentrate imports, driving double-digit volume gains. South America, notably Brazil, leverages centralized purchasing and clinical-protocol standardization to broaden access despite economic constraints. In contrast, Middle East and Africa progress is hampered by diagnostic and cold-chain deficits, although recombinant price declines could unlock latent demand later in the forecast.
- CSL Behring
- Takeda (Shire)
- Octapharma
- Grifols
- Sanofi
- Pfizer
- Ferring Pharmaceuticals
- Bio Products Laboratory
- Bayer
- Novo Nordisk
- Kedrion Biopharma
- LFB Group
- ADMA Biologics
- CSL Vifor
- Aptevo Therapeutics
- Kamada Ltd
- Biotest
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Patient Assistance & Charitable?Access Schemes
- 4.2.2 Rising Diagnosis From Wider Prophylactic Genetic Screening
- 4.2.3 Increasing Hospital Adoption Of Recombinant VWF-Only Concentrates
- 4.2.4 FDA Fast-Track For Sub-Cutaneous DDAVP Nano-Formulations
- 4.2.5 Surge In Pay-For-Performance Hemophilia Centers Bundling VWD Care
- 4.2.6 AI-Enabled Bleeding-Risk Decision Engines Integrated In EHRs
- 4.3 Market Restraints
- 4.3.1 Persistent Under-Diagnosis In Low-Income Geographies
- 4.3.2 High Lifetime Therapy Cost Despite Biosimilar Entries
- 4.3.3 Limited Cold-Chain Capacity For Plasma-Derived Products In Africa
- 4.3.4 Regulatory Uncertainty Around Gene-Editing Trials For VWD
- 4.4 Porter's Five Forces
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Disease Type
- 5.1.1 Type 1
- 5.1.2 Type 2 (2A, 2B, 2M, 2N)
- 5.1.3 Type 3
- 5.1.4 Acquired VWD
- 5.2 By Treatment Type
- 5.2.1 Desmopressin (DDAVP)
- 5.2.2 VWF/FVIII Combination Concentrates
- 5.2.3 Recombinant VWF-only Concentrates
- 5.2.4 Antifibrinolytics (e.g., Tranexamic Acid)
- 5.2.5 Topical & Adjunctive Agents
- 5.3 By Route of Administration
- 5.3.1 Intravenous
- 5.3.2 Intranasal
- 5.3.3 Oral
- 5.3.4 Sub-cutaneous
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 CSL Behring
- 6.3.2 Takeda (Shire)
- 6.3.3 Octapharma AG
- 6.3.4 Grifols SA
- 6.3.5 Sanofi SA
- 6.3.6 Pfizer Inc.
- 6.3.7 Ferring Pharmaceuticals
- 6.3.8 Bio Products Laboratory
- 6.3.9 Bayer AG
- 6.3.10 Novo Nordisk A/S
- 6.3.11 Kedrion Biopharma
- 6.3.12 LFB Group
- 6.3.13 ADMA Biologics
- 6.3.14 CSL Vifor
- 6.3.15 Aptevo Therapeutics
- 6.3.16 Kamada Ltd
- 6.3.17 Biotest AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


