

|
시장보고서
상품코드
2123360
웨스턴 블로팅 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Global Western Blotting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 웨스턴 블로팅 시장 규모는 2025년에 16억 9,000만 달러로 평가되었고 2026년 17억 9,000만 달러에서 2031년까지 23억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.92%를 나타낼 전망입니다.
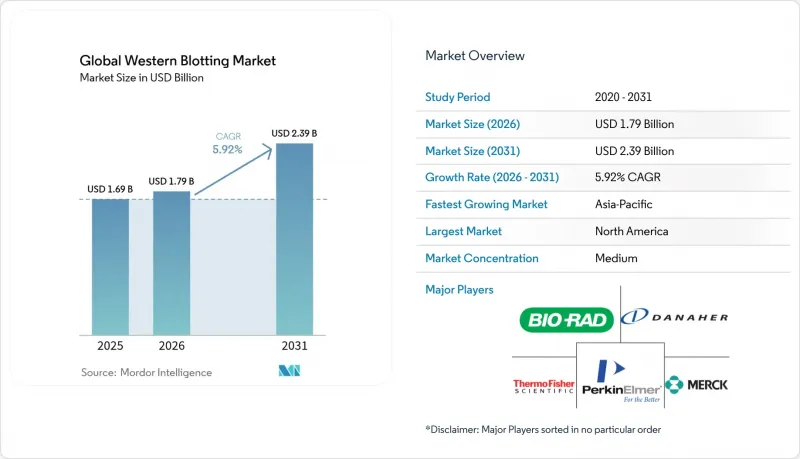
본 보고서는 제품별(장비(젤 및 모세관 전기영동 시스템 등) 및 소모품), 용도별(생의학·생화학 연구, 질병 진단 등), 최종 사용자별(학술 기관·연구 기관, 바이오의약품 기업 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 웨스턴 블로팅 시장 동향 및 인사이트
만성 질환 유병률 증가
1995년부터 2022년까지 유럽의 암 발병률은 58% 상승하여, 종양 생물학 및 대사 장애 연구 분야에서 단백질 바이오마커 확인에 대한 지속적인 수요를 창출하고 있습니다. 현재 종양학 연구에서는 저발현 단백질의 검출과 미세한 번역 후 변형의 검출이 요구되고 있으며, 이는 웨스턴 블로팅이 확실하게 지원하는 기능입니다. 고령 인구 증가로 인해 만성 질환의 사례 수가 더욱 확대되고 있으며, 블로팅용 소모품 및 이미징 시약의 일상적인 사용이 촉진되고 있습니다. 정밀 의학 프로그램이 증가함에 따라, 실험실에서는 수작업으로 인한 오류를 최소화하면서 더 높은 처리 능력을 실현하는 자동 블로팅 플랫폼이 도입되고 있습니다. 이러한 동향들이 맞물리면서 웨스턴 블로팅 시장의 매출 성장 여지가 확대되고 있습니다.
단백질체학 및 바이오마커 발굴 파이프라인의 확대
대규모 단백질체학 이니셔티브가 신약 개발 과정을 재편하고 있습니다. 서모피셔 사이언티픽(Thermo Fisher Scientific)이 올링크(Olink)를 31억 달러에 인수함에 따라, 해당 기업의 포트폴리오에는 5,300개 이상의 검증된 바이오마커 표적이 추가되었습니다. 마이크로플루이딕스 웨스턴 블로팅을 통해 가능해진 단일 세포 단백질 분석은 대량 분석에서는 간과되었던 이질성을 밝혀내고 있습니다. AI를 활용한 항체 스크리닝은 후보 선정 속도를 높이고 검증 시간을 단축하는 동시에 이용 사례를 확대되고 있습니다. 2024년에 18% 증가한 401만 달러에 달할 것으로 예상되는 탠덤 질량 태그 시약의 매출 증가는 보완적인 단백질체학 도구에 대한 활발한 투자를 보여줍니다. 이러한 동향은 웨스턴 블로팅 시장에서 지속적인 플랫폼 업그레이드를 뒷받침하고 있습니다.
대체 면역 분석법 및 알파 기술의 급속한 확산
병렬 반응 모니터링 질량 분석법은 감도를 향상시킨 항체 없는 검출을 가능하게 하여, 기존의 면역블로팅팅과 직접 경쟁하고 있습니다. MSD, Luminex, AlphaLISA와 같은 멀티플렉스 플랫폼을 통해 펨토그램 수준의 검출 정밀도로 사이토카인을 동시에 측정할 수 있게 되었습니다. 이러한 시스템은 분석 시간을 단축하고 작업을 간소화하며, 고처리량 스크리닝 요구를 충족시키고 있습니다. 속도와 멀티플렉싱을 중시하는 연구소에서는 특정 워크플로우를 웨스턴 블로팅에서 전환하고 있으며, 제조업체들은 마이크로플루이딕스 칩 및 통합 이미징 기술을 활용한 혁신을 요구받고 있습니다. 웨스턴 블로팅은 검증 용도로 그 역할을 유지하고 있지만, 이러한 대체 기술의 부상으로 인해 웨스턴 블로팅 시장의 일상적인 정량 분야에서의 성장은 제한되고 있습니다.
부문 분석
2025년에는 소모품이 매출의 64.78%를 차지하며, 이는 막, 항체, 완충액 및 화학 발광 기질의 지속적인 판매를 반영합니다. 이러한 광범위한 도입 기반 덕분에 웨스턴 블로팅 시장공급업체들은 안정적인 현금 흐름을 확보하고 있습니다. 자동화 및 마이크로플루이딕스 장비는 절대 매출 비중은 작지만, 사용자가 처리 속도와 시약 사용량 감소를 중시함에 따라 2031년까지 연평균 성장률(CAGR) 7.68%로 확대되고 있습니다. 키트 기반 솔루션은 워크플로우를 더욱 효율화하고, 사용자 간 편차를 줄이는 동시에 규제 관련 문서 작성을 용이하게 합니다. 이 부문의 탄력성은 플랫폼이 아무리 발전하더라도 소모품 교체 주기가 불가피하다는 점에 있습니다.
마이크로플루이딕스 장치는 항체 사용량을 기존 대비 1% 수준으로 줄여 어세이당 비용을 절감하는 동시에 공급 제약을 완화합니다. 이미징 시스템에는 현재 밴드 강도를 평가하는 AI 알고리즘이 내장되어 있어 판정 시 주관성을 낮추고 있습니다. 기존의 습식 전사 장치는 자본 예산 제약으로 인해 고성능 자동화 시스템 도입이 어려운 학술 연구소에서 여전히 활용되고 있습니다. 젤 및 모세관 전기영동 모듈은 시료 전처리와 후속 블로팅을 연결하는 역할을 계속 수행하며, 웨스턴 블로팅 시장 전체의 지속성을 뒷받침하고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 41.62%를 차지하며, 그 배경에는 성숙한 연구 인프라, 막대한 바이오의약품 연구개발비, 그리고 검증된 단백질 분석법을 중시하는 엄격한 규제 감독 체제가 있습니다. 매출의 대부분은 미국이 차지하고 있지만, 캐나다와 멕시코도 확대되는 생명공학 클러스터 및 임상시험 활동을 통해 매출 증가에 기여하고 있습니다. 정부 보조금, 벤처 캐피털 유입, 그리고 선진적인 공급업체 생태계가 자동화 블로팅 플랫폼의 조기 도입을 촉진하여 이 지역의 리더십을 유지하고 있습니다.
이어 유럽에서는 독일, 영국, 프랑스, 스위스에 확고한 생명공학 거점이 자리 잡고 있습니다. 유럽 규제 당국은 현재 재현 가능한 분석 결과를 요구하고 있으며, 이로 인해 검증된 항체 공급원 및 표준 운영 절차(SOP)가 더욱 중요시되고 있습니다. 1,500개 이상의 기업과 6만 명의 고용을 보유한 스위스의 생명공학 네트워크는 혁신의 집중이 장비 수요를 어떻게 촉진하고 있는지를 보여줍니다. 이탈리아나 스페인 등 시장에서는 제약 제조 및 대학 연구를 통해 수요가 확대되고 있지만, 예산 제약이 장비 보급률에 영향을 미치고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2031년까지 연평균 성장률(CAGR)이 8.28%를 나타낼 것으로 예측됩니다. 중국의 대규모 벤처 투자와 국가 지원 생명과학 단지가 블로팅용 소모품 및 자동 영상 분석 시스템의 대규모 조달을 주도하고 있습니다. 인도에서는 중개 연구 및 국내 바이오의약품 생산을 지원하는 정부의 이니셔티브으로 도입이 가속화되고 있습니다. 일본과 한국은 견고한 제약 기반과 국제 기준에 부합하는 규제 체계를 활용하여 장비 교체 주기를 유지하고 있습니다. 호주와 동남아시아 국가들은 규모는 작지만 단백질체학 시설에 대한 보조금을 투입하고 있어, 웨스턴 블로팅 시장에서 해당 지역의 입지를 강화하고 있습니다. 학계, 정부, 산업계를 연결하는 협업 모델이 인프라를 강화하여 장기적인 성장 모멘텀을 확보하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the western blot market size was valued at USD 1.69 billion in 2025 and estimated to grow from USD 1.79 billion in 2026 to reach USD 2.39 billion by 2031, at a CAGR of 5.92% during the forecast period (2026-2031).
This report is Segmented by Product (Instruments {Gel & Capillary Electrophoresis Systems and More} and Consumables), Application (Biomedical & Biochemical Research, Disease Diagnostics, and More), by End-User (Academia and Research Institutes, Biopharma Companies, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Western Blotting Market Trends and Insights
Rising Prevalence of Chronic Diseases
Cancer incidence climbed 58% in Europe between 1995 and 2022, creating sustained demand for protein biomarker confirmation in tumor biology and metabolic-disorder studies.Oncology research now requires the detection of low-abundance proteins and subtle post-translational changes, functions that western blotting supports reliably. The growing elderly population further enlarges case volumes for chronic conditions, reinforcing routine use of blot consumables and imaging reagents. As precision-medicine programs multiply, laboratories integrate automated blot platforms that handle higher throughput with minimal manual error. These patterns together lengthen the revenue runway for the Western blot market.
Expansion of Proteomics & Biomarker Discovery Pipelines
Large-scale proteomics initiatives are reshaping pharmaceutical discovery. Thermo Fisher Scientific's USD 3.1 billion purchase of Olink added more than 5,300 validated biomarker targets to its portfolio. Single-cell protein assays enabled by microfluidic western blotting now reveal heterogeneity that bulk analyses miss. AI-driven antibody screening accelerates candidate selection, cutting validation time and widening use cases. Rising sales of tandem-mass-tag reagents, up 18% to USD 4.01 million in 2024, indicate vigorous spending on complementary proteomics tools. These trends underpin continuous platform upgrades within the Western blot market.
Rapid Uptake of Alternative Immunoassay & Alpha Technologies
Parallel-reaction-monitoring mass spectrometry now offers antibody-free detection with enhanced sensitivity, directly challenging conventional immunoblotting. Multiplex platforms such as MSD, Luminex, and AlphaLISA permit simultaneous cytokine measurements with femtogram-level detection. These systems shorten assay time, simplify quantity, and align with high-throughput screening needs. Laboratories focused on speed and multiplexing migrate certain workflows away from western blotting, pressuring manufacturers to innovate with microfluidic chips and integrated imaging. While western blotting retains validation roles, the alternative technologies limit expansion in routine quantitation segments of the western blot market.
Other drivers and restraints analyzed in the detailed report include:
- Escalating Pharma / Biotech R&D Budgets
- Adoption of Automated & Microfluidic WB Platforms
- High Capital & Operating Cost of Western Blot Instruments & Antibodies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables generated 64.78% of revenue in 2025, reflecting recurring sales of membranes, antibodies, buffers, and chemiluminescent substrates. This broad installed base secures stable cash flow for suppliers in the Western blot market. Automated and microfluidic instruments, while representing a smaller absolute revenue pool, are expanding at 7.68% CAGR to 2031 as users prioritize speed and low reagent footprints. Kit-based solutions further streamline workflows, lowering user variability and facilitating regulatory documentation. The segment's resilience resides in unavoidable consumable replacement cycles, regardless of platform sophistication.
Microfluidic devices reduce antibody usage to 1% of conventional volumes, trimming per-assay costs and easing supply constraints. Imaging systems now include embedded AI algorithms that assess band intensity, reducing interpretation subjectivity. Traditional wet-transfer equipment still serves academic labs where capital budgets limit the adoption of high-end automation. Gel and capillary electrophoresis modules continue to bridge sample preparation with downstream blotting, supporting overall western blot market continuity.
Complete Report Scope:
- By Product
- Instruments
- Gel & Capillary Electrophoresis Systems
- Traditional Wet / Semi-dry / Dry Blotting Systems
- Automated & Microfluidic Platforms
- Imagers
- Consumables
- Reagent and Buffers
- Kits
- Instruments
- By Application
- Biomedical & Biochemical Research
- Disease Diagnostics
- Agricultural & Food Safety Testing
- By End-User
- Academic & Research Institutes
- Biopharma & Biotechnology Companies
- Hospitals & Diagnostic Laboratories
- CROs & Contract Testing Labs
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 41.62% of worldwide revenue in 2025, underpinned by mature research infrastructure, substantial biopharmaceutical R&D outlays, and rigorous regulatory oversight that values validated protein methods. The United States accounts for most sales, while Canada and Mexico contribute incremental gains through growing biotech clusters and clinical-trial activity. Government grants, venture capital flow, and an advanced supplier ecosystem foster early adoption of automated blot platforms, sustaining regional leadership.
Europe follows with well-established biotechnology hubs in Germany, the United Kingdom, France, and Switzerland. European regulators now demand reproducible analytics, reinforcing preferences for validated antibody sources and standard operating procedures. Switzerland's biotech network of more than 1,500 companies and 60,000 jobs illustrates how concentrated innovation feeds equipment demand. Markets such as Italy and Spain add volume via pharmaceutical manufacturing and university research, though budget constraints influence instrument penetration rates.
Asia Pacific is the fastest-growing territory, projected at an 8.28% CAGR through 2031. China's significant venture investments and state-sponsored life-sciences parks drive substantial procurement of blotting consumables and automated imaging systems. India accelerates adoption through government initiatives supporting translational research and domestic biologics production. Japan and South Korea leverage strong pharmaceutical bases and regulatory alignment with global standards to sustain replacement cycles. Australia and Southeast Asian countries, while smaller, are channeling grant funding toward proteomics facilities, strengthening regional participation in the western blot market. Collaborative models linking academia, government, and industry bolster infrastructure, ensuring long-term growth momentum.
List of Companies Covered in this Report:
- Thermo Fisher Scientific
- Bio-Rad Laboratories
- Danaher (Cytiva & ProteinSimple)
- Merck
- PerkinElmer
- LI-COR Biosciences
- Bio-Techne
- GE Healthcare
- Abcam
- Agilent Technologies
- Roche
- Azure Biosystems
- Rockland Immunochemicals
- Advansta Inc.
- GenScript Biotech
- RayBiotech Life
- ProteinSimple (Sartorius)
- Biovision
- Promega
- SignalChem Biotech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Chronic Diseases
- 4.2.2 Expansion of Proteomics & Biomarker Discovery Pipelines
- 4.2.3 Escalating Pharma / Biotech R&D Budgets
- 4.2.4 Adoption of Automated & Microfluidic Wb Platforms
- 4.2.5 Ai-Driven Antibody Validation Workflows Boosting Western Blot Demand
- 4.2.6 Regulatory Focus on Reproducible Protein Data
- 4.3 Market Restraints
- 4.3.1 Rapid Uptake of Alternative Immunoassay & Alpha Technologies
- 4.3.2 High Capital & Operating Cost of Western Blot Instruments & Antibodies
- 4.3.3 Antibody Batch-To-Batch Variability Undermining Reproducibility
- 4.3.4 Laboratory Decarbonization Targets Favoring Low-Reagent Assays
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product
- 5.1.1 Instruments
- 5.1.1.1 Gel & Capillary Electrophoresis Systems
- 5.1.1.2 Traditional Wet / Semi-dry / Dry Blotting Systems
- 5.1.1.3 Automated & Microfluidic Platforms
- 5.1.1.4 Imagers
- 5.1.2 Consumables
- 5.1.2.1 Reagent and Buffers
- 5.1.2.2 Kits
- 5.1.1 Instruments
- 5.2 By Application
- 5.2.1 Biomedical & Biochemical Research
- 5.2.2 Disease Diagnostics
- 5.2.3 Agricultural & Food Safety Testing
- 5.3 By End-User
- 5.3.1 Academic & Research Institutes
- 5.3.2 Biopharma & Biotechnology Companies
- 5.3.3 Hospitals & Diagnostic Laboratories
- 5.3.4 CROs & Contract Testing Labs
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Thermo Fisher Scientific
- 6.3.2 Bio-Rad Laboratories
- 6.3.3 Danaher (Cytiva & ProteinSimple)
- 6.3.4 Merck KGaA (Millipore Sigma)
- 6.3.5 PerkinElmer
- 6.3.6 LI-COR Biosciences
- 6.3.7 Bio-Techne Corporation
- 6.3.8 GE Healthcare
- 6.3.9 Abcam plc
- 6.3.10 Agilent Technologies
- 6.3.11 Roche Diagnostics
- 6.3.12 Azure Biosystems
- 6.3.13 Rockland Immunochemicals
- 6.3.14 Advansta Inc.
- 6.3.15 GenScript Biotech
- 6.3.16 RayBiotech Life
- 6.3.17 ProteinSimple (Sartorius)
- 6.3.18 BioVision Inc.
- 6.3.19 Promega Corporation
- 6.3.20 SignalChem Biotech
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


