

|
시장보고서
상품코드
2123363
산업용 디스플레이 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Industrial Display - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
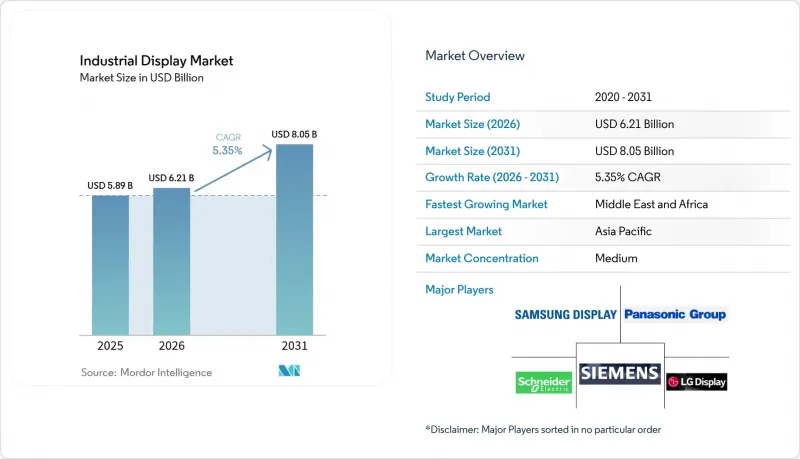
에 의하면, 2026년 산업용 디스플레이 시장 규모는 62억 1,000만 달러로 추정되고 있어 2025년 58억 9,000만 달러에서 확대될 전망입니다. 또한 2031년 시장 규모는 80억 5,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 5.35%로 성장할 전망입니다.
본 보고서는 유형별(내환경형 디스플레이, 오픈 프레임 모니터 등), 용도별(휴먼-머신 인터페이스, 원격 자산 및 파이프라인 모니터링 등), 기술별(LCD, LED 백라이트 장착 LCD 등),패널 크기(14인치 이하, 14인치-21인치 등), 최종 이용 산업(제조, 에너지 및 전력 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 산업용 디스플레이 시장 동향 및 인사이트
디스크리트 제조 및 공정 플랜트에서의 산업용 IoT 도입 확대
엣지 지원 HMI는 이더넷 기반 네트워크를 통해 밀리초 단위의 지연 데이터 처리가 가능해져, 예기치 않은 정지를 최소화하는 예측 유지보수 대시보드를 구현하고 있습니다. 록웰 오토메이션은 컨트롤러와 시각화 엔드포인트 간의 연동이 더욱 긴밀해지고 있음을 언급하며, IIoT 아키텍처를 2025년을 향한 주요 디지털화 로드맵으로 자리매김하고 있습니다. HMS 네트웍스는 이러한 추세를 뒷받침하듯, 2024년 신규 노드 설치의 71%를 산업용 이더넷이 차지하며, PROFINET, EtherNet/IP, EtherCAT 스택을 지원하는 디스플레이에 대한 수요를 촉진하고 있다고 지적합니다.
유해 화학물질 취급 시설에서의 다기능 HMI 수요 급증
기술 보고서 ‘ISA-TR101.02-2019’는 현재 모든 조달 요건서에 영향을 미치고 있는 사용 편의성 및 성능 벤치마크를 규정하고 있습니다. VarTech Systems와 같은 공급업체는 멀티 터치, 음성 제어, 1,000 nit를 초과하는 휘도를 갖춘 C1D1 및 C1D2 인증 패널을 제공하여 안전성과 기능성을 모두 충족시키고 있습니다. 이러한 사양은 운영자의 개입 시 마이크로초 단위의 대응이 요구되는 화학·제약 분야에서 배치 간 일관성을 확보하는 데 도움이 됩니다.
도입 및 유지 관리 비용 증가
방폭 인클로저, 컨포멀 코팅 및 전용 장착 키트로 인해 시스템의 초기 투자 비용이 높아집니다. Comark Corporation의 추산에 따르면, IECEx 준수로 인해 해양 플랫폼용 설비 예산이 2배로 늘어나고 설계 일정이 몇 분기 정도 연장될 가능성이 있습니다.
부문 분석
IP65-67 규격을 준수하는 견고한 인클로저는 2025년에 산업용 디스플레이 시장의 31.12% 점유율을 차지했습니다. 이는 시추, 광업, 군사 플랫폼의 가혹한 사용 조건에 대한 요구 사항을 반영한 것입니다. 비디오월은 석유화학 단지 전체의 중앙 제어실 투자에 힘입어 연평균 5.66%의 복합 성장률로 확대될 것으로 예측됩니다. 고휘도 오픈 프레임 모듈은 키오스크 케이스에 통합되어 있지만, 패널 마운트형 유닛은 기계 수준의 HMI에서 여전히 주력 제품으로 자리 잡고 있습니다. 산업용 디스플레이 시장에서는 내충격성과 모듈형 I/O를 겸비하여 신속한 교체와 가동 중단 시간 최소화를 보장하는 공급업체가 지속적으로 선호되고 있습니다. 선박용 등급 제품은 MIL-STD-167의 진동 내성 기준 및 염수 분무 시험 규격을 충족하여, 산업용 디스플레이 시장의 적용 범위를 해군 함정 및 해양 시추 시설까지 확대되고 있습니다. 바형 및 스트레치 스크린은 발전소의 다중 매개변수 대시보드를 지원하며, 판매량은 적지만 이 틈새 시장은 높은 평균 판매 가격(ASP)으로 이어지고 있습니다.
2차 공급업체들은 견고성과 좁은 베젤 아키텍처를 융합하여 현장 패널과 지휘 센터 모두에 적합한 크로스오버 제품을 생산하고 있습니다. Barco가 체결한 4,000대의 레이저 스크린을 대상으로 한 엔터프라이즈 시네마 계약은 제조의 확장성을 입증하고 있으며, 이는 이후 산업용 비디오월로 확대되었습니다. 하이브리드 섀시에는 현재 이중화된 전원 공급 장치와 엣지 게이트웨이가 내장되어 있어, IEC 60079-2025 안전 조항을 준수하면서 서비스가 가능한 산업용 디스플레이 시장을 확대되고 있습니다.
HMI 스테이션은 2025년 매출의 46.05%를 차지했지만, 파이프라인 및 웰패드의 원격 측정 데이터가 중앙 집중식 NOC로 전환됨에 따라 원격 자산 가시화 부문은 연평균 성장률(CAGR) 6.12%로 이를 상회하는 성장이 예상됩니다. 사막이나 연안 지역에서 위성 및 LPWAN 연결이 보급됨에 따라, 원격 모니터링용 산업용 디스플레이 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 린 생산 방식을 채택한 공장의 안돈 보드나 유지보수 인력을 위한 인터랙티브 키오스크는 인간 중심의 시각적 워크플로우를 강화하고, 고장 발생부터 수리까지의 주기를 단축합니다. 제어실의 비디오월은 프리미엄급으로 분류되며, 베젤리스 LCD와 신기술인 마이크로 LED 어레이가 몰입감 있는 상황 인식 환경을 구축하고 있습니다. AI 기반 분석 플랫폼과의 통합을 통해 운영자는 화면에 직접 표시되는 처방적 지침에 따라 행동할 수 있게 되어, 운영자의 피로와 실수 발생률을 줄이고 있습니다.
OnePetro사의 현장 시험을 통해 검증된 분산형 태양광 발전 스크린은 전력망에 접근할 수 없는 지역에서도 실용성이 입증되어, 외딴 채굴 지역의 산업용 디스플레이 시장 도입 기반을 확대되고 있습니다. 사이버 보안의 중요성이 높아짐에 따라, 디스플레이에는 화면상의 데이터 흐름을 보호하기 위해 하드웨어 루트 오브 트러스트 모듈이 내장되는 사례가 증가하고 있으며, 이러한 요구 사항은 국경을 넘는 파이프라인 운영에서 특히 중요하게 여겨지고 있습니다.
지역별 분석
아시아태평양은 2025년에 매출의 36.55%를 차지하며, 중국의 공장 자동화 추진과 정밀 부품 분야에서의 일본의 리더십이 이를 뒷받침하고 있습니다. 삼성디스플레이와 LG디스플레이는 전 세계적인 규모의 OLED 제조 공장을 운영하고 있어, 산업용 디스플레이 시장 전체에서 해당 지역공급 우위를 공고히 하고 있습니다. 각국 정부는 패널 공장 확장을 가속화하는 설비 투자 세액 공제를 지원하여, 반도체 부족 상황에서도 안정적인 패널 공급을 확보하고 있습니다.
중동 및 아프리카은 2031년까지 연평균 성장률(CAGR) 6.05%라는 가장 높은 성장세가 예상됩니다. 걸프 지역 전역에서 진행되고 있는 수십억 달러 규모의 탄화수소 프로젝트에서는 IEC 60079-2025 규격에 따라 인증된 본질 안전형 스크린이 필수적이며, 이로 인해 방폭형 하드웨어용 산업용 디스플레이 시장 규모가 확대되고 있습니다. 국영 석유 회사(NOC)는 중앙 관리 거점과 지역의 마이크로 제어실을 연계하고 있으며, 사막의 기온에서도 고휘도를 유지할 수 있는 동기화된 비디오월을 요구하고 있습니다.
북미에서는 에너지 효율 향상과 사이버 보안 강화를 목표로, 지은 지 50년 이상 된 공장의 개보수 열풍이 일고 있습니다. CRT 및 저항막 방식 터치 패널을 IP 기반 유리 표면으로 선구적으로 교체하는 움직임에 따라, 공장이 디지털 퍼포먼스 보드를 도입함에 따라 산업용 디스플레이 시장이 확대되고 있습니다. 유럽에서는 EN ISO 9241-210 사용성 지침을 준수하는 인체공학 기반의 HMI 레이아웃에 중점을 두고, 인더스트리 4.0 청사진을 추진함으로써 운영자의 웰빙을 증진하고 있습니다. 남미의 광업 및 수력 발전 부문에서는 고지대나 고습도 환경에 대응할 수 있는 내구성이 뛰어난 패널이 수입되면서, 지역별 수익원이 더욱 다각화되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, industrial display market size in 2026 is estimated at USD 6.21 billion, growing from 2025 value of USD 5.89 billion with 2031 projections showing USD 8.05 billion, growing at 5.35% CAGR over 2026-2031.
This report is Segmented by Type (Rugged Displays, Open Frame Monitors, and More), Application (Human-Machine Interface, Remote Asset and Pipeline Monitoring, and More), Technology (LCD, LED Backlit LCD, and More), Panel Size (Up To 14 Inch, 14 Inch - 21 Inch, and More), End-Use Industry (Manufacturing, Energy and Power, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Display Market Trends and Insights
Increasing Adoption of Industrial IoT in Discrete and Process Plants
Edge-ready HMIs now process millisecond latency data from Ethernet-based networks, enabling predictive maintenance dashboards that minimize unplanned shutdowns. Rockwell Automation identifies IIoT architecture as the principal digitization pathway for 2025, citing tighter coupling between controllers and visualization endpoints. HMS Networks confirms momentum, noting that Industrial Ethernet supplied 71% of new node installations in 2024, catalyzing demand for displays that support PROFINET, EtherNet/IP and EtherCAT stacks.
Demand Surge for Multi-featured HMI in Hazardous Chemical Facilities
The ISA-TR101.02-2019 technical report codifies usability and performance benchmarks that now influence every procurement brief. Suppliers such as VarTech Systems deliver C1D1 and C1D2 certified panels offering multi-touch, voice control and >1,000 nit brightness, aligning safety with functionality. These specifications support batch-to-batch integrity in chemicals and pharmaceuticals where micro-seconds matter for operator intervention.
High Cost of Implementation and Maintenance
Explosion-proof enclosures, conformal coatings, and specialized mounting kits elevate upfront system outlays. Comark Corporation projects that IECEx compliance can double equipment budgets for offshore platforms while extending engineering schedules by several quarters.
Other drivers and restraints analyzed in the detailed report include:
- Lean-Manufacturing Digital Signage (Andon) Roll-outs Across Automotive Lines
- Retrofit Wave of Aging North-American Factories for Electrification and Automation
- Prolonged LCD Controller Lead-Times Amid Chip Shortage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rugged housings rated to IP65-67 secured a 31.12% slice of the industrial display market in 2025, reflecting critical-duty requirements in drilling, mining and military platforms. Video walls are projected to compound at 5.66% annually, fueled by centralized control-room investment across petrochemical complexes. High-brightness open-frame modules integrate into kiosk enclosures, while panel-mount units remain the workhorse for machine-level HMIs. The industrial display market repeatedly favors vendors that combine shock resistance with modular I/O, ensuring rapid swap-out and minimal downtime. Marine-grade variants meet MIL-STD-167 vibration thresholds and salt-spray protocols, extending the industrial display market footprint to naval vessels and offshore rigs. Bar-type and stretch screens address multi-parameter dashboards in power plants, a niche translating to higher ASPs despite lower volumes.
Second-tier suppliers are blending ruggedization with narrow-bezel architectures, creating cross-over products that serve both field panels and command centers. Barco's enterprise cinema contract for 4,000 laser screens underscores manufacturing scalability that later translates into industrial video walls. Hybrid enclosures now embed redundant power supplies and edge gateways, aligning with IEC 60079-2025 safety clauses while enlarging the serviceable industrial display market.
HMI stations delivered 46.05% of 2025 revenue, but remote asset visualization will outpace at a 6.12% CAGR as pipeline and well-pad telemetry shifts to centralized NOCs. The industrial display market size for remote monitoring is forecast to expand steadily as satellite and LPWAN connectivity proliferate in deserts and offshore locations. Andon boards in lean plants and interactive kiosks for maintenance crews reinforce human-centric visual workflows that shorten fault-to-fix cycles. Control-room video walls constitute the premium class where bezel-less LCD or emerging Micro-LED arrays craft immersive situational awareness environments. Integration with AI-driven analytics platforms means operators now act on prescriptive prompts rendered directly on the screen, reducing operator fatigue and error incidence.
Distributed solar-powered screens demonstrated by OnePetro field trials prove viability in regions lacking grid access, widening the install base of the industrial display market in remote extraction zones. As cybersecurity rises in priority, displays are increasingly paired with hardware-root-of-trust modules to secure on-screen data flows, a requirement accentuated in cross-border pipeline operations.
Complete Report Scope:
- By Type
- Rugged Displays
- Open Frame Monitors
- Panel-Mount Monitors
- Marine and Naval-Grade Displays
- Industrial Video Walls
- Bar-Type/Stretch Displays
- By Application
- Human-Machine Interface (HMI)
- Remote Asset and Pipeline Monitoring
- Interactive Kiosks and Operator Terminals
- In-plant Digital Signage and Andon Boards
- Control-Room Video Walls
- By Technology
- LCD
- LED Backlit LCD
- OLED/AMOLED
- E-Paper and Reflective Displays
- Micro-LED
- By Panel Size
- Up to 14 inch
- 14 inch - 21 inch
- 21 inch - 40 inch
- 40 inch and Above
- By End-Use Industry
- Manufacturing
- Energy and Power
- Oil and Gas
- Mining and Metals
- Chemical and Pharmaceutical
- Transportation and Logistics
- Others (Water and Wastewater, Defense)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific commanded 36.55% revenue in 2025, underpinned by China's factory automation drive and Japan's leadership in precision components. Samsung Display and LG Display operate global-scale OLED fabs, cementing the region's supply advantage across the industrial display market. Component governments back capex tax credits that accelerate panel plant expansions, ensuring steady panel availability even during semiconductor shortages.
The Middle East and Africa is poised for the fastest 6.05% CAGR to 2031. Multi-billion-dollar hydrocarbon projects across the Gulf rely on intrinsically safe screens certified under IEC 60079-2025, enlarging the industrial display market size for explosion-proof hardware. National oil companies pair centralized NOCs with regional micro-control rooms, demanding synchronized video walls that sustain high brightness amid desert temperatures.
North America witnesses a retrofit wave across mid-century factories seeking energy efficiencies and cybersecurity hardening. Proactive replacement of CRTs and resistive-touch panels with IP-based glass surfaces boosts the industrial display market as factories embrace digital performance boards. Europe advances Industry 4.0 blueprints with a focus on ergonomic HMI layouts compliant with EN ISO 9241-210 usability guidance, promoting operator well-being. South America's mining and hydroelectric sectors import hardy panels rated for high altitude and humidity, further diversifying geographic revenue.
- Samsung Display Co., Ltd.
- LG Display Co., Ltd.
- Panasonic Holdings Corp.
- Sharp Corp.
- Emerson Electric Co.
- Schneider Electric SE
- Siemens AG
- Rockwell Automation Inc.
- NEC Display Solutions, Ltd.
- Advantech Co., Ltd.
- Barco NV
- WinMate Inc.
- Planar Systems, Inc.
- AU Optronics Corp.
- Bosch Rexroth AG
- Mitsubishi Electric Corp.
- Honeywell International Inc.
- Kontron AG
- iBASE Technology Inc.
- Beijer Electronics Group AB
- Delta Electronics, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Adoption of Industrial IoT in Discrete and Process Plants
- 4.2.2 Demand Surge for Multi-featured HMI in Hazardous Chemical Facilities
- 4.2.3 Lean-Manufacturing Digital Signage (Andon) Roll-outs Across Automotive Lines
- 4.2.4 Retrofit Wave of Aging North-American Factories for Electrification and Automation
- 4.2.5 Outdoor-Grade Sunlight-Readable Micro-OLED/Micro-LED Panels for Oilfield Operations
- 4.2.6 IECEx-2022 Mandate for Intrinsically Safe Offshore Display Hardware
- 4.3 Market Restraints
- 4.3.1 High Cost of Implementation and Maintenance
- 4.3.2 Prolonged LCD Controller Lead-Times Amid 2023-24 Chip Shortage
- 4.3.3 Legacy PLC Interface Fragmentation Limiting Display Interoperability
- 4.3.4 Accelerated Panel Burn-in in 24/7 Control-Room Duty Raising TCO
- 4.4 Indusrty Ecosystem Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Type
- 5.1.1 Rugged Displays
- 5.1.2 Open Frame Monitors
- 5.1.3 Panel-Mount Monitors
- 5.1.4 Marine and Naval-Grade Displays
- 5.1.5 Industrial Video Walls
- 5.1.6 Bar-Type/Stretch Displays
- 5.2 By Application
- 5.2.1 Human-Machine Interface (HMI)
- 5.2.2 Remote Asset and Pipeline Monitoring
- 5.2.3 Interactive Kiosks and Operator Terminals
- 5.2.4 In-plant Digital Signage and Andon Boards
- 5.2.5 Control-Room Video Walls
- 5.3 By Technology
- 5.3.1 LCD
- 5.3.2 LED Backlit LCD
- 5.3.3 OLED/AMOLED
- 5.3.4 E-Paper and Reflective Displays
- 5.3.5 Micro-LED
- 5.4 By Panel Size
- 5.4.1 Up to 14 inch
- 5.4.2 14 inch - 21 inch
- 5.4.3 21 inch - 40 inch
- 5.4.4 40 inch and Above
- 5.5 By End-Use Industry
- 5.5.1 Manufacturing
- 5.5.2 Energy and Power
- 5.5.3 Oil and Gas
- 5.5.4 Mining and Metals
- 5.5.5 Chemical and Pharmaceutical
- 5.5.6 Transportation and Logistics
- 5.5.7 Others (Water and Wastewater, Defense)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Nordics
- 5.6.2.5 Rest of Europe
- 5.6.3 South America
- 5.6.3.1 Brazil
- 5.6.3.2 Rest of South America
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South-East Asia
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Gulf Cooperation Council Countries
- 5.6.5.1.2 Turkey
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, JV, Agreements)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Samsung Display Co., Ltd.
- 6.4.2 LG Display Co., Ltd.
- 6.4.3 Panasonic Holdings Corp.
- 6.4.4 Sharp Corp.
- 6.4.5 Emerson Electric Co.
- 6.4.6 Schneider Electric SE
- 6.4.7 Siemens AG
- 6.4.8 Rockwell Automation Inc.
- 6.4.9 NEC Display Solutions, Ltd.
- 6.4.10 Advantech Co., Ltd.
- 6.4.11 Barco NV
- 6.4.12 WinMate Inc.
- 6.4.13 Planar Systems, Inc.
- 6.4.14 AU Optronics Corp.
- 6.4.15 Bosch Rexroth AG
- 6.4.16 Mitsubishi Electric Corp.
- 6.4.17 Honeywell International Inc.
- 6.4.18 Kontron AG
- 6.4.19 iBASE Technology Inc.
- 6.4.20 Beijer Electronics Group AB
- 6.4.21 Delta Electronics, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


