|
시장보고서
상품코드
2123392
대형 디스플레이 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026년-2031년)Large Format Display - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
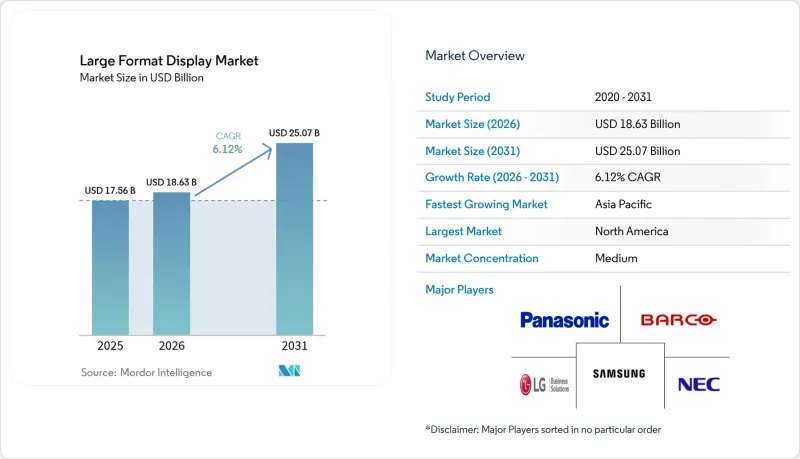
에 의하면, 대형 디스플레이 시장 규모는 2025년 175억 6,000만 달러에서 2026년에는 186억 3,000만 달러로 확대되고, 2026-2031년 CAGR 6.12%로 성장을 지속하여 2031년에는 250억 7,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 디스플레이 유형(비디오월, 독립형 디스플레이), 디스플레이 크기(32-40인치, 41-60인치, 61-80인치, 80인치 이상), 용도(실내, 실외),최종 사용자(상업, 인프라, 기관, 산업), 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 대형 디스플레이 시장 동향 및 인사이트
고휘도·고효율 LED 비디오월 솔루션의 부상
플립 칩 방식의 칩 온 보드(COB) 기술을 통해 IP67 등급의 내구성, 열 부하 감소, 3,840Hz의 주사율을 실현함으로써, 24시간 365일 가동되는 명령 센터용 디스플레이의 수명 주기 비용을 절감하고 있습니다. InfoComm 2024에서 발표된 Philips의 ‘Unite LED 5000 시리즈’는 P0.78이라는 고해상도의 공통 음극 COB 모듈을 채택하여 보증 기간을 2년에서 3년으로 연장하는 한편, 옵션으로 5년 서비스 플랜도 제공합니다. 삼성이 오랫동안 선도적인 위치를 유지해 온 것도 이와 같은 내구성에 대한 투자 덕분이지만, 아시아 팹에서의 상품화 진전으로 인해 하드웨어 이익률이 압박받고 있어, 기존 기업들은 소프트웨어 지원 제공을 통해 차별화를 꾀할 수밖에 없는 상황입니다. 대기 전력 및 네트워크 대기 전력 감축을 목표로 하는 유럽연합(EU)의 향후 규제안은 에너지 효율에 최적화된 LED 아키텍처를 더욱 촉진할 것입니다.
소매 업계 및 스마트 시티 인프라에서의 디지털 사이니지 수요 급증
리테일 미디어 네트워크는 매장 내 디지털화를 가속화하고 있지만, 매장 내 스크린에 할당되는 예산은 여전히 리테일 미디어 총예산의 1% 미만에 그치고 있으며, 2028년까지 미국 소매업체만으로도 6억 9,000만 달러의 매출 증가가 예상됩니다. 삼성은 2024년 7월 포지셔닝에서 대형 디스플레이를 스마트 시티의 ‘결합 조직’으로 규정하고, 길 안내, 교통 정보, 긴급 메시지를 하나의 관리 플랫폼에 통합하고 있습니다. VIOOH의 2024년 조사에 따르면, 최근 캠페인의 27%에 프로그래매틱 DOOH 광고 구매가 포함되어 있으며, 광고주들이 역동적이고 데이터가 풍부한 노출을 추구함에 따라 이 비율은 2026년 말까지 35%를 나타낼 것으로 전망됩니다. 아시아태평양의 지자체들은 이미 공공 입찰에 이러한 기능을 포함하고 있으며, 대형 디스플레이 시장은 재량적 구매 품목이 아닌 인프라 예산 항목으로 자리 잡고 있습니다.
대형 디스플레이 설치에 수반되는 높은 초기 설비 투자(Capex) 및 총 소유 비용(TCO)
2024년에 완공된 서울 COEX Magok Le-West의 Captivision 사가 제작한 16,000제곱피트 규모의 투명 미디어 유리 파사드가 보여주듯이, 플래그십 프로젝트의 비용은 800만 달러를 초과할 수도 있습니다. 비용에는 구조 보강, 전력 설비 업그레이드, 그리고 수년에 걸친 유지보수 계약이 포함됩니다. QSC를 12억 1,500만 달러에 인수하기로 합의한 Acuity Brands와 같은 통합 업체는 오디오비주얼,조명, 제어 시스템을 턴키 계약에 통합하고, 서비스 계약을 통해 비용을 상각하고 있습니다. 그럼에도 불구하고, 중견 기업이나 자금 조달에 어려움을 겪는 지자체는 프로젝트를 연기하거나 도입을 단일 스크린 시범 프로그램으로 제한하는 경우가 많아, 그 결과 대형 디스플레이 시장의 단기 성장세가 둔화되고 있습니다.
부문 분석
2025년에는 비디오월이 대형 디스플레이 시장 점유율의 52.02%를 차지했으나, 독립형 디스플레이는 2031년까지 연평균 성장률(CAGR) 6.64%로 가장 높은 성장률을 달성할 것으로 예측됩니다. 독립형 대형 디스플레이 시장 규모는 여전히 작지만, 드롭인 교체 및 모듈식 설치가 매우 중요한 패스트푸드점, 기업 로비, 안내 키오스크 등의 분야에서 점유율을 확대되고 있습니다. Philips의 ‘Unite LED 5000 시리즈’는 27.1인치 16:9 캐비닛 형태로 출하되며, 이를 조합하여 8K 캔버스를 형성함으로써 비디오월의 연속성과 단일 패널의 유지보수 편의성을 모두 확보하고 있습니다. LG의 118인치 ‘MAGNIT Micro LED’는 고급 호텔 업계를 위한 올인원 대체 솔루션을 제공하며, 베젤 관리를 완전히 불필요하게 만듭니다.
COB LED의 비용 감소와 폼 팩터를 초월한 관리 소프트웨어 통합이 진행됨에 따라, 성능과 가격 간의 격차는 점차 좁혀지고 있습니다. 삼성의 ‘VXT’와 LG의 ‘Business Cloud’를 통해 여러 거점의 설비에서 비디오월과 독립형 패널을 단일 대시보드 하에 통합할 수 있게 되었으며, 차별화 요소는 분석 기능 및 광고 기술과의 연동으로 이동하고 있습니다. 그 결과, 통합 업체들로부터 매니지드 서비스 계약 체결률이 상승하고 있다는 보고가 나오고 있으며, 이러한 동향은 대형 디스플레이 시장에서 지속적인 수익 향상으로 이어지고 있습니다.
80인치를 초과하는 패널은 가상 제작 스테이지, 제어실의 전체 화면 표시, 체험형 소매점의 파사드 등을 견인력으로 삼아 2031년까지 연평균 성장률(CAGR) 6.53%를 기록할 전망이며, 이는 각 크기대 중에서 가장 빠른 성장률입니다. 대조적으로, 41-60인치 모델은 기업의 허들 스페이스나 드라이브스루 메뉴 표시 등 수요에 힘입어 2025년에는 38.25%라는 최대 점유율을 차지했습니다. TCL Technology는 2024년 출하 대수의 79%가 55인치를 초과했다고 밝혔으며, 이는 점점 대형화되는 디스플레이에 대한 공급 체제가 갖춰져 있음을 보여줍니다. 건축용 설치로 인해 크기 구성에 투명성과 곡면성이 더해지고 있습니다. Captivision의 미디어 글라스와 LG의 투명 OLED 월은 디자이너가 디지털과 물리적 영역을 융합할 수 있게 해 주며, 대형 디스플레이 시장의 프리미엄 틈새 시장을 주도하고 있습니다.
에너지 소비량은 규제 측면의 불확실성 요인으로 대두되고 있습니다. 유럽연합 집행위원회가 조만간 도입할 에코디자인 규정은 고휘도 디스플레이를 대상으로 하며, 이 범주에서는 80인치를 초과하는 패널이 주류를 이룹니다. 따라서 각 벤더는 총 소유 비용을 증가시키지 않으면서 발광 출력과 더욱 엄격해진 효율 기준 간의 균형을 맞추어야 합니다.
지역별 분석
북미는 하이브리드 업무 환경 구축, 경기장 비디오월 개보수, 소매 미디어 네트워크 구축에 힘입어 2025년 대형 디스플레이 시장 매출의 35.25%를 차지했습니다. 덕트로닉스(Ductronics)는 UBS 아레나 및 알레지언트 스타디움(Alegiant Stadium) 등의 아레나 프로젝트 수주에 힘입어 2025 회계연도 1분기 라이브 이벤트 부문 매출이 18% 급증하여 1억 900만 달러에 달했다고 보고했습니다. 다만, 막대한 컨설팅 비용 및 IT 관련 지출로 인해 단기적인 이익률은 압박을 받았습니다. 프로그래매틱 DOOH(디지털 옥외 광고) 부문에서는 2024년 미국 광고주들이 평균 29%의 지출 증가를 기록하며, 정적 간판에서 클라우드 관리형 스크린으로의 전환이 가속화되었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.68%를 나타낼 것으로 예측되며, 이는 다른 어떤 지역보다 빠른 속도입니다. TCL 테크놀로지의 광저우에 위치한 G8.6 산화물 라인은 2024년 한 해 동안 풀가동되어 CSOT 매출의 21%를 차지했으며, 대형 LCD 및 LED 기판 분야에서 중국의 우위를 공고히 했습니다. 한국의 LG전자는 Mo-Sys Engineering에 투자하여 마이크로 LED 패널과 XR 카메라 트래킹을 통합함으로써, 인카메라 VFX를 채택하는 지역 스튜디오를 타겟으로 삼고 있습니다. 인도의 ‘스마트 시티 미션’은 2027년까지 100개 도시 중심부에 실시간 승객 정보 시스템을 도입할 계획이지만, 조달 체계의 분산과 재정적 제약으로 인해 단기적인 도입 규모는 제한될 전망입니다.
유럽은 가장 엄격한 규제적 역풍에 직면해 있습니다. 유럽집행위원회가 2024년 11월에 실시한 의견 수렴에서는 대기 전력 상한선을 강화하고 수리 가능성을 의무화함으로써, 연간 7,000만 대가 판매되는 전자 디스플레이의 전력 소비를 대폭 줄이는 것을 목표로 하고 있습니다. 제조업체들은 재활용 소재의 사용 및 우려 물질의 추적을 의무화받게 되어 시장 진입 장벽이 높아지고 있습니다. 독일, 프랑스, 영국에서는 멀티모달 교통 허브용 디지털 사이니지를 우선시하고 있으며, 기존의 종이 시간표를 광고 매체로도 기능하는 동적 디스플레이로 전환하고 있습니다.
남미, 중동 및 아프리카 3개 지역을 합쳐도 전 세계 매출에서 차지하는 비중은 10% 미만이지만, 장기적인 성장 기회를 내포하고 있습니다. 브라질과 멕시코에서는 패스트푸드점 메뉴의 디지털화가 진행되고 있지만, 경제 상황의 변동으로 인해 설비 투자가 억제되고 있습니다. 아랍에미리트(UAE)와 사우디아라비아에서는 관광 진흥책의 일환으로, 공항이나 쇼핑몰에 몰입형 파사드를 설치하기 위해 스마트시티 예산을 배정하고 있습니다. 아프리카 일부 지역에서는 전력 공급 안정성 문제로 인해 24시간 365일 가동이 여전히 제한되고 있지만, 통신사의 통신탑에 설치된 디스플레이가 대체 광고 거점으로 부상하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the large format display market size is expected to grow from USD 17.56 billion in 2025 to USD 18.63 billion in 2026 and is forecast to reach USD 25.07 billion by 2031 at 6.12% CAGR over 2026-2031.
This report is Segmented by Display Type (Video Wall, Stand-Alone Display), Display Size (32-40 Inch, 41-60 Inch, 61-80 Inch, Above 80 Inch), Application (Indoor, and Outdoor), End-User (Commercial, Infrastructural, Institutional and Industrial), and Geography (North America, South America, Europe, Asia-Pacific, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Large Format Display Market Trends and Insights
Rise in High-Brightness, Energy-Efficient LED Video-Wall Solutions
Flip-chip chip-on-board (COB) technology is delivering IP67 durability, lower thermal loads, and 3,840 Hz refresh rates, cutting lifetime operating costs for 24/7 command-center displays. Philips' Unite LED 5000 Series, unveiled at InfoComm 2024, uses common-cathode COB modules as fine as P0.78 to extend warranty coverage from 2 to 3 years, with optional 5-year service plans. Samsung's long-running dominance likewise stems from similar durability investments, yet increasing commoditization across Asian fabs is compressing hardware margins and pushing incumbents to differentiate through software support offerings. Upcoming European Union draft rules aimed at reducing standby and network-standby power will further favor energy-optimized LED architectures.
Soaring Demand for Digital Signage in Retail and Smart-City Infrastructure
Retail-media networks are accelerating in-store digitization, but in-aisle screens still capture less than 1% of total retail-media budgets, translating into a USD 690 million upside for U.S. retailers alone by 2028. Samsung's July 2024 positioning frames large format displays as the connective tissue for smart cities, integrating wayfinding, transit alerts, and emergency messaging into one managed platform. VIOOH's 2024 study found 27% of recent campaigns included programmatic DOOH buys, a share likely to reach 35% by end-2026 as advertisers seek dynamic, data-enriched impressions. Municipal agencies in Asia-Pacific are already embedding similar functionality into public tenders, making the large format display market an infrastructure line item rather than a discretionary purchase.
High Initial Capex and Total Cost of Ownership for Large Format Installations
Flagship projects can exceed USD 8 million, as shown by Captivision's 16,000-square-foot transparent media-glass facade at COEX Magok Le-West in Seoul, completed in 2024. Costs encompass structural reinforcements, power upgrades, and multi-year maintenance contracts. Integrators such as Acuity Brands, which agreed to acquire QSC for USD 1.215 billion, are bundling audio-visual, lighting, and control systems into turnkey deals to amortize expenses over service contracts. Nevertheless, mid-market enterprises and cash-constrained municipalities often delay projects or limit deployments to single-screen pilot programs, slowing the near-term trajectory of the large format display market.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of 4K/8K and Interactive Displays Across Education and Corporate Collaboration
- AI-Driven, Cloud-Based CMS Enabling Real-Time Content Personalization
- Intensifying Competition from Mobile and Online Advertising Channels
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, video walls captured 52.02% of the large format display market share, while stand-alone displays are projected to achieve the fastest growth rate at 6.64% CAGR through 2031. The large format display market size for stand-alone units remains smaller but is gaining share in quick-service restaurants, corporate lobbies, and wayfinding kiosks, where drop-in replacement and modular mounting are paramount. Philips' Unite LED 5000 Series ships in 27.1-inch 16:9 cabinets that snap together into 8K canvases, blending video-wall continuity with single-panel serviceability. LG's 118-inch MAGNIT Micro LED provides an All-in-One alternative for luxury hospitality, circumventing bezel management altogether.
The performance-price gap is narrowing as COB LED costs fall and management software converges across form factors. Samsung's VXT and LG Business Cloud allow multi-site fleets to mix video walls and stand-alone panels under one dashboard, shifting differentiation to analytics and ad-tech hooks. Consequently, integrators report higher attach rates for managed-service contracts, a trend that elevates recurring revenue in the large format display market.
Panels exceeding 80 inches are on track to register a 6.53% CAGR to 2031, the quickest among size tiers, driven by virtual-production stages, control-room overviews, and experiential retail facades. In contrast, 41-60 inch models held the lion's share at 38.25% in 2025 thanks to corporate huddle spaces and drive-through menus. TCL Technology revealed that 79% of its 2024 shipments exceeded 55 inches, underscoring supply readiness for ever-larger canvases. Architectural installations add transparency and curvature to the size mix; Captivision's media glass and LG's Transparent OLED walls enable designers to meld digital and physical realms, feeding premium niches of the large format display market.
Energy consumption looms as a regulatory wildcard. The European Commission's forthcoming ecodesign rules target high-nit displays, a category dominated by panels larger than 80 inches. Vendors must therefore balance luminous output against stricter efficiency thresholds without inflating total cost of ownership.
Complete Report Scope:
- By Display Type
- Video Wall
- Stand-Alone Display
- By Display Size
- 32-40 inch
- 41-60 inch
- 61-80 inch
- Above 80 inch
- By Application
- Indoor
- Outdoor
- By End-User
- Commercial
- Infrastructural
- Institutional and Industrial
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Mexico
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 35.25% of 2025 revenue in the large format display market, buoyed by hybrid-work upgrades, stadium video-wall renovations, and retail-media network rollouts. Daktronics reported an 18% spike in Live Events revenue to USD 109 million in Q1 FY2025 after winning arena projects such as UBS Arena and Allegiant Stadium, though heavy consulting and IT outlays compressed near-term margins. Programmatic DOOH saw U.S. advertisers boost spend by 29% on average in 2024, advancing the shift from static boards to cloud-managed screens.
Asia-Pacific is projected to log a 6.68% CAGR to 2031, the fastest of any region. TCL Technology's Guangzhou G8.6 oxide line ran at full capacity throughout 2024 and contributed 21% of CSOT revenue, cementing China's dominance in large format LCD and LED substrates. South Korea's LG Electronics invested in Mo-Sys Engineering to integrate Micro LED panels with XR camera tracking, targeting regional studios adopting in-camera VFX. India's Smart-City Mission plans to integrate real-time passenger information systems into 100 urban centers by 2027, though fragmented procurement and fiscal constraints moderate near-term volumes.
Europe faces the most stringent regulatory headwinds. The European Commission's November 2024 consultation aims to slash electricity use among the 70 million electronic displays sold annually by tightening standby-power caps and mandating repairability. Vendors must embed recycled content and substance-of-concern tracking, raising entry barriers. Germany, France, and the UK are prioritizing digital signage for multimodal transit hubs, converting legacy paper timetables to dynamic displays that double as advertising inventory.
South America and the Middle East and Africa collectively generate under 10% of global revenue but represent long-range opportunities. Brazil and Mexico are digitizing quick-service restaurant menus, yet economic volatility constrains capital spend. The UAE and Saudi Arabia allocate smart-city budgets to immersive facades in airports and malls aligned with tourism initiatives. Power-reliability issues in parts of Africa continue to limit 24/7 operation, though telco tower-side displays are emerging as alternative advertising nodes.
- Samsung Electronics Co., Ltd.
- LG Display Co., Ltd.
- Sharp NEC Display Solutions, Ltd.
- Leyard Optoelectronic Co., Ltd.
- Barco NV
- Panasonic Holdings Corp.
- Sony Group Corp.
- AU Optronics Corp.
- TPV Technology Ltd.
- ViewSonic Corp.
- Christie Digital Systems USA, Inc.
- Daktronics, Inc.
- Absen Optoelectronic Co., Ltd.
- Unilumin Group Co., Ltd.
- Delta Electronics, Inc.
- AOTO Electronics Co., Ltd.
- Planar Systems, Inc.
- DynaScan Technology Corp.
- Koninklijke Philips N.V.
- BenQ Corp.
- E Ink Holdings, Inc.
- Prysm Systems, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise In High-Brightness, Energy-Efficient LED Video-Wall Solutions
- 4.2.2 Soaring Demand For Digital Signage In Retail And Smart-City Infrastructure
- 4.2.3 Proliferation Of 4K/8K And Interactive Displays Across Education And Corporate Collaboration
- 4.2.4 Cost-Per-Inch Decline Of Large-Area LCD/LED Panels
- 4.2.5 Virtual-Production LED Volumes Accelerating Studio Adoption
- 4.2.6 AI-Driven, Cloud-Based CMS Enabling Real-Time Content Personalization
- 4.3 Market Restraints
- 4.3.1 High Initial Capex And TCO For Large-Format Installations
- 4.3.2 Intensifying Competition From Mobile / Online Advertising Channels
- 4.3.3 Installation And Maintenance Complexity Across Multi-Panel Walls
- 4.3.4 Emerging Energy-Consumption Regulations For High-Nit Displays
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Display Type
- 5.1.1 Video Wall
- 5.1.2 Stand-Alone Display
- 5.2 By Display Size
- 5.2.1 32-40 inch
- 5.2.2 41-60 inch
- 5.2.3 61-80 inch
- 5.2.4 Above 80 inch
- 5.3 By Application
- 5.3.1 Indoor
- 5.3.2 Outdoor
- 5.4 By End-User
- 5.4.1 Commercial
- 5.4.2 Infrastructural
- 5.4.3 Institutional and Industrial
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Mexico
- 5.5.2.3 Argentina
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Samsung Electronics Co., Ltd.
- 6.4.2 LG Display Co., Ltd.
- 6.4.3 Sharp NEC Display Solutions, Ltd.
- 6.4.4 Leyard Optoelectronic Co., Ltd.
- 6.4.5 Barco NV
- 6.4.6 Panasonic Holdings Corp.
- 6.4.7 Sony Group Corp.
- 6.4.8 AU Optronics Corp.
- 6.4.9 TPV Technology Ltd.
- 6.4.10 ViewSonic Corp.
- 6.4.11 Christie Digital Systems USA, Inc.
- 6.4.12 Daktronics, Inc.
- 6.4.13 Absen Optoelectronic Co., Ltd.
- 6.4.14 Unilumin Group Co., Ltd.
- 6.4.15 Delta Electronics, Inc.
- 6.4.16 AOTO Electronics Co., Ltd.
- 6.4.17 Planar Systems, Inc.
- 6.4.18 DynaScan Technology Corp.
- 6.4.19 Koninklijke Philips N.V.
- 6.4.20 BenQ Corp.
- 6.4.21 E Ink Holdings, Inc.
- 6.4.22 Prysm Systems, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment