|
시장보고서
상품코드
2123401
진공포장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Vacuum Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
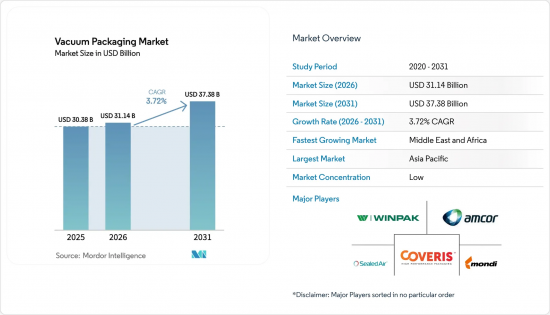
에 의하면, 진공포장 시장 규모는 2025년 303억 8,000만 달러, 2026년 311억 4,000만 달러에서 2031년까지 373억 8,000만 달러로 확대된다고 예측되고 있어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 3.72%를 나타낼 전망입니다.
본 보고서는 포장 유형(연포장, 경질 포장), 소재(폴리에틸렌,폴리아미드, 폴리프로필렌 등), 최종 사용자 산업(식품, 헬스케어 및 의약품, 공업 제품 등), 기계 유형(열성형기, 챔버식 진공 실러, 외부/에지식 진공 실러 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 진공포장 시장 동향 및 인사이트
포장 식품 및 편의 식품에 대한 수요 증가
2025년에는 진공 밀봉된 단백질 보울과 수비드 조리된 메인 요리가 식료품점 진열대에서 더욱 널리 자리 잡음에 따라, 즉석식사의 취급량은 전년 대비 18% 증가했습니다. 같은 기간 동안, 밀키트 기업들은 냉동하지 않고도 최대 10일간 관능적 품질을 유지할 수 있는 분량 조절된 파우치를 활용함으로써 주문 빈도를 2배로 늘렸습니다. 현재 풀필먼트 센터에서는 더 대규모의 일괄 출하가 선호되고 있으며, 이를 통해 단위당 물류 비용을 약 13% 절감할 수 있게 되었지만, 그 대신 진공포장 형태라면 견딜 수 있는 것보다 더 많은 취급 주기에 포장이 노출되고 있습니다. 네슬레는 브라질 내 냉장 식품 생산 능력 확대를 위해 5억 레알(9,500만 달러)을 예산으로 편성했습니다. 이는 2025년까지 보급률이 60%를 넘어설 것으로 예상되는 맞벌이 가구를 타겟으로 한 것입니다. 소비자들은 집으로 가져갈 수 있는 편의성을 위해 20-25%의 가격 프리미엄을 기꺼이 수용하는 경향이 있으며, 지난해 식품 인플레이션이 완화되었음에도 불구하고 진공포장 상품군은 두 자릿수 성장을 유지하고 있습니다.
소매업체들의 식품 안전 규정 준수 관심 고조
규제 당국은 저산성·저산소 제품에서 보툴리눔균(Clostridium botulinum)의 위험에 주목하고 있습니다. 영국 식품표준청(FSA)은 현재 판매 기간이 10일을 초과하는 냉장 진공포장 제품에 대해 6 로그의 포자 감소를 입증하거나 pH 5.0 미만 등의 추가 요건을 충족할 것을 의무화하고 있습니다. 미국에서는 미국 농무부 식품안전검사국(USDA FSIS)이 9 CFR 318.300에 근거하여 기밀성 기준을 시행하고 있으며, 21 CFR 113에서는 열처리 검증 절차가 규정되어 있습니다. 소매업체는 분기마다 공급업체를 감사하고, 기준을 충족하지 못하는 업체에 대해서는 30일 이내에 거래를 중단하고 있습니다. 이러한 움직임은 미생물학 실험실이나 유통기한 시험실을 보유한 가공업체에 유리하게 작용하고 있습니다. 그 결과, 1차 공급업체는 검증 인프라에 투자할 자금력이 없는 소규모 지역 업체에 대한 우위를 더욱 확대되고 있습니다.
산업용 진공 기계의 높은 자본 비용
엔트리 레벨 챔버 실러는 1만 5,000달러 정도부터 시작하지만, 완전한 열성형·충진·밀봉 라인은 350만 달러를 초과하여, 이 가격 차이를 메우기 위해 남미와 남아시아의 소규모 위탁 포장 업체들은 어려움을 겪고 있습니다. 이 지역에서의 자금 조달에는 선진국 시장의 금리보다 300-500 베이시스 포인트 높은 프리미엄이 부과되기 때문에 투자 회수 기간은 7년 이상에 달하게 됩니다. IFC 등 개발 금융 기관은 2025년에 브라질의 컨버터 기업에 6,500만 유로(7,300만 미달러)를 대출했으나, 이러한 프로그램의 대상 기업 중 5% 미만에만 혜택이 미쳤습니다. 각 공급업체들은 인도와 인도네시아에서 ‘패키지 단위 과금’의 시범 도입을 추진하고 있지만, 가공업체들이 장기적인 비용 불확실성을 우려하고 있어 도입률은 2% 미만에 그치고 있습니다.
부문 분석
2025년 현재, 진공포장 시장 점유율의 78.43%를 연포장이 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 4.23%를 나타낼 것으로 예측됩니다. 이는 트레이에 비해 수지 사용량을 최대 50%까지 줄일 수 있어, 수출 경로에서는 1kg당 0.10달러 가까운 운임 절감으로 이어지며, 전자상거래용 토트백의 적재 효율 향상도 실현합니다. 슈르 플렉서블스(Surre Flexibles)는 2025년, 슬라이스된 델리 미트를 21일간 보관할 수 있으며, 확대 생산자 책임(EPR) 규정을 준수하는 재활용 가능한 폴리에틸렌 단일 소재 파우치를 출시했습니다. 경질 트레이는 21.57%의 시장 점유율을 유지했으나, 금형 비용의 급등으로 인해 SKU 확대가 저해되어 성장률은 2.8%에 그쳤습니다. Klockner Pentaplast사의 스캐빈저가 내장된 PET 트레이는 살코기의 신선도 유지 기간을 18일로 연장했으나, 그 채택은 15%의 가격 인상을 소비자에게 전가할 수 있는 프리미엄 프라이빗 브랜드에 집중되어 있습니다.
전자상거래에서는 플렉서블 패키지의 장점이 두드러집니다. 냉장 토트 1개당 적재량이 트레이보다 30% 많아, 라스트 마일 비용 절감과 파손 감소로 이어집니다. 커버이스(Coveris)사의 보고서에 따르면, 2025년 밀키트용 연포장 솔루션은 22%의 성장이 예상되는 반면, 동등한 경질 포장은 3% 감소할 것으로 나타나, 판매 채널별 선호도의 차이가 뚜렷하게 드러나고 있습니다. ISO 18601에서는 다층 트레이보다 단일 소재의 플렉서블 필름에 더 높은 재활용 가능성 점수가 부여되어 있어, 브랜드 소유자가 파우치를 선택하도록 유도하고 있습니다. 외식 산업은 고온 재가열을 견딜 수 있는 경질 트레이의 마지막 보루로 남아 있지만, 이 틈새 시장은 진공포장 시장 규모의 10% 미만을 차지할 뿐입니다.
2025년에는 저렴한 비용, 폭넓은 밀봉 온도 범위, 그리고 확립된 압출 성형 기반에 힘입어 폴리에틸렌이 시장 점유율의 38.53%를 차지했습니다. 폴리프로필렌은 핫 필(hot fill) 및 레토르트 가공에 적합한 반면, 틈새 시장인 산소 차단 용도에는 EVOH 및 폴리아미드가 사용되고 있습니다. 폴리아미드는 2031년까지 연평균 성장률(CAGR)이 4.54%로 가장 높은 성장세를 보이고 있습니다. 이는 산소 차단성이 폴리에틸렌보다 최대 7배나 뛰어나며, 훈제 육류나 동결 건조 의약품에 필수적이기 때문입니다.
다우(Dow)사가 2025년 출시 예정인 ‘INNATE TF’ 수지 제품군은 라미네이트 가공 없이도 15 cc/m²/일의 산소 투과율을 실현함으로써 폴리아미드의 입지를 위협하는 것을 목표로 하고 있습니다. 그러나 가격이 12-15% 비싸기 때문에 현재 채택률은 약 5%에 그치고 있습니다. 보레알리스(Borealis)사의 ‘Borstar’ 시리즈는 내천자성을 향상시켜, 가공업체가 필름 두께를 약 12% 얇게 만들 수 있게 함으로써, 결과적으로 1팩당 0.02달러의 비용 절감으로 이어집니다. 의료 분야 고객들이 폴리아미드의 부상을 뒷받침하고 있습니다. 이는 ISO 11607 검증 과정에서 134°C에서의 멸균 처리 내성이 요구되기 때문입니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 40.77%를 차지했습니다. 이는 중국의 480만 톤에 달하는 진공포장 육류 수출과 인도의 콜드체인 인프라 구축이 주도한 결과입니다. 일본에서는 의약품 포장에 대한 실시간 GMP 모니터링이 의무화되어 데이터 로깅 기능이 탑재된 열성형기 도입이 촉진되고 있습니다. 한국에서는 1인 가구가 전체 가구의 30%를 넘어섬에 따라 편의점의 진공포장 식품 품목이 18% 확대되었습니다. 호주의 가공업체들은 중동 및 북미로의 고급 식품 수출에 대응하기 위해 배리어 포장 라인에 1억 2,000만 호주 달러(7,800만 달러)를 투자했습니다.
중동 및 아프리카는 가장 빠르게 성장하는 지역으로, 2031년까지 연평균 성장률(CAGR)이 5.22%를 나타낼 것으로 전망됩니다. UAE의 ‘식량 안보 전략 2050’에서는 10일 분량의 단백질 비축을 의무화하고 있으며, 이에 따라 슈퍼마켓에서는 냉장 농산물의 진공포장이 진행되어 현재 냉장 진열대의 22%를 차지하고 있습니다. 사우디아라비아는 2024년부터 2026년까지 식품 가공 인프라에 80억 사우디 리얄(21억 달러)을 배정했습니다. 남아프리카공화국 시장 점유율의 68%를 차지하는 3대 식품 소매업체는 재고 손실을 줄이기 위해 자사 브랜드 육류 제품에 대해 진공포장을 의무화하고 있습니다.
2025년 매출액 중 북미와 유럽을 합치면 45%를 차지했으나, 성장률은 각각 3.2%와 2.9%로 소폭에 그쳤습니다. FDA의 21 CFR 113 규정을 준수하려면 SKU당 8만 달러의 비용이 소요되지만, 반면 독일의 2024년 포장법에 따르면 재활용이 불가능한 라미네이트 소재에 대해 1kg당 0.52유로의 EPR(생산자 책임 회수) 요금이 부과됩니다. 캐나다에서 검토 중인 일회용 플라스틱 규제로 인해 투자 시기가 불투명해지고 있습니다. 남미는 니어쇼어링과 IFC(국제금융공사)가 지원하는 자본 투입으로 생산 능력이 확대되어 4.1%의 성장세를 보이고 있습니다. 테트라팩의 메히카리 공장 설비 갱신을 통해 북미용 니어쇼어링 프로그램을 위한 열성형 제품의 생산 능력이 60% 확대되었습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the vacuum packaging market size is projected to expand from USD 30.38 billion in 2025 and USD 31.14 billion in 2026 to USD 37.38 billion by 2031, registering a CAGR of 3.72% between 2026 to 2031.
This report is Segmented by Packaging Type (Flexible Packaging, and Rigid Packaging), Material (Polyethylene, Polyamide, Polypropylene, and More), End-User Industry (Food, Healthcare and Pharmaceutical, Industrial Goods, and More), Machinery Type (Thermoformers, Chamber Vacuum Sealers, External/ Edge Vacuum Sealers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Vacuum Packaging Market Trends and Insights
Growing Demand for Packaged and Convenience Foods
Ready-to-eat meal volumes increased 18% year-over-year in 2025, as vacuum-sealed protein bowls and sous-vide entrees secured a broader presence on grocery shelves. Meal-kit firms doubled the order frequency over the same period, relying on portion-controlled pouches that maintain sensory quality for up to 10 days without freezing. Fulfillment centers now favor larger, consolidated shipments, trimming logistics cost per unit by roughly 13% yet exposing packs to more handling cycles that vacuum formats withstand. Nestle has earmarked BRL 500 million (USD 95 million) to expand chilled-meal capacity in Brazil, targeting dual-income households, which were expected to surpass 60% penetration by 2025. Consumers are willing to accept a 20-25% price premium for grab-and-go convenience, supporting double-digit expansion in vacuum-packed offerings, even as food inflation moderated last year.
Increasing Focus on Food-Safety Compliance by Retailers
Regulators have zeroed in on Clostridium botulinum risk in low-acid, reduced-oxygen items. The UK Food Standards Agency now requires chilled vacuum packs marketed beyond 10 days to show a 6-log spore reduction or add hurdles such as pH below 5.0. In the United States, USDA FSIS enforces hermetic standards under 9 CFR 318.300, while 21 CFR 113 covers thermal validation. Retailers audit suppliers quarterly and delist non-conformers within 30 days, a move that favors converters owning microbiology labs and shelf-life chambers. As a result, tier-1 suppliers lengthen their lead over small regionals that lack capital for validation infrastructure.
High Capital Cost of Industrial Vacuum Machinery
Entry-level chamber sealers start at around USD 15,000, while full thermoform-fill-seal lines exceed USD 3.5 million, a gap that small co-packers in South America and South Asia struggle to bridge. Financing in those regions carries premiums of 300-500 bps above developed-market rates, pushing payback beyond seven years. Development lenders, such as the IFC, injected EUR 65 million (USD 73 million) into a Brazilian converter in 2025; however, such programs reach less than 5% of eligible firms. Vendors are piloting pay-per-pack fees in India and Indonesia, yet uptake stays below 2% because processors fear long-term cost uncertainty.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of E-Commerce Grocery Channels
- Automation of High-Speed Thermoform Lines
- Environmental Concerns over Multi-Layer Plastic Films
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Flexible variants accounted for 78.43% of the vacuum packaging market share in 2025 and are projected to grow at a 4.23% CAGR through 2031. They use up to 50% less resin than trays, resulting in freight savings of nearly USD 0.10 per kilogram on export routes and enabling better cube utilization in e-commerce totes. Schur Flexibles launched a recyclable polyethylene mono-material pouch in 2025 that preserves sliced deli meats for 21 days while complying with Extended Producer Responsibility rules. Rigid trays kept a 21.57% share but grew only 2.8% as higher tooling costs hindered SKU proliferation. Klockner Pentaplast's PET tray with built-in scavengers now extends the color life of red meat to 18 days; however, adoption is concentrated in premium private labels willing to pass a 15% price increase to shoppers.
E-commerce accentuates the benefits of flexible packs, which stack 30% more units per refrigerated tote than trays, resulting in lower last-mile costs and fewer breakages. Coveris reported 22% growth in flexible solutions for meal kits in 2025, whereas rigid equivalents slipped 3%, underscoring channel preference. ISO 18601 assigns higher recyclability scores to mono-material flexible films than to multi-substrate trays, encouraging brand owners to opt for pouches. Foodservice remains the last stronghold for rigid trays because they endure high-heat reheating, a niche representing under 10% of vacuum packaging market size.
Polyethylene represented 38.53% of the market share in 2025, driven by its low cost, broad sealing window, and installed extrusion base. Polypropylene is suitable for hot-fill and retort duty, while niche oxygen-barrier jobs rely on EVOH and polyamide. Polyamide logs the quickest 4.54% CAGR through 2031, as its oxygen barrier is up to seven times tighter than polyethylene, making it essential for cured meats and lyophilized drugs.
Dow's 2025 INNATE TF resin family aims to dethrone polyamide by achieving 15 cc/m2/day oxygen rates without lamination; however, uptake currently sits at around 5% due to 12-15% price premiums. Borealis' Borstar line enhances puncture resistance, enabling converters to reduce film gauge by approximately 12%, resulting in a savings of USD 0.02 per pack. Healthcare customers underpin polyamide's rise because ISO 11607 validation counts on its toughness during 134 °C sterilization.
Complete Report Scope:
- By Packaging Type
- Flexible Packaging
- Rigid Packaging
- By Material
- Polyethylene (PE)
- Polyamide (PA)
- Polypropylene (PP)
- Other Materials
- By End-User Industry
- Food
- Healthcare and Pharmaceutical
- Industrial Goods
- Other End -user Industries
- By Machinery Type
- Thermoformers
- Chamber Vacuum Sealers
- External / Edge Vacuum Sealers
- Other Machinery Types
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 40.77% of global revenue in 2025, fueled by China's 4.8 million-ton vacuum-packed meat exports and India's cold-chain build-out. Japan mandates real-time GMP monitoring in pharma packs, driving adoption of data-logging thermoformers. South Korea's convenience stores enlarged vacuum-meal offerings by 18% as single-person households topped 30% of dwellings. Australia's processors invested AUD 120 million (USD 78 million) in barrier lines to serve premium exports to the Middle East and North America.
The Middle East and Africa are the fastest risers, with a 5.22% CAGR through 2031. The UAE's Food Security Strategy 2050 requires a ten-day protein reserve, prompting supermarkets to vacuum-pack chilled produce, which now occupies 22% of their fridge space. Saudi Arabia allocated SAR 8 billion (USD 2.1 billion) to food-processing infrastructure between 2024 and 2026. South Africa's top three grocers, which control 68% of the trade, have mandated vacuum packs for private-label meats to reduce shrinkage.
North America and Europe together accounted for 45% of 2025 sales, but grew modestly at 3.2% and 2.9%, respectively. FDA 21 CFR 113 compliance adds up to USD 80,000 per SKU, while Germany's 2024 packaging law imposes EUR 0.52 per kilogram EPR fees on non-recyclable laminates. Canada's pending single-use plastics rules cloud investment timing. South America advances at 4.1% as nearshoring and IFC-backed capital inject capacity. Tetra Pak's Mexicali upgrade expands thermoform output 60% for North American nearshoring programs.
- Amcor plc
- Sealed Air Corporation
- Mondi Group
- Winpak Ltd.
- Coveris Holdings SA
- Schur Flexibles Group
- Klockner Pentaplast Group
- Plastopil Ltd.
- Swiss Pac Pvt Ltd.
- Multivac Sepp Haggenmuller SE
- Ulma Packaging
- Wipak Oy
- Dow Inc.
- Bemis (An Amcor Brand)
- Constantia Flexibles
- ProAmpac LLC
- CVP Systems Inc.
- LINPAC Packaging
- Allfo Vakuumverpackungen
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for Packaged and Convenience Foods
- 4.2.2 Increasing Focus on Food-Safety Compliance by Retailers
- 4.2.3 Rapid Expansion of E-Commerce Grocery Channels
- 4.2.4 Automation of High-Speed Thermoform Lines
- 4.2.5 Integration of Smart Sensors for Real-Time Quality Checks
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of Industrial Vacuum Machinery
- 4.3.2 Environmental Concerns Over Multi-Layer Plastic Films
- 4.3.3 Regulatory Pressure on PVDC and Other Halogenated Barriers
- 4.3.4 Limited Recycling Streams for Contaminated Flexible Films
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Packaging Type
- 5.1.1 Flexible Packaging
- 5.1.2 Rigid Packaging
- 5.2 By Material
- 5.2.1 Polyethylene (PE)
- 5.2.2 Polyamide (PA)
- 5.2.3 Polypropylene (PP)
- 5.2.4 Other Materials
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Healthcare and Pharmaceutical
- 5.3.3 Industrial Goods
- 5.3.4 Other End -user Industries
- 5.4 By Machinery Type
- 5.4.1 Thermoformers
- 5.4.2 Chamber Vacuum Sealers
- 5.4.3 External / Edge Vacuum Sealers
- 5.4.4 Other Machinery Types
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Sealed Air Corporation
- 6.4.3 Mondi Group
- 6.4.4 Winpak Ltd.
- 6.4.5 Coveris Holdings SA
- 6.4.6 Schur Flexibles Group
- 6.4.7 Klockner Pentaplast Group
- 6.4.8 Plastopil Ltd.
- 6.4.9 Swiss Pac Pvt Ltd.
- 6.4.10 Multivac Sepp Haggenmuller SE
- 6.4.11 Ulma Packaging
- 6.4.12 Wipak Oy
- 6.4.13 Dow Inc.
- 6.4.14 Bemis (An Amcor Brand)
- 6.4.15 Constantia Flexibles
- 6.4.16 ProAmpac LLC
- 6.4.17 CVP Systems Inc.
- 6.4.18 LINPAC Packaging
- 6.4.19 Allfo Vakuumverpackungen
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment