

|
시장보고서
상품코드
2123403
박막 봉지 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Thin Film Encapsulation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
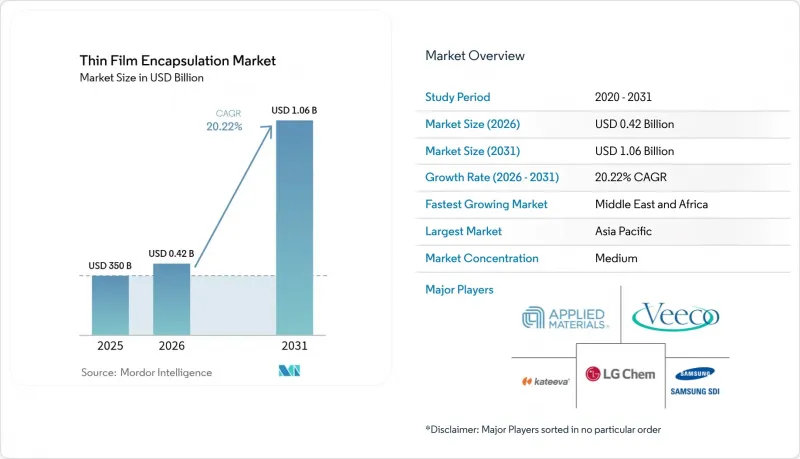
에 의하면, 2026년 박막 봉지 시장 규모는 4억 2,077만 달러로 추정되고 있어 2025년 3억 5,000만 달러에서 확대되어, 2031년에는 10억 6,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 20.22%를 나타낼 것으로 전망됩니다.
본 보고서는 기술별(플라즈마 강화 화학 기상 증착법, 원자층 증착법 등), 층 구조별(무기 다층 배리어, 유기 다층 배리어 등), 용도별(플렉서블 OLED 디스플레이 등), 성막 장비 유형별(클러스터 PECVD 시스템 등),최종 이용 산업별(소비자용 전자기기, 재생에너지 등), 그리고 지역별로 분류되어 있습니다.
세계 박막 봉지 시장 동향 및 인사이트
한국 및 중국의 AMOLED 생산 능력 확대가 ALD-TFE 장비 수주를 견인하고 있습니다.
삼성디스플레이는 2026년 생산 개시를 목표로 한 제8.6세대 IT용 OLED 라인에 30억 달러를 투자한 반면, BOE는 동급 공장에 87억 달러를 투자했습니다. 이러한 프로젝트로 인해 ALD 봉지 장비 수주가 급증했습니다. 이는 이 기술이 차세대 IT 및 자동차용 패널에 필수적인, 저온에서 균일하고 핀홀이 없는 배리어 층을 제공하기 때문입니다. 경쟁 심화로 인해 한국 제조업체들의 출하량 주도권이 회복된 한편, 아시아태평양 파운드리 전반에 걸쳐 ALD에 대한 수요가 확대되고 있습니다.
EU 및 북미의 자동차용 곡면 디스플레이 의무화
이음매 없는 계기판을 권장하는 규제 지침에 따라 곡면 OLED 대시보드 설계 채택이 가속화되고 있습니다. 이러한 모듈에는 진동, 자외선 및 -40°C의 온도 사이클을 견딜 수 있는 밀봉층이 필요합니다. 삼성이 고도의 방습 장벽을 갖춘 탠덤 OLED를 채택한 것은 이러한 변화를 상징하는 것으로, 2026년까지 자동차용 디스플레이에 대한 총 지출이 모니터 패널 매출을 넘어설 것으로 예상되는 가운데, 삼성은 수익을 창출할 준비를 갖추고 있습니다.
6세대 ALD 클러스터 라인의 막대한 설비 투자
차세대 ALD 스택 도입에는 라인당 1억 달러 이상의 투자가 필요하며, 이로 인해 중견 제조업체들이 시장 진입을 포기하면서 기술 보급이 더뎌지고 있습니다. 많은 아시아 제조 공장에서는 여전히 구형 클러스터 장비의 감가상각이 진행 중이며, 수율 향상이 뚜렷한 경우에도 업그레이드 경제성이 복잡해지고 있습니다. 이러한 비용 장벽으로 인해 박막 봉지 시장 전체에서 최고 수준의 봉지 기술이 균일하게 보급되는 것이 지연되고 있습니다.
부문 분석
ALD는 25.85%의 연평균 성장률(CAGR)이 예상되는 반면, PECVD는 2025년에 매출의 38.90%를 차지하고 있어, 박막 봉지 시장의 과도기가 두드러지게 나타나고 있습니다. ALD 필름은 10-6 g/m2/일의 수증기 투과율을 달성하여 OLED의 수명을 연장하고, 접이식 기판의 채택을 가능하게 합니다. 롤 투 롤(R2R) ALD는 웨어러블 제품 생산에 적합한 웹 속도까지 처리량을 향상시켰으며, 한편 공간 ALD는 기판 크기의 한계를 극복해 나가고 있습니다. PECVD는 대량 생산이 요구되는 리지드 패널에서 여전히 선호되고 있습니다. VTE 및 OVPD는 배리어 층의 극한 성능보다 재료의 호환성이 우선시되는 틈새 발광 스택 분야에서 계속해서 채택되고 있습니다. 2023년 SID로부터 표창을 받은 저온 ALD 화학 공법을 통해 양산형 폴더블 디바이스용 폴리이미드 기판의 실용화가 가능해졌으며, 기술의 다양화가 진행되었습니다. 그 결과, ALD 장비 제조업체들은 사상 최대의 수주 잔고를 기록하고 있으며, 한국, 중국, 미국에 걸친 지역 공급망 생태계를 활성화시키고 있습니다.
박막 봉지 시장에서는 비용 중심의 SKU에서 PECVD에 대한 의존도가 계속되고 있습니다. 이는 PECVD 리액터가 기존 TFT 라인과 원활하게 통합될 수 있기 때문입니다. Kateeva사가 선도하는 잉크젯 봉지 인쇄는 유기 재료 폐기물을 줄이고, 스마트 워치 다이얼용 패턴화된 배리어 층을 구현했습니다. VTE는 디바이스의 수율이 처리량보다 우선시되는 소면적 마이크로 디스플레이 분야에서 여전히 중요한 위치를 차지하고 있습니다. 파일럿 테스트에서 공간 ALD가 15세대 기판 처리에 성공함에 따라, PECVD와 ALD 간경쟁 구도는 더욱 격화될 것으로 예상되며, 두 기법을 활용하는 하이브리드 생산 라인의 보급이 촉진될 것입니다.
파릴렌 C와 ALD Al2O3를 조합한 하이브리드 적층 구조는 응력 완화 및 방습성의 균형이 입증됨에 따라 2025년에는 매출의 46.85%를 차지했습니다. 이러한 조합은 1만 회를 넘는 굽힘 사이클을 유지하면서 105 g/m2/일 미만의 WVTR을 달성하고 있으며, 이는 프리미엄 스마트폰에 요구되는 사양입니다. 한편, 단층 배리어는 현재 28.35%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이는 실비온이 배합된 하이브리드 필름이 성막 공정의 길이를 절반으로 단축하면서도 동등한 보호 성능을 제공하여, 롤형 패널의 타크트 타임을 단축하고 있기 때문입니다.
무기 다층 구조는 타의 추종을 불허하는 내산소성을 발휘하지만, 인장 응력 하에서 균열이 발생할 위험이 있어 접이식 기기에의 채택이 제한되고 있습니다. 유기 다층 구조는 굽힘 용이성이 뛰어나지만, 단독으로는 수명 목표를 달성하기 어렵습니다. 그 결과, 양산 라인에서는 제품 등급별로 층 구조가 조정되고 있습니다. 스마트폰에는 하이브리드 2층 구조가 채택되고, 자동차용 계기판에는 3층의 무기 캡 층이 필요한 반면, 전자 섬유 분야에서는 첨단 유기 화학 기술에 대한 의존도가 높아지고 있습니다. 부품 공급업체들은 인접한 층 간의 굴절률, 탄성률, 접착성을 조화시킨 모듈식 소재 키트를 제공함으로써 이에 대응하고 있으며, 90% 이상의 수율을 실현하는 생산 라인의 신뢰성을 확보하고 있습니다.
지역별 분석
아시아태평양은 한국과 중국의 팹 확장 및 통합된 공급 생태계에 힘입어 2025년에도 매출 점유율 69.10%를 유지했습니다. 봉지 설비 투자 비용을 충당하는 정부의 인센티브로 인해 ALD 클러스터 도입이 가속화된 반면, 한국 기업들은 이익률을 지키기 위해 고부가가치 제품 및 탠덤 스택으로 사업을 전환했습니다. 지역 내 장비 및 화학 약품 공급업체들은 팹 근처에 거점을 마련하여 인증 주기를 단축하는 동시에, 박막 봉지 시장 전체에서 우위를 강화했습니다.
유럽에서는 자동차 및 BIPV(건축용 태양광 발전) 수요를 배경으로 견조한 성장을 보였습니다. EU의 엄격한 자동차 안전 지침에 따라 곡면 OLED 콕핏의 채택이 가속화되었으며, 탄소 중립 건축 규제가 태양광 파사드에 ALD 배리어 층의 채택을 촉진했습니다. 연구 컨소시엄은 저온 ALD 전구체의 개발을 추진하여, 그 성능을 순환형 경제의 목표와 부합시켰습니다.
중동 및 아프리카은 UAE나 사우디아라비아 등 국가들이 경제 다각화를 도모하기 위해 전자 산업 클러스터에 자금을 지원함에 따라, 소규모 기반임에도 불구하고 26.35%라는 가장 높은 연평균 성장률(CAGR)이 예상됩니다. 가혹한 사막 기후로 인해 디스플레이 및 태양전지 제품에는 견고한 봉지 기술이 필수적이며, 이에 따라 ALD 기반 무기층에 대한 프리미엄 수요가 발생했습니다. 아시아의 OEM 제조업체와의 기술 이전 파트너십을 통해 현지 생산 능력이 구축되었으며, 세계 브랜드의 단일 지역 의존도가 낮아졌습니다.
북미는 패널 생산 규모가 제한적임에도 불구하고, 재료 과학 분야의 리더십과 장비 수출을 통해 영향력을 유지했습니다. 자동차 업계의 규제와 양자점·마이크로 LED 연구 개발이 특수 배리어 기술에 대한 수요를 뒷받침한 반면, 롤-투-롤 ALD 스타트업 기업들은 벤처 자금을 활용하여 웨어러블 제품 라인의 상용화를 추진했습니다. 지역 내 팹(fab)들은 대학과 협력하여 머신러닝을 활용한 공정 제어에 착수함으로써, 박막의 균일성과 처리량을 향상시켰습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, thin film encapsulation market size in 2026 is estimated at USD 420.77 million, growing from 2025 value of USD 350 million with 2031 projections showing USD 1.06 billion, growing at 20.22% CAGR over 2026-2031.
This report is Segmented by Technology (Plasma-Enhanced Chemical Vapor Deposition, Atomic Layer Deposition, and More), by Layer Structure (Inorganic Multilayer Barriers, Organic Multilayer Barriers, and More), by Application (Flexible OLED Displays, and More), by Deposition Equipment Type (Cluster PECVD Systems, and More), by End-Use Industry (Consumer Electronics, Renewable Energy, and More), and by Geography.
Global Thin Film Encapsulation Market Trends and Insights
AMOLED capacity expansions in South Korea and China are fueling ALD-TFE tool orders
Samsung Display allocated USD 3 billion for an 8.6-generation IT OLED line targeting 2026 production, while BOE committed USD 8.7 billion for a comparable plant. These projects multiplied purchase orders for ALD encapsulation tools because the technology offers uniform, pinhole-free barriers at low temperatures, a necessity for next-generation IT and automotive panels. Heightened competition has revived Korean shipment leadership but simultaneously broadened ALD demand across Asia-Pacific foundries.
Automotive curved-display mandates in the EU and North America
Regulatory guidance favoring seamless instrument clusters has sparked accelerated design-ins of curved OLED dashboards. These modules need encapsulation stacks that withstand vibration, UV exposure, and -40 °C cycling. Samsung's adoption of tandem OLED with advanced moisture barriers exemplified the shift, positioning the firm to capture revenue as total automotive display spend is forecast to overtake monitor panel sales by 2026.
High CapEx of Gen-6 ALD cluster lines
Next-generation ALD stacks demand more than USD 100 million per line, sidelining mid-tier producers and slowing technology diffusion. Many Asian fabs still amortize older cluster tools, complicating upgrade economics even where yield benefits are clear. This cost barrier delays uniform adoption of best-in-class encapsulation across the thin film encapsulation market.
Other drivers and restraints analyzed in the detailed report include:
- Roll-to-roll ALD unlocking certified medical wearables
- EU carbon-neutral BIPV push boosting inorganic barriers
- Reliability failures under -40 °C automotive cycling
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ALD recorded a 25.85% CAGR outlook while PECVD held 38.90% revenue in 2025, illustrating a transition phase within the thin film encapsulation market. ALD films reached water-vapor rates at 10-6 g/m2/day that extend OLED life spans and support foldable substrates. Roll-to-roll ALD upgraded throughput to web speeds suitable for wearable production, while spatial ALD is overcoming substrate-size limits. PECVD remains preferred for rigid panels needing high volume. VTE and OVPD continue in niche emissive stacks where material compatibility overrides barrier extremity. Low-temperature ALD chemistries awarded by SID in 2023 unlocked polyimide substrates for mass foldables, deepening the technology mix. Consequently, ALD tool providers enjoy record order backlogs, lifting regional supplier ecosystems across South Korea, China, and the United States.
The thin film encapsulation market continues to rely on PECVD for cost-sensitive SKUs because the reactors integrate seamlessly with legacy TFT lines. Inkjet encapsulation printing, spearheaded by Kateeva, decreased organic material waste and enabled patterned barriers for smartwatch dials. VTE retains relevance for small-area microdisplays where device yield trumps throughput. With spatial ALD crossing 15 gen substrates in pilot tests, the competitive landscape between PECVD and ALD is expected to tighten, driving hybrid production floors that leverage both methods.
Hybrid stacks combining parylene C with ALD Al2O3 secured 46.85% sales in 2025, thanks to a proven balance of stress relief and moisture blocking. These dyads achieved sub-105 g/m2/day WVTR while sustaining flex cycles exceeding 10,000 bends, a specification demanded by premium smartphones. Single-layer barriers, however, now post the fastest 28.35% CAGR because silbione-blended hybrimer films offer comparable protection at half the deposition sequence length, cutting takt time for rollable panels.
Inorganic multi-layers deliver unmatched oxygen resistance but risk crack formation under tensile stress, limiting adoption in foldables. Organic multi-layers excel in bendability yet rarely reach lifetime targets alone. Commercial lines consequently calibrate layer architecture by product class: smartphones accept hybrid dyads, automotive clusters need triple inorganic caps, while e-textiles increasingly lean on advanced organic chemistries. Component suppliers respond with modular material kits that harmonize refractive index, modulus, and stickiness across adjoining layers, ensuring line reliability beyond 90% yield.
Complete Report Scope:
- By Technology
- Plasma-Enhanced Chemical Vapor Deposition (PECVD)
- Atomic Layer Deposition (ALD)
- Inkjet Printing
- Vacuum Thermal Evaporation (VTE)
- Organic Vapor Phase Deposition (OVPD)
- Roll-to-Roll ALD
- Other Emerging Techniques (Parylene, Sol-Gel)
- By Layer Structure
- Inorganic Multilayer Barriers
- Organic Multilayer Barriers
- Hybrid (Organic+Inorganic) Barriers
- Single-Layer Encapsulation
- By Application
- Flexible OLED Displays
- Thin-Film Photovoltaics
- Flexible OLED Lighting
- Wearable and Medical Electronics
- Automotive Displays and Lighting
- Quantum-Dot and MicroLED Devices
- Printed Sensors and IoT Devices
- By Deposition Equipment Type
- Cluster PECVD Systems
- Inkjet Encapsulation Printers
- ALD Reactors
- Roll-to-Roll Vacuum Systems
- Laser-Assisted Deposition Tools
- By End-Use Industry
- Consumer Electronics
- Renewable Energy
- Automotive and Transportation
- Healthcare and Wearables
- Industrial and Aerospace
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Rest of Europe
- Asia-Pacific
- China
- South Korea
- Japan
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific retained 69.10% revenue share in 2025, driven by South Korea's and China's fab expansions and integrated supply ecosystems. Government incentives covering encapsulation capital costs accelerated ALD cluster installations, while Korean players pivoted toward high-value products and tandem stacks to defend margins. Regional tooling and chemical suppliers co-located near fabs, shortening qualification cycles and reinforcing dominance across the thin film encapsulation market.
Europe posted healthy gains built on automotive and BIPV demand. Strict EU vehicle safety directives accelerated curved OLED cockpit adoption, and carbon-neutral building rules spurred ALD barrier uptake in solar facades. Research consortia advanced low-temperature ALD precursors, aligning performance with circular-economy objectives.
The Middle East and Africa exhibited the highest 26.35% CAGR outlook from a small base, as nations like the UAE and Saudi Arabia funded electronics clusters to diversify their economies. Harsh desert climates necessitated robust encapsulation for display and solar products, creating premium demand for ALD-based inorganic layers. Technology transfer partnerships with Asian OEMs seeded local capacity, reducing single-region dependency for global brands.
North America maintained influence through materials science leadership and equipment exports despite limited panel production. Automotive mandates and quantum-dot microLED research and development anchored demand for specialized barrier know-how, while roll-to-roll ALD startups leveraged venture funding to commercialize wearable lines. Regional fabs collaborated with universities on machine-learning process control, enhancing film uniformity and throughput.
- Samsung SDI Co., Ltd.
- LG Chem Ltd.
- Universal Display Corporation
- Applied Materials Inc.
- Veeco Instruments Inc.
- 3M Inc.
- Toray Industries Inc.
- Kateeva
- BASF (Rolic) AG
- Meyer Burger Technology AG
- Encapsulix SAS
- Forge Nano Inc.
- Aixtron SE
- Angstrom Engineering Inc.
- Forge Nano Inc.
- Beneq Oy
- Picosun Oy
- Canon Tokki Corporation
- AP Systems
- EMD Electronics (Merck KGaA)
- Idemitsu Kosan Co.
- Encapsulix SAS
- Wonik IPS
- Vitriflex Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AMOLED Capacity Expansions in South Korea and China Fueling ALD-TFE Tool Orders
- 4.2.2 Automotive Curved-Display Mandates in EU and NA
- 4.2.3 Roll-to-Roll ALD Unlocking Certified Medical Wearables
- 4.2.4 EU Carbon-Neutral BIPV Push Boosting Inorganic Barriers
- 4.2.5 SID Award-Winning Low-Temp ALD Materials Enabling Foldables
- 4.2.6 China "New Display" Subsidies Covering Encapsulation Capex
- 4.3 Market Restraints
- 4.3.1 High Capex of Gen-6 ALD Cluster Lines
- 4.3.2 Reliability Failures under -40 °C Automotive Cycling
- 4.3.3 Competition from Ultra-Thin Flexible Glass
- 4.3.4 Precursor Supply Bottlenecks (e.g., DEZ)
- 4.4 Value Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Key Performance Indicators Benchmarked
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Impact of Macroeconomic factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Plasma-Enhanced Chemical Vapor Deposition (PECVD)
- 5.1.2 Atomic Layer Deposition (ALD)
- 5.1.3 Inkjet Printing
- 5.1.4 Vacuum Thermal Evaporation (VTE)
- 5.1.5 Organic Vapor Phase Deposition (OVPD)
- 5.1.6 Roll-to-Roll ALD
- 5.1.7 Other Emerging Techniques (Parylene, Sol-Gel)
- 5.2 By Layer Structure
- 5.2.1 Inorganic Multilayer Barriers
- 5.2.2 Organic Multilayer Barriers
- 5.2.3 Hybrid (Organic+Inorganic) Barriers
- 5.2.4 Single-Layer Encapsulation
- 5.3 By Application
- 5.3.1 Flexible OLED Displays
- 5.3.2 Thin-Film Photovoltaics
- 5.3.3 Flexible OLED Lighting
- 5.3.4 Wearable and Medical Electronics
- 5.3.5 Automotive Displays and Lighting
- 5.3.6 Quantum-Dot and MicroLED Devices
- 5.3.7 Printed Sensors and IoT Devices
- 5.4 By Deposition Equipment Type
- 5.4.1 Cluster PECVD Systems
- 5.4.2 Inkjet Encapsulation Printers
- 5.4.3 ALD Reactors
- 5.4.4 Roll-to-Roll Vacuum Systems
- 5.4.5 Laser-Assisted Deposition Tools
- 5.5 By End-Use Industry
- 5.5.1 Consumer Electronics
- 5.5.2 Renewable Energy
- 5.5.3 Automotive and Transportation
- 5.5.4 Healthcare and Wearables
- 5.5.5 Industrial and Aerospace
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 France
- 5.6.3.3 United Kingdom
- 5.6.3.4 Italy
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 South Korea
- 5.6.4.3 Japan
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Samsung SDI Co., Ltd.
- 6.4.2 LG Chem Ltd.
- 6.4.3 Universal Display Corporation
- 6.4.4 Applied Materials Inc.
- 6.4.5 Veeco Instruments Inc.
- 6.4.6 3M Inc.
- 6.4.7 Toray Industries Inc.
- 6.4.8 Kateeva
- 6.4.9 BASF (Rolic) AG
- 6.4.10 Meyer Burger Technology AG
- 6.4.11 Encapsulix SAS
- 6.4.12 Forge Nano Inc.
- 6.4.13 Aixtron SE
- 6.4.14 Angstrom Engineering Inc.
- 6.4.15 Forge Nano Inc.
- 6.4.16 Beneq Oy
- 6.4.17 Picosun Oy
- 6.4.18 Canon Tokki Corporation
- 6.4.19 AP Systems
- 6.4.20 EMD Electronics (Merck KGaA)
- 6.4.21 Idemitsu Kosan Co.
- 6.4.22 Encapsulix SAS
- 6.4.23 Wonik IPS
- 6.4.24 Vitriflex Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


