|
시장보고서
상품코드
2123406
압력 라벨 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pressure Labels - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
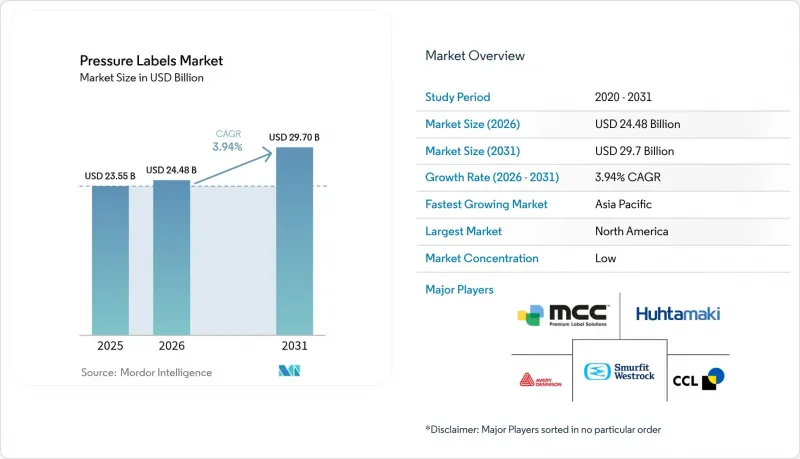
에 의하면, 압력 라벨 시장 규모는 2025년 235억 5,000만 달러에서 2026년에는 244억 8,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 3.94%로 성장을 지속하여, 2031년에는 297억 달러에 이를 것으로 예측됩니다.
본 보고서는 인쇄 공정(그라비아, 플렉소, 스크린, 활판, 잉크젯 등), 최종 사용자(식품, 음료, 헬스케어, 화장품, 가정용품, 산업용 등), 접착제 유형(수성 아크릴계, 핫멜트 고무계, 용제계, UV 경화형) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 압력 라벨 시장 동향 및 인사이트
전자상거래 및 적시(JIT) 물류의 성장
온라인 소매에서 처리되는 소포 물량은 계속 증가하고 있으며, 현재 창고에서는 매일 수백만 장의 감압 접착제로 인쇄된 배송 라벨이 인쇄되고 있습니다. 물류 사업자들은 컨베이어에 의한 마모를 견디면서도, 골판지 재사용 시 깨끗하게 떼어낼 수 있는 접착제를 지정하고 있습니다. UPM Adhesive Materials사는 여러 배송 주기에 대응 가능한, 박리 가능한 물류용 페이스 스톡을 출시했습니다. 또한, 브랜드 소유주들이 재고 완충량을 줄이고 있기 때문에 컨버터는 몇 주가 아닌 몇 시간 이내에 맞춤형 라벨을 공급해야 합니다. 이러한 긴급성으로 인해 가동 중단 시간을 최소화하며 작업 전환이 가능한 디지털 인쇄기가 유리해졌으며, 이는 압력 라벨 시장의 성장을 뒷받침하고 있습니다.
소량·가변 데이터 디지털 인쇄의 부상
디지털 기술을 통해 컨버터는 그래픽, 언어, 일련번호를 현장에서 개인화할 수 있게 되었습니다. 그라비아 인쇄기는 고급 화장품 분야에서 가장 빠르게 성장하고 있지만, 단거리 인쇄의 경우 비용 증가로 이어지는 실린더가 여전히 필요합니다. 대조적으로, 토너 및 잉크젯 플랫폼에서는 판을 필요로 하지 않고 일련번호가 부여된 바코드나 지역별 디자인을 인쇄할 수 있습니다. AGH Labels사는 고해상도의 싱글 패스 금속화 효과가 아날로그 품질에 필적할 수준에 이르렀을 뿐만 아니라, 준비 공정에서 발생하는 폐기물을 줄일 수 있다는 점을 강조했습니다. 이러한 기능들은 그라비아 인쇄의 예상 연평균 성장률(CAGR) 6.13%를 뒷받침하며, 전체 압력 라벨 시장의 회복력을 강화하고 있습니다.
원자재(아크릴계 PSA) 가격 변동
석유화학제품의 현물 가격 급등이 컨버터의 이익률을 압박하고 있습니다. 미국화학공업협회(ACC)는 전 세계 화학제품 생산량이 소폭 증가에 그쳤다고 보고했으며, 이는 모노머 공급이 부족함을 시사합니다. 생산자들은 SASOLWAX와 같은 바이오 접착제로 전환하여 위험을 헤지하고 있으며, 이를 통해 ‘크래들-투-게이트’ 환경 부하를 35% 저감하고 보다 안정적인 가격 책정이 가능해집니다.
부문 분석
플렉소 인쇄는 2025년 매출의 38.12%를 차지하며, 식품 라벨 대량 생산에서 높은 비용 효율성을 입증하고 있습니다. 한편, 그라비아 인쇄는 화장품 및 제약 업계의 구매자들이 사진 수준의 품질과 메탈릭 잉크를 요구함에 따라 연평균 성장률(CAGR) 5.86%를 나타낼 것으로 예측됩니다. 그라비아 방식의 압력 라벨 시장 규모는 2031년까지 75억 3,000만 달러에 달할 것으로 예측되며, 프리미엄 틈새 시장의 확대를 보여줍니다. 스크린 인쇄와 활판 인쇄는 촉감이 좋은 고급 포장 분야에서 꾸준한 지지를 유지하고 있는 반면, 잉크젯 인쇄는 일련번호 부여 분야에서의 채택이 확대되고 있습니다.
플렉소 가공업체들은 설비 폐기물을 최적화하고 전력 소비를 줄이는 UV-LED 경화 기술을 도입함으로써 원자재 가격 변동의 영향을 완화하고 있습니다. 그라비어 인쇄 시설에서는 전기 기계식 조각을 채택하여 실린더 리드타임을 단축하고, 신제품 출시를 가속화하고 있습니다. 프레스처 라벨 시장은 이러한 균형 잡힌 기술 조합의 혜택을 받고 있으며, 브랜드 소유자에게는 용도 수준에 따른 가격 및 서비스 선택지가 제공되고 있습니다. 또한, 규제 감사에서도 ISO 9001:2015 인증 및 G7 컬러 타겟을 준수하는 공정이 중시되고 있어, 신흥국에서도 공정 업그레이드가 진행되고 있습니다.
지역별 분석
북미는 엄격한 추적성 관련 법규와 고도의 소매 자동화를 배경으로 2025년 매출의 39.05%를 차지했습니다. ‘의약품 공급망 보안법’ 및 ‘식품 안전 현대화법’에 따라 제약 업계와 잎채소 업계에서 일련번호 라벨에 대한 연간 수요가 유지되고 있습니다. CCL 인더스트리즈는 2025년 1분기에 8.6%의 매출 성장을 기록했으며, 이는 투입 자재 가격의 변동에도 불구하고 컨버터의 이익률이 견조하게 유지되고 있음을 반영합니다. UPM의 밀스 리버 공장에 대한 투자를 통해 고급 와인, 증류주, 우편용 라미네이트 제품이 추가되어 현지 공급이 확보되었습니다.
아시아태평양은 가처분 소득 증가가 포장 화장품 및 즉석 음용 차 수요를 견인함에 따라, 2031년까지 연평균 성장률(CAGR)이 5.33%로 가장 빠른 성장을 기록할 것으로 예측됩니다. UPM의 조호르바루 코팅 라인은 해당 지역의 전자기기 수출 수요에 부응하기 위해 필름 라벨 및 전자기기용 라벨을 공급할 예정입니다. 필리핀과 베트남에서 확대 생산자 책임(EPR) 법이 도입됨에 따라 워시오프 라벨 및 라이너리스 라벨에 대한 수요가 촉진되고 있습니다. 국내 각 컨버터 기업들은 아세안 지역의 모바일 사용자층을 대상으로 다국어 지원 제품을 제공하기 위해 디지털 인쇄기 투자를 추진하고 있습니다. 세계 브랜드들이 자카르타, 호치민시, 방갈로르 인근으로 공장을 이전하는 움직임에 따라, 압력 라벨 시장에서는 공급망의 변혁이 진행되고 있습니다.
유럽에서는 야심 찬 재활용 목표와 선진적인 회수 시스템에 힘입어 완만한 성장을 유지하고 있습니다. ‘포장 및 포장 폐기물 규정’에 따라 각 컨버터 업체는 가정용 분리수거기와 호환성을 입증해야 합니다. APR 인증을 받은 라벨 및 용기 시스템은 환경 조정 요금의 대상이 되며, 이를 통해 확대된 생산자 책임의 비용이 절감되므로 도입이 촉진되고 있습니다. 2019년에 전면 도입된 의약품 일련번호 부여 제도는 코드 라벨의 지속적인 구매를 뒷받침하고 있습니다. 브렉시트로 인한 규제 차이는 복잡성을 가중시키고 있지만, 기존 주요 기업들은 신속하게 적응하며 고객의 충성도를 유지하고 있습니다. 이러한 요인들이 결합되어 유럽의 압력 라벨 시장은 안정적인 상승 궤도를 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the pressure labels market size is expected to grow from USD 23.55 billion in 2025 to USD 24.48 billion in 2026 and is forecast to reach USD 29.7 billion by 2031 at 3.94% CAGR over 2026-2031.
This report is Segmented by Print Process (Gravure, Flexography, Screen, Letterpress, Inkjet, and More), End-User (Food, Beverage, Healthcare, Cosmetics, Household, Industrial, and More), Adhesive Type (Water-Based Acrylic, Hot-Melt Rubber-Based, Solvent-Based, and UV-Curable), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Pressure Labels Market Trends and Insights
Growth of e-commerce and just-in-time logistics
Parcel volumes from online retail continue to rise, and warehouses now print millions of pressure-sensitive shipping labels daily. Logistics providers specify adhesives that survive conveyor abrasion yet peel away cleanly for carton reuse. UPM Adhesive Materials released removable logistics facestocks that support multiple delivery cycles. Brand owners also compress inventory buffers, so converters must supply customized labels within hours rather than weeks. This urgency favors digital presses that swap jobs with minimal downtime, reinforcing the growth of the pressure labels market.
Rise of short-run, variable-data digital printing
Digital technology lets converters personalize graphics, languages, and serial numbers on the fly. Gravure presses, while growing fastest for premium cosmetics, still require cylinders that add cost at short lengths. By contrast, toner and inkjet platforms can print serialized barcodes or regional designs without the need for plates. AGH Labels highlighted that high-definition single-pass metalized effects now match analog quality while cutting makeready waste. These capabilities underpin the projected 6.13% CAGR for gravure and strengthen overall pressure labels market resilience.
Volatility in raw-material (acrylic PSA) prices
Spot petrochemical hikes squeeze converter margins. The American Chemistry Council reported fractional global chemical output growth, signaling tight monomer supply. Producers hedge by shifting to bio-based tackifiers, such as SASOLWAX, which offers a 35% lower cradle-to-gate footprint and more stable pricing.
Other drivers and restraints analyzed in the detailed report include:
- Brand-owner demand for sustainable facestocks and liners
- Strict traceability mandates in food and pharma
- Stringent recyclability regulations limiting mixed-material labels
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Flexography contributed 38.12% of the 2025 revenue, underscoring its cost-effectiveness for long food labeling runs. Gravure printing, however, is projected to deliver a 5.86% CAGR as beauty and pharmaceutical buyers request photographic quality and metallic inks. The pressure labels market size for gravure formats is forecast to reach USD 7.53 billion by 2031, indicating a widening premium niche. Screen and letterpress retain loyal followings in tactile luxury packaging, while inkjet widens adoption in serialization.
Flexo converters mitigate raw-material fluctuations by optimizing setup waste and implementing UV-LED curing, which reduces power consumption. Gravure facilities utilize electromechanical engraving to reduce cylinder lead times, enabling faster introductions of new products. The pressure labels market benefits from this balanced technology mix, giving brand owners price-service options across application tiers. Regulatory audits also favor processes certified to ISO 9001:2015 and G7 color targets, prompting process upgrades even in emerging economies.
Complete Report Scope:
- By Print Process
- Gravure
- Flexography
- Screen
- Letterpress
- Inkjet
- Other Print Processes
- By End-User
- Food
- Beverage
- Healthcare
- Cosmetics
- Household
- Industrial
- Other End-user Industries
- By Adhesive Type
- Water-based Acrylic
- Hot-melt Rubber-based
- Solvent-based
- UV-curable
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 39.05% of 2025 revenue, anchored by strict traceability legislation and sophisticated retail automation. The Drug Supply Chain Security Act and the Food Safety Modernization Act sustain annual demand for serialized labels across the pharmaceutical and leafy green industries. CCL Industries logged 8.6% sales growth in Q1 2025, reflecting steady converter margins despite input volatility. Investments at UPM's Mills River site add premium wine, spirits, and postal laminates, ensuring local supply.
The Asia-Pacific region is projected to record the fastest growth, with a 5.33% CAGR through 2031, as rising disposable incomes drive demand for packaged cosmetics and ready-to-drink teas. UPM's Johor Bahru coating line will supply filmic and electronics labels to meet regional electronics exports. Extended Producer Responsibility laws in the Philippines and Vietnam stimulate demand for wash-off or linerless labels. Domestic converters invest in digital presses to offer multilingual versions for ASEAN's mobile consumer base. The pressure labels market is seeing supply-chain shifts as global brands relocate plants closer to Jakarta, Ho Chi Minh City, and Bengaluru.
Europe maintains moderate growth underpinned by ambitious recycling targets and advanced collection systems. The Packaging and Packaging Waste Regulation pressures converters to prove compatibility with household sorters. APR-certified label-container systems earn eco-modulated fees that lower extended producer costs, encouraging adopters. Pharmaceutical serialization, complete since 2019, sustains recurring code-label purchases. Brexit regulatory divergence adds complexity, but established players adapt swiftly, preserving customer loyalty. Together these factors keep the pressure labels market in Europe on a stable upward path.
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Fuji Seal International Inc.
- Smurfit WestRock plc
- Huhtamaki Oyj
- Taghleef Industries LLC
- Coveris Group
- UPM Raflatac
- Taylor Corporation
- Constantia Flexibles Group GmbH
- Herma GmbH
- Skanem AS
- Resource Label Group, LLC
- Beontag Group
- Schreiner Group GmbH & Co. KG
- SATO Holdings Corporation
- Inland Packaging LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of e-commerce and just-in-time logistics
- 4.2.2 Rise of short-run, variable-data digital printing
- 4.2.3 Brand-owner demand for sustainable facestocks and liners
- 4.2.4 Strict traceability mandates in food and pharma
- 4.2.5 Adoption of liner-less pressure labels in retail automation
- 4.2.6 Smart labels with printed electronics for cold-chain monitoring
- 4.3 Market Restraints
- 4.3.1 Volatility in raw-material (acrylic PSA) prices
- 4.3.2 Stringent recyclability regulations limiting mixed-material labels
- 4.3.3 Limited durability in extreme temperatures and UV exposure
- 4.3.4 Capital-intensive transition to digital presses for converters
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Print Process
- 5.1.1 Gravure
- 5.1.2 Flexography
- 5.1.3 Screen
- 5.1.4 Letterpress
- 5.1.5 Inkjet
- 5.1.6 Other Print Processes
- 5.2 By End-User
- 5.2.1 Food
- 5.2.2 Beverage
- 5.2.3 Healthcare
- 5.2.4 Cosmetics
- 5.2.5 Household
- 5.2.6 Industrial
- 5.2.7 Other End-user Industries
- 5.3 By Adhesive Type
- 5.3.1 Water-based Acrylic
- 5.3.2 Hot-melt Rubber-based
- 5.3.3 Solvent-based
- 5.3.4 UV-curable
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 CCL Industries Inc.
- 6.4.2 Avery Dennison Corporation
- 6.4.3 Multi-Color Corporation
- 6.4.4 Fuji Seal International Inc.
- 6.4.5 Smurfit WestRock plc
- 6.4.6 Huhtamaki Oyj
- 6.4.7 Taghleef Industries LLC
- 6.4.8 Coveris Group
- 6.4.9 UPM Raflatac
- 6.4.10 Taylor Corporation
- 6.4.11 Constantia Flexibles Group GmbH
- 6.4.12 Herma GmbH
- 6.4.13 Skanem AS
- 6.4.14 Resource Label Group, LLC
- 6.4.15 Beontag Group
- 6.4.16 Schreiner Group GmbH & Co. KG
- 6.4.17 SATO Holdings Corporation
- 6.4.18 Inland Packaging LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment