

|
시장보고서
상품코드
2123407
스마트 모터 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Smart Motors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
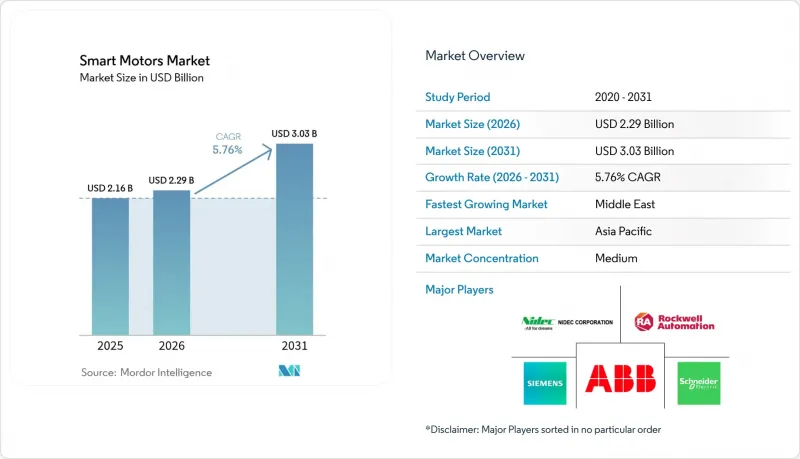
에 의하면, 스마트 모터 시장 규모는 2025년에 21억 6,000만 달러로 평가되었고 2026년 22억 9,000만 달러에서 2031년까지 30억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.76%를 나타낼 전망입니다.
본 보고서는 구성 요소(가변 속도 드라이브, 모터, 일체형 모터·드라이브), 정격 출력(1kW 미만, 1-10kW, 10kW 초과),통신 프로토콜(이더넷/IP 등), 용도(산업용, 상업용, 자동차용, 항공우주 및 방위용), 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 스마트 모터 시장 동향 및 인사이트
SiC/GaN 파워 디바이스를 활용한 통합형 모터·드라이브 패키지의 비용 절감
광대역 갭 실리콘 카바이드(SiC) 및 갈륨 나이탈리아드(GaN) 트랜지스터 덕분에 재료 비용이 약 5분의 1로 절감되어, 공급업체는 추가 비용 없이 모터, 인버터, 피드백 센서를 하나의 하우징에 통합할 수 있게 되었습니다. 100 kHz를 초과하는 스위칭 주파수로 인해 수동 부품의 크기가 40% 축소되어 통합 유닛의 무게가 가벼워졌으며, 협동 로봇이나 전기자동차의 냉각 루프에 쉽게 장착할 수 있게 되었습니다. 전도 손실이 30-35% 감소하여, 충전 간 가동 시간을 연장해야 하는 배터리 구동 이동 로봇에게 이는 매우 중요한 이점이 됩니다. 2025년에는 200mm SiC 웨이퍼의 세계 생산량이 증가하고 모듈 가격이 85달러에서 62달러로 하락함에 따라, 중급 산업용 드라이브에도 통합 패키지의 구현이 가능해졌습니다. 도입이 가장 빠르게 진행되고 있는 곳은 북미와 유럽이지만, 중국의 팹은 수율 및 신뢰성 벤치마크 측면에서 여전히 12-18개월 뒤처져 있습니다.
유럽 및 중국의 산업용 에너지 효율 기준 의무화
유럽연합(EU)은 2025년 7월, IE4 요건을 0.75kW 미만 모터로도 확대했으며, 중국은 2024년 1월, 신규 프로젝트에서 IE2 모터 사용을 금지했습니다. 이에 따라 IE3 이상의 효율을 기준으로 하는 전 세계 규제가 통일되어 가고 있습니다. 드라이브가 장착된 75kW IE4 모터는 전력 소비를 8-12% 절감할 수 있으며, 산업용 전기 요금 기준으로는 1,800달러의 추가 비용을 18개월 이내에 회수할 수 있습니다. 따라서 금속, 시멘트, 펄프 생산업체들은 모터가 고장 나기 전에 노후화된 장비를 폐기하고, 검증된 효율 곡선이 첨부된 턴키 방식의 통합 유닛을 선호하여 도입하고 있습니다. 태국은 2027년을 목표로 IE3 의무화안을 수립했고, 베트남은 IE4 목표에 대해 협의 중이며, 이는 아세안 전역으로 확산될 것으로 보입니다. 거시경제적인 역풍에도 불구하고, 교체 주기의 가속화가 수요 증가를 뒷받침하고 있습니다.
네트워크 연결형 모터 시스템의 사이버 보안 취약점
2025년에 발각된 14건의 펌웨어 결함으로 인해 인증 없이 Modbus-TCP 쓰기가 가능해져, 스마트 드라이브의 비상 정지 기능이 해제될 우려가 있었습니다. 2025년 출하된 제품 중 IEC 62443의 SL2를 충족한 제품은 불과 38%에 불과했으며, 암호화와 역할 기반 접근 제어를 의무화하는 SL3에 도달한 제품은 12% 미만이었습니다. 2024년 유럽의 처리 시설에서 패치가 적용되지 않은 PROFINET 드라이브를 통해 발생한 보안 침해 사고로 인해, 상수도 유틸리티자와 정유시설가 가장 큰 위험에 직면해 있습니다. 보안 강화 조치, 네트워크 세분화, 서명된 펌웨어, 침입 감지 시스템을 도입하면 모터 1대당 300-800달러의 추가 비용이 발생하며, OT와 보안 두 분야 모두에 능통한 엔지니어가 필요하지만, 사업자의 64%는 이러한 인재를 확보하지 못하고 있습니다.
부문 분석
모터와 드라이브가 일체화된 패키지 제품은 스마트 모터 시장 전체보다 빠른 속도로 성장하고 있으며, 연평균 성장률(CAGR)은 6.31%에 달할 전망입니다. 이는 설치 시간을 30-40% 단축하고, 전자기 간섭으로 인한 문제 해결 부담을 줄이는 점을 중시하는 사용자를 확보하고 있기 때문입니다. 2025년에도 독립형 가변속 드라이브는 여전히 매출의 44.56%라는 최대 점유율을 차지하고 있습니다. 이는 개조 프로젝트에서 모터 자체보다는 컨트롤러만 교체하는 경우가 많기 때문입니다. 그러나 일체형 설계는 단일 하우징의 IP69K 대응 유닛을 통해 스테인리스 인클로저 비용을 절감할 수 있어, 이동형 로봇이나 세척이 가능한 식품 제조 라인에 점차 확산되고 있습니다.
이러한 변화는 분산 제어의 동향과 일치합니다. 40축 서보가 필요한 포장기의 경우, 각 모터 샤프트에 일체형 드라이브를 장착함으로써 캐비닛 한 줄 분량의 공간을 절약할 수 있습니다. 아시아태평양에서는 자본 예산상의 이유로 단계적인 업그레이드가 선호되기 때문에 독립형 드라이브에 대한 수요는 여전히 높지만, 중국의 보조금 프로그램에 따라 중공업 분야의 국영 기업들은 500kW 이상의 통합형 플랫폼으로의 전환을 추진하고 있습니다. 모듈식 아키텍처는 계속해서 채택되고 있으며, 고장 시 운영자가 모터 또는 드라이브 중 하나를 개별적으로 교체할 수 있습니다.
1kW 미만의 모터는 EC 창고에서 1대당 0.2-0.5kW의 휠 드라이브 4-6개를 탑재한 자율 이동 로봇이 도입됨에 따라 연간 6.34%의 성장세를 보이고 있습니다. 대조적으로, 1-10kW급은 2025년 매출의 38.72%를 차지하며, 산업용 펌프 및 컨베이어의 중추를 이루고 있습니다. 2025년에는 0.5kW 통합형 패키지의 단가가 180-240달러까지 하락하여, 과거 정속 유도 모터를 사용하던 용도에서도 스마트한 제어가 가능해졌습니다.
10kW를 초과하는 등급의 경우, 석유 및 가스·금속 플랜트에서는 에너지 절약보다 견고성이 우선시되기 때문에 모터의 전면적인 교체가 아닌 예측 유지보수로의 업그레이드가 선택되는 경향이 있어, 성장률은 시장 평균보다 낮습니다. 빌딩 자동화는 저출력 분야에서 수요를 끌어올리고 있습니다. 중규모 사무실에는 100대의 가변 풍량(VAV) 박스가 설치되어 있으며, 각 박스에는 0.1-0.3kW의 스마트 액추에이터가 탑재되어 있습니다. 그 결과, 예측 기간 동안 1kW 미만 솔루션의 스마트 모터 시장 규모는 중출력 유닛과의 격차를 좁힐 전망입니다.
지역별 분석
아시아태평양은 2025년 스마트 모터 시장에서 39.74%라는 최대 점유율을 차지했습니다. 이는 중국이 같은 해 180만 대의 모터를 업그레이드하기 위해 투입한 3,000억 위안(420억 달러) 규모의 에너지 효율화 기금에 힘입은 결과입니다. 인도의 백색가전 및 에어컨용 ‘생산 연계 인센티브(PLI)’ 프로그램 덕분에 2025년에는 연간 생산 능력이 120만 대 증가했습니다. 한편, 일본과 한국에서는 로봇 공학 및 반도체 제조 공장을 위한 서보 모터의 생산이 확대되었습니다. 지역별 수요는 각국의 기준에 맞추어 통합형 모터 구동 패키지를 맞춤 제작하는 현지 공급업체들에 의해 뒷받침되고 있으며, 정부 프로젝트의 승인 주기가 단축되고 있습니다. 공급망이 단일 공급처 부품에 대한 의존에서 벗어나 다각화되는 가운데, 다국적 OEM 제조업체들은 물류 리스크를 억제하기 위해 베트남,태국, 인도네시아에서 전자기기 및 모터 조립 라인을 단일 거점으로 통합하고 있습니다. 이러한 투자를 통해 해당 지역은 세계 출하량의 핵심 거점으로서의 입지를 공고히 하고 있습니다.
중동의 스마트 모터 시장 규모는 2026년부터 2031년까지 연평균 성장률(CAGR) 6.71%로 확대될 것으로 예상되며, 이는 세계에서 가장 빠른 성장률입니다. 이는 사우디아라비아의 공공투자기금(PIF)이 IE4 모터와 ISO 50001 인증이 의무화된 NEOM 산업 도시에 200억 달러를 투자하고 있기 때문입니다. 아랍에미리트(UAE) 두바이 전력·상수도청은 시간대별 요금제를 도입하여 비피크 시간대의 전기 요금을 18% 인하했습니다. 이에 따라 공장들은 압축기, 펌프, 팬 어레이에 가변 속도 드라이브를 도입하도록 장려받고 있습니다. 카타르에서는 130억 달러 규모의 석유화학 산업 확장 계획에서 최대 500kW급 방폭형 스마트 모터 사용이 지정된 반면, 오만의 해수 담수화 프로젝트에서는 고염분용 펌프에 부식 방지 통합형 유닛이 채택되고 있습니다. 이러한 노력들이 맞물려 대규모 인프라 투자가 내구성이 뛰어난 설비 수주로 이어지고 있습니다.
북미는 2025년 매출의 약 24%를 차지했으며, 배터리, 반도체, 제약 시설의 모터 교체를 포함한 플랜트 업그레이드 비용의 30%를 환급해 주는 ‘인플레이션 감축법’의 세액 공제가 호재로 작용했습니다. 유럽은 22%의 점유율로 그 뒤를 이었으며, 엄격한 에코디자인 규제와 피치 제어 및 요 제어용 드라이브가 필요한 연간 4기가와트 이상의 해상 풍력 발전 신규 도입이 견인 역할을 하고 있습니다. 남미와 아프리카를 합친 비율은 지출의 14%를 차지하며, 브라질의 광업용 컨베이어와 남아프리카공화국의 수처리용 펌프가 주도적인 역할을 하고 있습니다. 이들 모두는 운영 비용을 절감하는 회생 구동 기술의 혜택을 받고 있습니다. 국경을 초월한 무역 협정과 현지 조달률 제고를 요구하는 규제 강화로 인해 공급업체들은 지역 파트너에게 조립 라이선스를 부여하도록 장려받고 있으며, 이를 통해 서비스 네트워크 확보와 리드타임 단축이 도모되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the smart motors market size was valued at USD 2.16 billion in 2025 and estimated to grow from USD 2.29 billion in 2026 to reach USD 3.03 billion by 2031, at a CAGR of 5.76% during the forecast period (2026-2031).
This report is Segmented by Component (Variable Speed Drive, Motor, Integrated Motor-Drive), Power Rating (Below 1 KW, 1-10 KW, Above 10 KW), Communication Protocol (Ethernet/IP, and More), Application (Industrial, Commercial, Automotive, Aerospace and Defense), and Geography (North America, South America, Europe, Asia-Pacific, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Motors Market Trends and Insights
Declining Cost of Integrated Motor-Drive Packages Due to SiC/GaN Power Devices
Wide-bandgap silicon carbide and gallium nitride transistors are reducing material costs by nearly one-fifth, enabling suppliers to house the motor, inverter, and feedback sensor in one enclosure without a premium. Switching frequencies above 100 kHz reduces passive component size by 40%, making integrated units lighter and easier to mount in collaborative robots and electric-vehicle coolant loops. Conduction losses fall by 30-35%, a critical gain for battery-powered mobile robots that must extend runtime between charges. Global wafer output for 200 mm SiC increased in 2025, driving module prices down from USD 85 to USD 62 and making integrated packages feasible for mid-range industrial drives. Adoption is fastest in North America and Europe, while Chinese fabs remain 12-18 months behind in yield and reliability benchmarks.
Mandates on Industrial Energy Efficiency Standards in Europe and China
The European Union extended IE4 requirements to motors below 0.75 kilowatts in July 2025, and China barred IE2 motors from new projects in January 2024, converging global rules around IE3-plus efficiency. A 75-kilowatt IE4 motor with a drive consumes 8-12% less power, recouping the USD 1,800 premium within 18 months at industrial electricity tariffs. Metals, cement, and pulp producers are thus retiring motors ahead of failure, favoring turnkey integrated units that ship with verified efficiency curves. Thailand drafted an IE3 mandate for 2027, and Vietnam is consulting on IE4 targets, signaling spillover across ASEAN. Accelerated replacement cycles underpin rising demand despite macroeconomic headwinds.
Cybersecurity Vulnerabilities in Networked Motor Systems
Fourteen firmware flaws exposed in 2025 enabled unauthenticated Modbus-TCP writes that could cause smart drives to turn off emergency stops. Only 38% of 2025 shipments met SL2 of IEC 62443, and fewer than 12% reached SL3, which mandates encryption and role-based access controls. Water utilities and refineries face the greatest risk after a 2024 breach at a European treatment plant via an unpatched PROFINET drive. Hardening steps, network segmentation, signed firmware, and intrusion detection add USD 300-800 per motor and require dual-skilled OT-security engineers, a resource that 64% of operators lack.
Other drivers and restraints analyzed in the detailed report include:
- Convergence of Smart Motor Controls with Edge AI for On-Device Optimization
- Rapid Electrification of HVAC Systems in Commercial Buildings
- Fragmented Communication Protocol Ecosystem Limiting Interoperability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Integrated motor-drive packages are growing faster than the overall smart motors market, with a 6.31% CAGR, capturing users who value 30-40% shorter installation times and reduced electromagnetic interference troubleshooting. Standalone variable-speed drives still accounted for the largest 44.56% of revenue in 2025 because retrofit projects often only replace the controller, not the motor. Yet integrated designs are penetrating mobile robots and wash-down food lines, where single-housing IP69K units avoid the cost of stainless-steel enclosures.
The shift aligns with distributed control trends; a packaging machine needing 40 servo axes can free an entire cabinet row by mounting integrated drives on each motor shaft. Asia-Pacific retains an appetite for standalone drives, as capital budgets favor incremental upgrades, but China's subsidy programs are tipping state enterprises in heavy industries toward integrated platforms above 500 kilowatts. Modular architectures persist, allowing operators to replace either the motor or the drive independently after a fault.
Sub-1 kilowatt motors are advancing 6.34% each year as e-commerce warehouses deploy autonomous mobile robots that carry four to six 0.2-0.5 kilowatt wheel drives per unit. In contrast, the 1-10 kilowatt class retained 38.72% of 2025 revenue and constitutes the backbone of industrial pumps and conveyors. Integrated 0.5-kilowatt packages fell to USD 180-240 per unit in 2025, enabling smart control of applications that once used fixed-speed induction motors.
Above 10 kilowatts, growth trails the market average because oil, gas, and metals plants prioritize ruggedness over energy savings, opting for predictive maintenance upgrades rather than full motor replacement. Building automation adds volume at the low end: a mid-size office may contain 100 variable-air-volume boxes, each with a 0.1-0.3 kilowatt smart actuator. Consequently, the smart motors market size for sub-kilowatt solutions is poised to close the gap with mid-power units over the forecast period.
Complete Report Scope:
- By Component
- Variable Speed Drive
- Motor
- Integrated Motor-Drive
- By Power Rating
- Below 1 kW
- 1-10 kW
- Above 10 kW
- By Communication Protocol
- Ethernet/IP
- PROFINET
- Modbus TCP
- Other Communication Protocols
- By Application
- Industrial
- Oil and Gas
- Metal and Mining
- Water and Wastewater
- Food and Beverage
- Chemicals
- Commercial
- HVAC and Building Automation
- Data Centers
- Automotive
- Aerospace and Defense
- Industrial
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held the highest smart motors market share of 39.74% in 2025, supported by China's CNY 300 billion (USD 42 billion) energy-efficiency fund that upgraded 1.8 million motors during the year. India's Production Linked Incentive program for white goods and air conditioners added 1.2 million units of annual capacity in 2025, while Japan and South Korea pushed servo-motor output for robotics and semiconductor fabs. Regional demand is reinforced by local suppliers that tailor integrated motor-drive packages to national standards, shortening approval cycles for government projects. As supply chains diversify away from single-source components, multinational original-equipment manufacturers are co-locating electronics and motor assembly lines in Vietnam, Thailand, and Indonesia to contain logistics risk. Such investments keep the region firmly positioned as the volume anchor of global shipments.
The smart motors market size in the Middle East is projected to expand at a 6.71% CAGR between 2026 and 2031, the fastest worldwide, as Saudi Arabia's Public Investment Fund channels USD 20 billion into the NEOM industrial city, where IE4 motors and ISO 50001 certification are mandatory. The UAE's Dubai Electricity and Water Authority introduced time-of-use tariffs that cut off-peak power prices by 18%, persuading factories to retrofit variable-speed drives for compressors, pumps, and fan arrays. Qatar's USD 13 billion petrochemical expansion specifies explosion-proof smart motors up to 500 kilowatts, while Oman's desalination projects favor corrosion-resistant integrated units for high-salinity pumps. Collectively, these initiatives convert large-scale infrastructure spending into durable equipment orders.
North America accounted for roughly 24% of 2025 revenue, energized by the Inflation Reduction Act tax credits that reimburse 30% of plant upgrades, including motor replacements in battery, semiconductor, and pharmaceutical facilities. Europe followed with a 22% share, anchored by strict Ecodesign rules and more than 4 gigawatts of annual offshore wind additions that demand pitch- and yaw-control drives. South America and Africa together made up 14% of spending, led by Brazilian mining conveyors and South African water-treatment pumps, both of which benefit from regenerative drive technology that reduces operating costs. Cross-border trade agreements and rising local-content rules are prompting suppliers to license assembly to regional partners, ensuring service coverage and shorter lead times.
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Rockwell Automation Inc.
- Nidec Corporation
- Applied Motion Products Inc.
- Bonfiglioli Riduttori S.p.A.
- Brook Crompton Holdings Ltd
- Dunkermotoren GmbH
- Emerson Electric Co.
- Fuji Electric Co. Ltd
- Moog Inc.
- Nanotec Electronic GmbH and Co. KG
- Parker Hannifin Corporation
- Regal Rexnord Corporation
- Safran Electrical and Power
- SEW-Eurodrive GmbH and Co KG
- Shanghai Moons' Electric Co. Ltd
- Turntide Technologies Inc.
- WEG S.A.
- Yaskawa Electric Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Convergence of Smart Motor Controls with Edge AI for On-Device Optimization
- 4.2.2 Mandates on Industrial Energy Efficiency Standards in Europe and China
- 4.2.3 Rapid Electrification of HVAC Systems in Commercial Buildings
- 4.2.4 Increasing Adoption in Autonomous Mobile Robots and AGVs
- 4.2.5 Rising Deployment in Offshore Wind Turbine Pitch and Yaw Systems
- 4.2.6 Declining Cost of Integrated Motor-Drive Packages Due to SiC/GaN Power Devices
- 4.3 Market Restraints
- 4.3.1 Cybersecurity Vulnerabilities in Networked Motor Systems
- 4.3.2 Fragmented Communication Protocol Ecosystem Limiting Interoperability
- 4.3.3 Prolonged Supply Chain Constraints for Power Electronics Components
- 4.3.4 Skills Gap in Condition-Based Maintenance Analytics
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Variable Speed Drive
- 5.1.2 Motor
- 5.1.3 Integrated Motor-Drive
- 5.2 By Power Rating
- 5.2.1 Below 1 kW
- 5.2.2 1-10 kW
- 5.2.3 Above 10 kW
- 5.3 By Communication Protocol
- 5.3.1 Ethernet/IP
- 5.3.2 PROFINET
- 5.3.3 Modbus TCP
- 5.3.4 Other Communication Protocols
- 5.4 By Application
- 5.4.1 Industrial
- 5.4.1.1 Oil and Gas
- 5.4.1.2 Metal and Mining
- 5.4.1.3 Water and Wastewater
- 5.4.1.4 Food and Beverage
- 5.4.1.5 Chemicals
- 5.4.2 Commercial
- 5.4.2.1 HVAC and Building Automation
- 5.4.2.2 Data Centers
- 5.4.3 Automotive
- 5.4.4 Aerospace and Defense
- 5.4.1 Industrial
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Schneider Electric SE
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Nidec Corporation
- 6.4.6 Applied Motion Products Inc.
- 6.4.7 Bonfiglioli Riduttori S.p.A.
- 6.4.8 Brook Crompton Holdings Ltd
- 6.4.9 Dunkermotoren GmbH
- 6.4.10 Emerson Electric Co.
- 6.4.11 Fuji Electric Co. Ltd
- 6.4.12 Moog Inc.
- 6.4.13 Nanotec Electronic GmbH and Co. KG
- 6.4.14 Parker Hannifin Corporation
- 6.4.15 Regal Rexnord Corporation
- 6.4.16 Safran Electrical and Power
- 6.4.17 SEW-Eurodrive GmbH and Co KG
- 6.4.18 Shanghai Moons' Electric Co. Ltd
- 6.4.19 Turntide Technologies Inc.
- 6.4.20 WEG S.A.
- 6.4.21 Yaskawa Electric Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


