|
시장보고서
상품코드
2123410
웨어러블 로봇 및 외골격 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wearable Robots And Exoskeletons - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
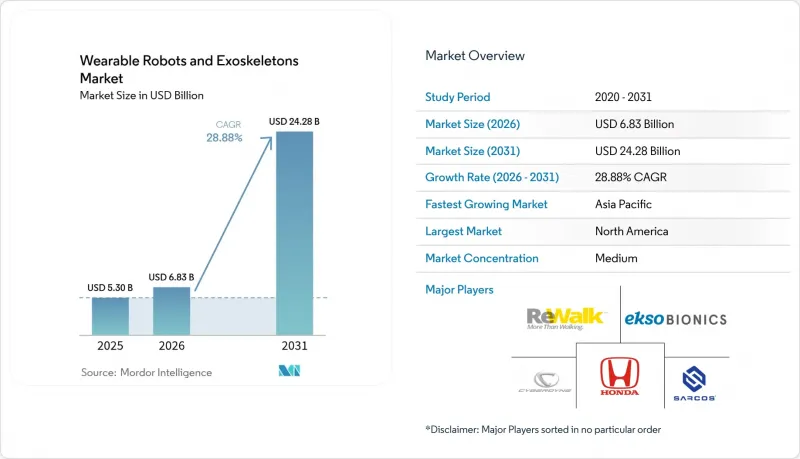
에 의하면, 웨어러블 로봇 및 외골격 시장 규모는 2025년 53억 달러에서 2026년에는 68억 3,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 28.88%로 성장을 지속하여, 2031년에는 242억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(동력식 및 수동식), 구성 요소별(센서, 액추에이터 등을 포함한 하드웨어), 신체 부위별(하지, 상지 등),최종 사용자 산업별(의료, 산업·물류 등), 이동성 유형별(이동형 또는 웨어러블, 고정형 또는 테더식), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 웨어러블 로봇 및 외골격 시장 동향과 인사이트
고령화에 따른 근골격계 질환의 급증
뇌졸중 유병률은 55세 이후 급격히 상승하고 있으며, 2025년에는 고령자가 세계 인구의 16%를 차지할 것으로 전망됩니다. 세계보건기구(WHO)의 추계에 따르면, 근골격계 질환으로 인한 장애 조정 생명년(DALY)은 17억 1,000만 년에 달할 전망입니다. 전동 보행 훈련 기기는 조절 가능한 토크를 제공함으로써 수동 방식보다 고강도의 재활을 가능하게 합니다. 일본에서는 2024년 4월부터 시행된 보조 로봇 대여 비용에 대한 보험 적용으로 인해 요양 시설에서의 하이브리드 어시스트 림(HAL) 도입이 가속화되었습니다. 한편, 미국 메디케어·메디케이드 서비스 센터(CMS)는 재택 사용 처방전을 위해 코드 E1399를 신설했습니다. 임상시험 결과, 12주간의 HAL 치료 주기 후 보행 속도가 23% 향상된 것으로 나타났습니다. 이러한 동향은 의료 분야가 여전히 웨어러블 로봇 및 외골격 시장의 핵심인 이유를 뒷받침합니다.
액추에이터와 배터리의 급격한 비용 하락
중국 공장이 희토류를 포함하지 않는 로터의 양산화를 추진한 결과, 2022년부터 2024년까지 브러쉬리스 DC 모터 가격은 18% 하락했으며, 고방전형 웨어러블 기기용 리튬 이온 배터리 팩 가격은 kWh당 137달러까지 떨어졌습니다. German Bionic사는 무게 4.8kg의 ‘Apogee ULTRA’에 1.2kWh 배터리 팩을 탑재해 12시간의 작동 시간을 실현한 결과, 한 분기 만에 300건의 대여 계약을 확보했습니다. Parker Hannifin의 소형 전기유압 액추에이터는 동급의 공압식 제품에 비해 무게를 3분의 1로 줄이면서도 150 Nm의 토크를 발휘합니다. 이러한 변화로 인해 부품 원가가 낮아지면서, 웨어러블 로봇 및 외골격 시장의 비용이 수동형 보조기 수준과 동등해지는 방향으로 나아가고 있습니다.
높은 초기 도입 비용과 수명 주기 유지 비용
산업용 장치의 정가는 40,000-8만 달러이지만, 의료용 시스템의 경우 가정용 기기조차 7만 7,000달러로 가격이 책정되어 있습니다. 배터리 및 액추에이터 교체에 따른 연간 유지보수 비용은 초기 비용의 20%에 달할 전망입니다. German Bionic사의월250유로 임대료는 연간 3,396달러에 해당하며, 이익률이 낮은 기업에게는 큰 부담이 되고 있습니다. 2년마다 이루어지는 배터리 교체에는 2,500-4,000달러,액추에이터 정밀 점검에는 5,000-8,000달러가 소요됩니다. 이러한 경제적 요인으로 인해 가격에 민감한 지역에서의 도입이 억제되고 있으며, 웨어러블 로봇 및 외골격 산업의 단기적인 성장 여지가 제한되고 있습니다.
부문 분석
동력식 설계는 2025년 매출의 66.85%를 차지하며, 2031년까지 연평균 성장률(CAGR) 31.2%로 확대될 것으로 전망되어, 의료, 국방 및 중량물 운반 업무에서의 높은 수요가 부각되고 있습니다. 전동식 제품에 기인한 웨어러블 로봇 및 외골격 시장 규모는 액추에이터 가격 하락과 자본 지출을 평준화하는 구독 모델에 힘입어 2031년까지 162억 달러에 육박할 것으로 예측됩니다. German Bionic사의 렌탈 플랜은 소유 비용을 40% 절감하는 반면, 록히드 마틴사의 ONYX에 대한 현장 데이터는 군사 분야 구매자들이 중시하는 두 자릿수의 내구성 향상을 보여주고 있습니다.
2025년에는 패시브형 솔루션이 33.15%의 점유율을 차지하며, 건설, 농업, 유지보수 분야에서 내구성이 뛰어나고 배터리가 필요 없는 장치에 대한 수요는 견조한 추세를 보이고 있습니다. SuitX사의 ‘IX BACK VOLTON’은 패시브형 허리 지지대와 옵션으로 제공되는 전동 모드를 융합하여, 가동 시간을 저해하지 않으면서 유연성을 추구하는 구매자의 요구에 부응하는 설계의 융합을 구현하고 있습니다. 충전 인프라가 부족한 지역에서는 패시브형 외골격에 대한 수요가 여전히 높고, 토크 성능의 향상이 기대됨에 따라 전동식 시스템은 전 세계 웨어러블 로봇 및 외골격 시장에서 그 보급 범위를 계속해서 확대해 나갈 것입니다.
2025년 매출액 중 하드웨어가 73.05%를 차지했으나, 센서와 모터의 가격 하락에 따라 상품화가 진행되면서 이익률이 하락하고 있습니다. 센서는 부품 원가의 15%를 차지하고 있지만, 액추에이터는 여전히 45%로 가장 큰 비중을 차지하고 있으며, 무게와 전력 소비의 감축이 진행되고 있습니다. 배터리 혁신도 시급한 과제로 대두되고 있으며, 고체 배터리 프로토타입은 2027년까지 에너지 밀도를 50% 향상시킬 전망입니다. 소프트웨어 매출은 연평균 성장률(CAGR) 32.05%로 성장을 지속하고, 있으며, 현재 차량 관리 대시보드가 지속적인 수익 모델을 뒷받침하고 있습니다.
푸리에 인텔리전스(Fourier Intelligence)의 기기 내 AI는 토크를 실시간으로 조정하여 피로를 줄이는 동시에, 병원 입찰에서 타사와의 차별화를 꾀하고 있습니다. 그 결과, 데이터 분석 및 원격 진단이 모든 계약에 정착됨에 따라 웨어러블 로봇 및 외골격 시장에서 소프트웨어의 점유율은 확대될 것입니다.
지역별 분석
2025년에는 북미가 매출의 39.85%를 차지하며 1위를 차지했습니다. FDA의 510(k) 제도에 따라 의료기기 승인 절차가 간소화된 데다, 2025 회계연도에 육군이 RDT&E(연구·개발·시험·평가)의 외골격 관련 자금으로 1,280만 달러를 계상함으로써 장기적인 노력이 드러나고 있습니다. 또한, 재향군인부(VA)의 정책 변경으로 감독 의무가 철폐되어 재향군인의 이용 기회가 확대되었습니다. 캐나다의 WorkSafeBC는 구입 비용의 50%를 보조하고 있으며, 멕시코의 자동차 산업 벨트 지역에서는 훈련이 부족한 상황임에도 불구하고 패시브형 장치의 시범 운영이 진행되고 있습니다. 이러한 요인들로 인해 북미는 웨어러블 로봇 및 외골격 시장 순위에서 1위 자리를 유지하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 32.1%로 가장 빠르게 성장하고 있습니다. 일본에서는 요양보험의 적용 범위를 확대하여 보조 로봇 대여 비용을 지원하게 되었습니다. 푸리에 인텔리전스(Fourier Intelligence)에 따르면, 2024년 말까지 중국 병원에 120대의 외골격이 도입되었습니다. 한국에서는 공장 자동화와 노동 안전 규제의 조화가 진행되는 가운데, 현대자동차는 2026년까지 ‘X-ble Shoulder’ 1,000대를 도입할 계획입니다. 인도와 호주는 초기 단계에 있지만, 새로운 자금 조달 경로와 실증 실험을 통해 미래성이 기대되고 있습니다. 해당 지역의 인구 동적 상황의 시급성과 보험 환급 제도 개혁으로 인해, 웨어러블 로봇 및 외골격 시장에 있어 매우 중요한 성장 동력이 되고 있습니다.
유럽은 2025년 매출의 약 24.95%를 차지했습니다. MDR(의료기기 규정)에 따라 승인 주기가 24개월로 연장됨에 따라, 오토복(Ottobock)이나 원더크래프트(Wondercraft)와 같은 기존 기업들이 혜택을 보고 있습니다. 독일의 산재보험 기금은 고위험 직종에서 기기 비용의 80%를 보상하고 있습니다. 영국 국민보건서비스(NHS)의 시범 시험에서는 기존 재활 치료에 비해 치료 시간이 30% 단축된 것으로 나타나 도입을 뒷받침하고 있습니다. 규제상의 병목 현상으로 인해 단기적인 확대 속도는 완만하지만, 근로자 안전에 대한 높은 인식이 웨어러블 로봇 및 외골격 시장 전반 수요를 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the wearable robots and exoskeletons market size is expected to grow from USD 5.30 billion in 2025 to USD 6.83 billion in 2026 and is forecast to reach USD 24.28 billion by 2031 at 28.88% CAGR over 2026-2031.
This report is Segmented by Type (Powered, and Passive), Component (Hardware Including Sensors, Actuators, and More), Body Part Assisted (Lower Extremity, Upper Extremity, and More), End-User Industry (Healthcare, Industrial and Logistics, and More), Mobility Type (Mobile or Wearable, and Stationary or Tethered), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Wearable Robots And Exoskeletons Market Trends and Insights
Aging-Population Surge in Musculoskeletal Disorders
Stroke prevalence climbs sharply after age 55, and older adults already represent 16% of the world population in 2025. The World Health Organization estimates 1.71 billion disability-adjusted life years from musculoskeletal conditions. Powered gait trainers provide adjustable torque that enables higher-intensity therapy than manual techniques. Japan's reimbursement for assistive-robot rentals, effective April 2024, accelerated Hybrid Assistive Limb adoption in nursing homes, while the U.S. Centers for Medicare and Medicaid Services opened code E1399 for home-use prescriptions. Clinical trials showed a 23% bump in walking speed after 12-week HAL therapy cycles. These signals demonstrate why healthcare remains the anchor of the wearable robots and exoskeletons market.
Rapid Cost Declines in Actuators and Batteries
Brushless DC motor prices slid 18% between 2022 and 2024 as Chinese plants scaled rare-earth-free rotors, and lithium-ion packs for high-discharge wearables fell to USD 137 per kWh. German Bionic embedded a 1.2 kWh pack in the 4.8 kg Apogee ULTRA, securing 12-hour runtime and 300 rental subscriptions within one quarter. Parker Hannifin's compact electro-hydraulic actuator now delivers 150 Nm at one-third the weight of pneumatic peers . These shifts lower the bill of materials, propelling the wearable robots and exoskeletons market toward cost-parity with passive braces.
High Upfront Acquisition and Lifecycle Maintenance Costs
Industrial units list at USD 40,000-80,000, while healthcare systems face USD 77,000 price tags for home-use devices. Annual maintenance adds up to 20% of initial spend, driven by battery and actuator replacements. German Bionic's EUR 250 monthly rental still equates to USD 3,396 per year, straining thin-margin firms . Battery swaps every two years cost USD 2,500-4,000; actuator overhauls run USD 5,000-8,000. These economics temper adoption in price-sensitive regions, limiting the near-term upside of the wearable robots and exoskeletons industry.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory Workplace-Injury Reduction Targets
- Record Defense Budgets for Soldier Augmentation
- Lengthy Multi-Jurisdictional Certification
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Powered designs captured 66.85% of 2025 revenue and are forecast to expand at 31.2% CAGR through 2031, underscoring their pull across healthcare, defense, and heavy-lifting tasks. The wearable robots and exoskeletons market size attributed to powered units is projected to near USD 16.2 billion by 2031, driven by falling actuator prices and subscription models that smooth capital outlays. German Bionic's rental plan reduces ownership costs 40%, while Lockheed Martin's ONYX field data signal double-digit endurance gains that military buyers value.
Passive solutions held 33.15% share in 2025, steady demand for rugged, battery-free rigs in construction, agriculture, and maintenance. SuitX's IX BACK VOLTON blends passive lumbar support with an optional powered mode, illustrating design convergence as buyers seek flexibility without compromising uptime. Passive exoskeletons remain attractive where charging infrastructure is scarce, yet incremental torque benefits mean powered systems will keep widening their reach across the global wearable robots and exoskeletons market.
Hardware delivered 73.05% of 2025 revenue, but commoditization is eroding margins as sensor and motor prices fall. Sensors accounted for 15% of bill-of-materials cost, while actuators still dominate at 45% but are shedding weight and energy draw. Battery innovation looms; solid-state prototypes promise 50% density gains by 2027. Software revenue is pacing at 32.05% CAGR, and fleet dashboards now underpin recurring-revenue bundles.
Fourier Intelligence's on-device AI tweaks torque in real time, reducing fatigue and differentiating bids in hospital tenders. As a result, software's slice of the wearable robots and exoskeletons market share will widen as data analytics and remote diagnostics cement themselves in every contract.
Complete Report Scope:
- By Type
- Powered Exoskeletons
- Passive Exoskeletons
- By Component
- Hardware
- Sensors
- Actuators
- Power Sources
- Software
- Services
- Hardware
- By Body Part Assisted
- Lower Extremity
- Upper Extremity
- Full Body
- By End-user Industry
- Healthcare
- Industrial and Logistics
- Military and Defense
- Other End-user Industrys (Public Safety, Consumer)
- By Mobility Type
- Mobile / Wearable
- Stationary / Tethered
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led with 39.85% revenue in 2025. FDA 510(k) streamlines medical clearances, while USD 12.8 million in FY 2025 Army RDT&E exoskeleton funding signals long-run commitment. VA policy changes removed supervision mandates, boosting veteran access. Canada's WorkSafeBC offers 50% purchase subsidies, and Mexico's automotive belt is piloting passive rigs despite training gaps. These factors keep North America atop the wearable robots and exoskeletons market rankings.
Asia Pacific is the fastest climber at 32.1% CAGR. Japan expanded long-term care insurance to cover assistive-robot rentals. Fourier Intelligence installed 120 exoskeletons in Chinese hospitals by late-2024. Hyundai plans 1,000 X-ble Shoulder units by 2026 as South Korea aligns factory automation with labor-safety mandates. India and Australia are early-stage yet promising due to new funding lines and pilot trials. The region's demographic urgency and reimbursement reforms make it the pivotal growth engine for the wearable robots and exoskeletons market.
Europe held roughly 24.95% of 2025 revenue. MDR lengthens approval cycles to 24 months, benefiting incumbents such as Ottobock and Wandercraft. Germany's accident-insurance funds reimburse 80% of device costs for high-risk trades. The U.K. National Health Service pilot shows a 30% reduction in therapy hours versus conventional rehab, aiding adoption. Regulatory bottlenecks moderate short-term expansion, yet strong worker-safety cultures sustain demand across the wearable robots and exoskeletons market.
- Cyberdyne Inc.
- ReWalk Robotics Ltd.
- Ekso Bionics Holdings Inc.
- Sarcos Technology and Robotics Corporation
- Honda Motor Co., Ltd.
- Myomo Inc.
- Ottobock SE and Co. KGaA
- SuitX Inc. (Ottobock Group)
- Parker Hannifin Corporation
- Bionik Laboratories Corp.
- Wandercraft SAS
- Fourier Intelligence Co., Ltd.
- Skelex B.V.
- Wearable Robotics S.r.l.
- Daiya Industry Co., Ltd.
- Panasonic Holdings Corporation
- Lockheed Martin Corporation
- Hyundai Motor Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ageing-population led surge in musculoskeletal disorders
- 4.2.2 Rapid cost declines in lightweight actuators and battery packs
- 4.2.3 Mandatory workplace-injury reduction targets in heavy industry
- 4.2.4 Record defence budgets earmarked for soldier-augmentation tech
- 4.2.5 Insurance-reimbursement approvals for in-home neuro-rehab
- 4.2.6 Emerging lease-as-a-service models for exoskeleton fleets
- 4.3 Market Restraints
- 4.3.1 High upfront acquisition and lifecycle maintenance costs
- 4.3.2 Lengthy multi-jurisdictional medical-device certification
- 4.3.3 Limited torque-to-weight ratios for full-shift industrial use
- 4.3.4 User-acceptance barriers due to device discomfort and heat
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type
- 5.1.1 Powered Exoskeletons
- 5.1.2 Passive Exoskeletons
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.1.1 Sensors
- 5.2.1.2 Actuators
- 5.2.1.3 Power Sources
- 5.2.2 Software
- 5.2.3 Services
- 5.2.1 Hardware
- 5.3 By Body Part Assisted
- 5.3.1 Lower Extremity
- 5.3.2 Upper Extremity
- 5.3.3 Full Body
- 5.4 By End-user Industry
- 5.4.1 Healthcare
- 5.4.2 Industrial and Logistics
- 5.4.3 Military and Defense
- 5.4.4 Other End-user Industrys (Public Safety, Consumer)
- 5.5 By Mobility Type
- 5.5.1 Mobile / Wearable
- 5.5.2 Stationary / Tethered
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cyberdyne Inc.
- 6.4.2 ReWalk Robotics Ltd.
- 6.4.3 Ekso Bionics Holdings Inc.
- 6.4.4 Sarcos Technology and Robotics Corporation
- 6.4.5 Honda Motor Co., Ltd.
- 6.4.6 Myomo Inc.
- 6.4.7 Ottobock SE and Co. KGaA
- 6.4.8 SuitX Inc. (Ottobock Group)
- 6.4.9 Parker Hannifin Corporation
- 6.4.10 Bionik Laboratories Corp.
- 6.4.11 Wandercraft SAS
- 6.4.12 Fourier Intelligence Co., Ltd.
- 6.4.13 Skelex B.V.
- 6.4.14 Wearable Robotics S.r.l.
- 6.4.15 Daiya Industry Co., Ltd.
- 6.4.16 Panasonic Holdings Corporation
- 6.4.17 Lockheed Martin Corporation
- 6.4.18 Hyundai Motor Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need assessment