|
시장보고서
상품코드
2123426
미용 레이저 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Aesthetic Lasers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미용 레이저 시장 규모는 2025년에 32억 3,000만 달러로 평가되었고 2026년 35억 2,000만 달러에서 2031년까지 54억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.04%를 나타낼 전망입니다.

본 보고서에서는 업계를 ‘유형별(절제 레이저, 비절제 레이저)’, ‘모달리티별(독립형 레이저 시스템 등)’, ‘휴대성별(비휴대형, 휴대형)’, ‘용도별(피부 리서페이싱/회춘, 제모 등)’, ‘최종 사용자별(병원, 외래수술센터(ASC) 등)’, 그리고 ‘지역별’로 분류하고 있습니다. 시장 규모 및 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 미용 레이저 시장 동향 및 인사이트
고령화가 진행되는 인구 구조가 정밀한 표적 치료를 뒷받침
급속히 확대되는 65세 이상 인구층은 현재 레이저를 이용한 탄력 개선 치료를 통해 피부 처짐 개선을 우선시하고 있으며, 외과적 안면 리프팅 대신 외래 치료를 선택하는 경향이 있습니다. 고령자의 진피는 치유에 시간이 걸리기 때문에 기기 제조업체들은 과잉 치료의 위험을 줄이기 위해 보다 미세한 에너지 조절 설정과 폐쇄 루프 온도 피드백 기능을 탑재하고 있습니다. 이러한 치료법을 ‘미에 대한 집착’이 아닌 ‘활력 유지’로 포지셔닝하는 클리닉은 활동성과 회복 기간을 깊이 신경 쓰는 고령 환자들로부터 더 높은 호응을 얻고 있습니다.
기술의 융합이 혁신 주기를 가속화
각 제조업체는 여러 파장이나 고주파 채널을 단일 본체에 통합하여, 실질적으로 4-5대의 독립된 기기를 1대로 집약하고 있습니다. 그 직접적인 결과로, 단일 모달리티의 주력 기기는 사양이 부족해 보이며 교체 주기가 단축되지만, 부수적인 효과로 하드웨어 본체가 아닌 소프트웨어의 업그레이드 가능성야말로 진정한 락인 메커니즘이 됩니다. Alma Hybrid의 CO2+1570 nm 조합은 미래의 경쟁 우위가 광원에서 펌웨어 업데이트를 통해 제어되는 치료 알고리즘으로 이동할 가능성을 시사합니다.
보험 급여 제한이 시장의 양극화를 초래한다.
주사나 여드름에 대한 레이저 치료는 여전히 널리 ‘선택적 치료’로 분류되며, 유나이티드 헬스케어의 의료 정책에서는 ‘의학적으로 필요하지 않다’고 간주됩니다. 그 결과, 고소득 도시 거주자들이 고급 클리닉의 수익을 견인하는 반면, 중견 의료 제공업체들은 접근성을 확대하기 위해 독창적인 자금 조달이나 1회당 지불 플랜에 의존하고 있습니다. 이러한 양극화는 주력 시스템을 도입할 자금이 없는 신흥 시장의 기업이들을 대상으로 한 저비용 휴대용 기기에 틈새 시장을 개척하고 있습니다.
부문 분석
2025년, 미용 레이저 시장 규모 중 비절제형 시스템이 64.35%의 시장 점유율을 차지했습니다. 이는 일상생활에 지장을 주지 않는 치료를 원하는 소비자의 요구에 힘입은 결과입니다. 프랙셔널 트륨 파이버 레이저가 아시아인의 광노화 사례에서 표피 두께를 개선한다는 증거는 인종에 관계없이 적용 가능함을 뒷받침합니다. 이러한 우위는 또한 클리닉이 회복 기간이 없는 결과를 강조하기 위해 마케팅 예산의 과반수를 할당할 가능성을 시사하며, 경쟁의 초점을 단일 시술의 유효성에서 누적적인 피부 질 개선으로 미묘하게 전환하고 있음을 의미합니다.
2025년 시점에서 단일 기능 레이저는 71.20%의 점유율을 유지한 반면, 멀티 플랫폼형 하이브리드 기기는 연평균 성장률(CAGR) 12.90%를 기록했습니다. 이에 따라 금융사는 조만간 감가상각 일정을 재조정하여, 멀티플랫폼형 장비를 기존의 자본 설비라기보다는 소프트웨어를 통해 업그레이드가 가능한 자산으로 취급하게 될 가능성이 있습니다. 경제적 수명이 길어짐에 따라 리스 모델의 매력이 높아져, 리스 회사와 제조업체 모두에게 지속적인 수익원이 창출될 것입니다.
지역별 분석
북미는 견고한 의료 서비스 제공업체 네트워크와 기술의 조기 도입에 힘입어 2025년 세계 시장 점유율의 39.60%를 차지했습니다. 미국 내 최소 침습적 ‘미세 조정(tweakment)’ 시술 시장 규모는 의료 종사자들이 극적인 변화보다는 점진적인 수정을 중시하고 있음을 뒷받침합니다. 이와 함께, 주요 대도시권에서 환자들의 기대는 주사제와 비절제형 레이저를 결합한 시너지 효과가 있는 시술에 점점 더 중점을 두고 있어, 통합형 클리닉에 크로스셀링의 기회가 시사되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 11.75%를 나타낼 것으로 예측되며, 이는 다른 어떤 지역보다 빠른 속도입니다. 피부 톤의 균일함을 문화적 이상으로 중시하는 국가들에서는 피코초 및 나노초 색소 레이저의 도입이 평균 이상의 속도로 진행되고 있습니다. 기미와 혈관성 홍반 모두에 대응 가능한 장비를 갖춘 클리닉은 시장 점유율을 확보할 전망입니다. 시술 가격 경쟁이 치열한 시장에서 두 가지 적응증에 대응할 수 있는 범용성 덕분에 설비 투자 회수 기간이 단축되기 때문입니다.
유럽은 성숙해 가면서도 계속 확대되고 있는 시장이며, 자연스러운 시술 결과를 선호하기 때문에 저출력 조사를 여러 번에 나누어 진행하는 시술 프로토콜이 권장되고 있습니다. 간접적인 영향으로, 특히 입소문 소개가 큰 비중을 차지하는 독일, 프랑스, 영국에서는 많은 클리닉에서 신규 환자 유치보다 기존 환자 유지를 통해 주요 수익원을 확보할 가능성이 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the aesthetic lasers market size was valued at USD 3.23 billion in 2025 and estimated to grow from USD 3.52 billion in 2026 to reach USD 5.43 billion by 2031, at a CAGR of 9.04% during the forecast period (2026-2031).
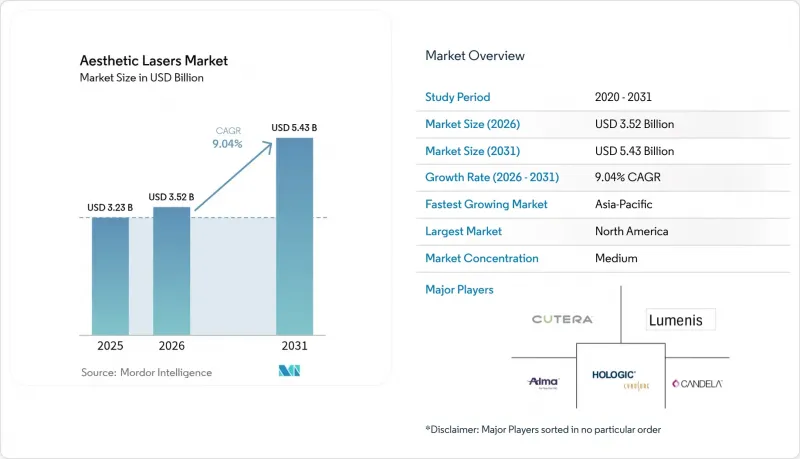
This report Segments the Industry Into by Type (Ablative Laser, Non-Ablative Laser), by Modality (Standalone Laser Systems, and More), by Portability (Non-Portable and Portable), by Application (Skin Resurfacing/Skin Rejuvenation, Hair Removal, and More), End-User (Hospitals, Ambulatory Surgical Centers, and More), and by Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Aesthetic Lasers Market Trends and Insights
Aging Demographics Driving Precision-Targeted Treatments
A rapidly expanding 65-plus cohort now prioritizes skin laxity correction through laser tightening, substituting surgical facelifts with outpatient regimens. Because geriatric dermis heals more slowly, device makers are integrating finer energy-increment settings and closed-loop temperature feedback to mitigate overtreatment risk . Clinics that position these protocols as "maintenance of vitality" rather than vanity appeal find higher acceptance among older patients intimately concerned with mobility and recovery time.
Technological Convergence Accelerates Innovation Cycles
Makers are stacking multiple wavelengths and radiofrequency channels into single chassis, effectively collapsing four or five standalone devices into one. The direct result is shorter replacement cycles as single-modality workhorses appear under-spec'd, but the secondary effect is that software upgradability becomes the real lock-in mechanism, not the hardware shell. Alma Hybrid's CO2 + 1570 nm pairing illustrates how future competitive advantage may pivot from light sources to treatment algorithms controlled by firmware updates.
Limited Reimbursement Creates Market Stratification
Laser treatment for rosacea and acne remains widely classified as elective, with UnitedHealthcare's medical policy deeming it "not medically necessary" . Consequently, high-income urban dwellers propel premium clinic revenues, while mid-market providers rely on creative financing or pay-per-session plans to broaden access. The stratification opens a niche for low-cost portable units targeting emerging-market entrepreneurs who lack capital for flagship systems.
Other drivers and restraints analyzed in the detailed report include:
- Picosecond Technology Transforms Millennial Aesthetic Priorities
- Medical Tourism Reshapes Global Treatment Distribution
- Regulatory Complexity Delays Innovation Commercialization
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-ablative systems held 64.35 % market share of the aesthetic lasers market size in 2025, propelled by consumer insistence on treatments that do not interfere with daily routines. Evidence showing that fractional thulium fiber lasers improve epidermal thickness in Asian photodamage cases underscores their cross-ethnic applicability. This dominance also implies that clinics may allocate a disproportionate share of marketing budgets to highlight downtime-free outcomes, subtly shifting competitive discourse away from single-session efficacy toward cumulative skin-quality upgrades.
Standalone lasers retained 71.20 % share in 2025, yet multiplatform hybrids are posting a 12.90 % CAGR. The embedded inference is that financing companies could soon recalibrate depreciation schedules, treating multiplatform units more like software-upgradable assets than conventional capital equipment. Longer economic life increases the appeal of leasing models, creating recurring-revenue streams for both lessors and manufacturers.
Complete Report Scope:
- By Type
- Ablative Lasers
- Carbon Dioxide (CO2) Laser
- Erbium Laser
- Non-Ablative Lasers
- Pulsed-Dye Laser (PDL)
- Nd:YAG Laser
- Alexandrite Laser|
- Diode Laser
- Ablative Lasers
- By Modality
- Standalone Laser Systems
- Multiplatform / Hybrid Systems
- By Portability
- Non-Portable
- Portable
- By Application
- Skin Resurfacing & Rejuvenation
- Hair Removal
- Acne & Scar Management
- Tattoo Removal
- Body Sculpting & Skin Tightening
- Vascular & Pigmented Lesion Treatmen
- By End User
- Hospitals
- Dermatology & Aesthetic Clinics
- Medical Spas & Beauty Centres
- Ambulatory Surgical Centres
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- GCC
- Rest of Middle East
- North America
Geography Analysis
North America controlled 39.60% of global market share in 2025, supported by robust provider networks and early technology adoption. The market size of U.S. minimally invasive "tweakment" procedures reinforces the importance practitioners place on incremental corrections rather than dramatic makeovers. A parallel observation is that patient expectations in major metropolitan areas increasingly revolve around synergistic protocols combining injectables with sub-ablative lasers, suggesting cross-selling opportunities for integrated practices.
Asia-Pacific is forecast to register 11.75% CAGR through 2031, the fastest pace of any region. Countries emphasizing even skin tone as a cultural ideal drive above-average adoption of picosecond and nano-second pigment lasers. Clinics that stock devices capable of addressing both melasma and vascular redness stand to capture share, because dual-indication versatility defrays capital investment more quickly in markets where procedure pricing is tightly competitive.
Europe remains a mature yet expanding market, where preference for natural-appearing outcomes encourages protocols that blend low-energy passes over multiple sessions. An indirect implication is that patient retention may supersede new-patient acquisition as the primary revenue lever for many clinics, particularly in Germany, France, and the UK where word-of-mouth referrals carry considerable weight.
- Alma Lasers
- Candela Medical
- Cynosure
- Lumenis
- Cutera
- Solta Medical
- Aerolase
- Sciton
- El.En.
- Iridex
- sharplight technologies
- Fotona d.o.o.
- Jeisys Medical
- Lutronic
- Venus Concept Inc.
- InMode Ltd.
- Quanta System S.p.A.
- Zimmer MedizinSysteme
- BTL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Population & Rise in Skin-Laxity-Driven Laser Tightening
- 4.2.2 Growing Technological Advancements
- 4.2.3 AI-Enabled Laser Parameter Optimization Reducing Adverse Events
- 4.2.4 Uptake of Picosecond Lasers for Pigmented Lesions Among Millennials
- 4.2.5 Medical-Tourism-Led Boom in Laser Hair Removal
- 4.2.6 Changing Lifestyle and Growing Disposable Income
- 4.3 Market Restraints
- 4.3.1 Limited Reimbursement in Public Healthcare Systems
- 4.3.2 Stringent Laser Safety Regulations Delaying Product Launches
- 4.3.3 Social Stigma Associated With Cosmetic Treatments
- 4.3.4 Shortage of Trained Laser Technicians in Emerging Nations
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Scenario
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Ablative Lasers
- 5.1.1.1 Carbon Dioxide (CO2) Laser
- 5.1.1.2 Erbium Laser
- 5.1.2 Non-Ablative Lasers
- 5.1.2.1 Pulsed-Dye Laser (PDL)
- 5.1.2.2 Nd:YAG Laser
- 5.1.2.3 Alexandrite Laser|
- 5.1.2.4 Diode Laser
- 5.1.1 Ablative Lasers
- 5.2 By Modality
- 5.2.1 Standalone Laser Systems
- 5.2.2 Multiplatform / Hybrid Systems
- 5.3 By Portability
- 5.3.1 Non-Portable
- 5.3.2 Portable
- 5.4 By Application
- 5.4.1 Skin Resurfacing & Rejuvenation
- 5.4.2 Hair Removal
- 5.4.3 Acne & Scar Management
- 5.4.4 Tattoo Removal
- 5.4.5 Body Sculpting & Skin Tightening
- 5.4.6 Vascular & Pigmented Lesion Treatmen
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Dermatology & Aesthetic Clinics
- 5.5.3 Medical Spas & Beauty Centres
- 5.5.4 Ambulatory Surgical Centres
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East
- 5.6.5.1 GCC
- 5.6.5.3 Rest of Middle East
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Alma Lasers
- 6.4.2 Candela Medical
- 6.4.3 Cynosure
- 6.4.4 Lumenis
- 6.4.5 Cutera
- 6.4.6 Solta Medical
- 6.4.7 Aerolase Corporation
- 6.4.8 Sciton Inc.
- 6.4.9 El.En. Group
- 6.4.10 IRIDEX Corporation
- 6.4.11 sharplight technologies
- 6.4.12 Fotona d.o.o.
- 6.4.13 Jeisys Medical
- 6.4.14 Lutronic Corporation
- 6.4.15 Venus Concept Inc.
- 6.4.16 InMode Ltd.
- 6.4.17 Quanta System S.p.A.
- 6.4.18 Zimmer MedizinSysteme
- 6.4.19 BTL Industries
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment