

|
시장보고서
상품코드
2123434
데이터 처리 및 호스팅 서비스 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Data Processing And Hosting Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
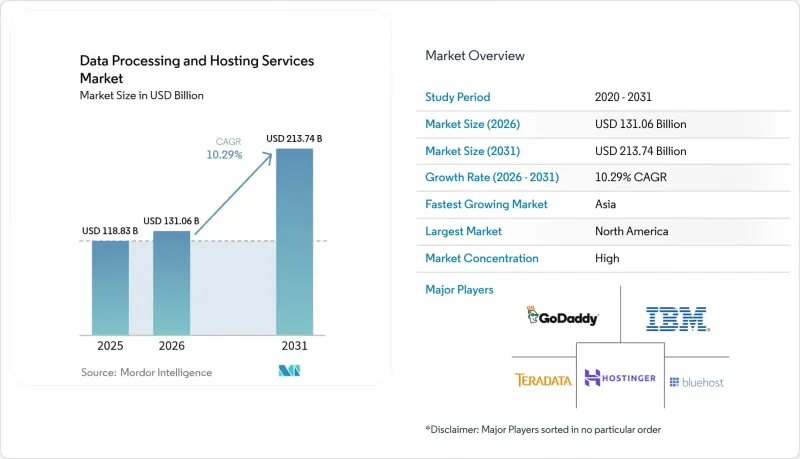
에 의하면, 데이터 처리 및 호스팅 서비스 시장 규모는 2025년 1,188억 3,000만 달러에서 2026년에는 1,310억 6,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 10.29%로 성장을 지속하여, 2031년에는 2,137억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 조직 규모(대기업 및 중소기업(SME)), 서비스 유형별(데이터 처리 서비스 및 호스팅 서비스), 배포 모델(퍼블릭 클라우드, 프라이빗 클라우드, 하이브리드 및 멀티 클라우드), 최종 사용자 산업(IT 및 통신, 은행, 금융서비스 및 보험(BFSI), 소매 및 전자상거래,제조, 헬스케어 및 생명과학 등) 및 지역별로 분류되어 있습니다.
전 세계 데이터 처리 및 호스팅 서비스 시장 동향과 인사이트
기업 워크로드의 하이퍼스케일 클라우드 데이터센터로의 이전 확대
기업들은 미션 크리티컬 시스템을 하이퍼스케일 지역으로 이전함으로써 자본 예산의 위험을 지속적으로 줄이고 있으며, 미국의 데이터센터 전력 수요는 2030년까지 35GW로 두 배 증가할 것으로 예측됩니다. 이러한 움직임은 On-Premise 환경에서는 여전히 막대한 비용이 드는 AI 가속기 및 관리형 보안 서비스에 대한 접근을 기반으로 하여, 점점 더 기능 중심으로 변화하고 있습니다. 특히 전력 할당량에 제약이 있는 애쉬번, 피닉스, 더블린, 프랑크푸르트에서는 물리적 인계보다 수년 앞서 임대 전 계약을 통해 용량을 확보하는 움직임이 나타나고 있습니다.
AI/ML 워크로드의 폭발적인 증가가 고밀도 GPU 호스팅 수요를 끌어올리고
2025년까지 4만 개 이상의 기업이 디스크리트 GPU에서 프로덕션 환경의 AI를 가동하게 되어, 계산 밀도와 냉각 요구 사항이 높아질 전망입니다. Lambda 및 CoreWeave와 같은 전용 GPU 클라우드는 훈련, 미세 조정, 추론 워크로드를 위해 H100 및 MI300 재고를 보장하고 있어 3자리 수의 성장률을 기록하고 있습니다.
전력망의 불안정성과 에너지 요금 급등이 데이터센터 확장을 제한하고 있습니다.
남아시아와 아프리카의 전력 공급 부족 및 추가 요금이 신규 건설의 걸림돌이 되고 있습니다. 2023년, 데이터센터는 미국 전력의 176 TWh를 소비했으며, 이는 국내 수요의 4.4%에 해당합니다. 이는 컴퓨팅 수요의 확대와 전력망 용량 간의 긴장 관계를 여실히 드러내고 있습니다. 사업자들은 현장 태양광 발전과 배터리 저장 장치를 결합한 솔루션이나 마이크로그리드 솔루션으로 전환하고 있으며, 이로 인해 자본 요건이 증가하고 도입 일정이 장기화되고 있습니다.
부문 분석
대기업은 2025년 매출의 70.35%를 차지하며, 풍부한 자금력을 바탕으로 메인프레임 현대화, 컨테이너 오케스트레이션 도입, 세계 재해 복구(DR) 복제본 구축을 추진하고 있습니다. 대조적으로, 중소기업은 가장 빠르게 성장하고 있으며, 간소화된 마이그레이션 도구, 마켓플레이스 크레딧, 관리형 DevOps 서비스를 통해 기술적 장벽이 낮아짐에 따라 연평균 성장률(CAGR) 11.55%로 확대되고 있습니다. 아프리카 및 라틴아메리카 시장에서는 중소기업의 90% 이상이 디지털 결제를 도입하고 있어, 디지털화의 광범위한 확산이 두드러지고 있습니다. 정부가 교육 및 클라우드 이용권 지원에 보조금을 지급함에 따라 그 보급 범위는 더욱 확대되고 있습니다. 중소기업용 데이터 처리 및 호스팅 서비스 시장 규모는 2030년까지 두 배로 증가할 것으로 예측되지만, 대기업의 시스템 기반도 계속 확대되고 있어 총 지출에서 중소기업이 차지하는 비중은 30% 미만에 그칠 것으로 전망됩니다.
중소기업의 클라우드 활용 성숙화는 새로운 파트너 생태계를 창출하고 있습니다. 리셀러들은 POS(판매 시점 정보 관리), 분석, 현지 언어 지원을 묶어 제공하고, 컴퓨팅 비용을 서비스 요금에 포함시키고 있습니다. 고급 가시성 스택은 이상을 감지하고 복구 스크립트를 자동으로 적용함으로써, 과거 중소기업을 가로막았던 기술 격차를 완화하고 있습니다. 이러한 효율화는 궁극적으로 구독 갱신 및 점진적인 업셀링을 촉진하여, 중소기업 부문을 데이터 처리 및 호스팅 서비스 시장 전체의 지속적인 성장 동력으로 자리매김하고 있습니다.
2025년에는 호스팅 서비스가 해당 부문 매출의 63.40%를 차지하며, 그 기반에는 신뢰할 수 있는 컴퓨팅, 스토리지, 네트워크 프리미티브가 자리 잡고 있습니다. 클라우드 호스팅(IaaS, PaaS, SaaS) 하위 부문은 하이퍼스케일러에 의한 수요 집중에 따라 탄력적인 확장, 번들형 API 및 단가 하락에 힘입어 2031년까지 연평균 성장률(CAGR) 13.85%를 나타낼 것으로 전망됩니다. 고객들은 워크로드에 최적화된 티어, AI용 GPU 클러스터, 웹 티어용 ARM 코어, 재무 원장용 z-parity CICS as a Service를 점점 더 선호하고 있습니다. 동시에, 기업들이 클라우드 네이티브 재설계, 데이터 파이프라인 리팩토링 및 FinOps 거버넌스를 추구함에 따라 전문 서비스 매출이 확대되고 있습니다. 엣지 및 코로케이션 제공업체들은 포털에 클라우드와 유사한 프로비저닝 기능을 통합하여 코어 호스팅과 분산형 호스팅의 경계를 모호하게 만들고 있습니다. 향후에는 데이터 준비와 컴퓨팅을 융합한 통합 파이프라인이 독립 ETL 벤더의 시장 점유율을 잠식하고, 그 수익 구조를 데이터 처리 및 호스팅 서비스 시장의 게이트키퍼에 통합해 나갈 것입니다.
재무적 유연성은 여전히 큰 매력입니다. 초 단위 과금 및 지속 이용 크레딧을 통해 총 소유 비용(TCO)이 절감됩니다. 에너지 비용이 변동하는 가운데, 워크로드는 실시간 전력 현물 가격을 기반으로 지역 간에 재조정됩니다. 이는 클라우드 자동화를 통해서만 실현 가능한 기능입니다. 그 결과, 구조적으로 높은 가동률이 실현되어, 제공업체에게는 이익률 확대로, 테넌트에게는 비용 예측 가능성으로 이어집니다.
지역별 분석
북미는 광대한 광섬유 백본, 풍부한 세제 혜택, 그리고 고밀도 하이퍼스케일 클러스터를 바탕으로 2025년 매출의 38.62%를 차지했습니다. 버지니아주 라우던 카운티만 해도 3,000만 제곱피트 이상의 레이즈드 플로어를 보유하고 있지만, 현재 변압기 제약으로 인해 송전망 연결이 일시 중단되는 상황에 직면해 있습니다. 각 제공업체들은 지속가능성에 대한 엄격한 감시를 충족하기 위해 캠퍼스 규모의 마이크로그리드, 연중무휴 24시간 가동되는 재생에너지 PPA, 그리고 폐열 재활용 프로그램을 도입하고 있습니다. AWS, 마이크로소프트, 구글은 2025년에 미국 내 신규 데이터센터 건설에 총 2550억 달러 이상을 할당하여 해당 지역의 용량 면에서 우위를 확보하고 있습니다. 캘리포니아주의 CCPA나 텍사스주의 개인정보 보호 법안 등 주 차원의 개인정보 보호 관련 법규로 인해 데이터 사본을 주 내에 보관해야 할 가능성이 있어, 데이터 처리 및 호스팅 서비스 시장의 도입 방식에 미묘한 변화를 가져오고 있습니다.
아시아에서는 5G 보급, 디지털 뱅킹, AI 스타트업 생태계가 융합되어 13.18%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 싱가포르의 신규 데이터센터 허가 유예 조치로 인해 설비 투자는 조호르, 바탐, 방콕, 하이데라바드로 이동하고 있으며, 이들 지역은 모두 해당 지역의 저지연 허브가 되기 위해 경쟁하고 있습니다. 일본의 통신 사업자들은 홋카이도의 미활용 지열 자원을 활용하는 한편, 중국의 하이퍼스케일러 기업들은 국내의 슈퍼 앱 스택을 동남아시아로 확장하며 컴퓨팅과 결제·물류를 융합하고 있습니다. 스마트폰 보급률의 상승과 실시간 번역 서비스의 확대로 데이터 흐름이 증가하며 지속적인 수요가 정착되고 있습니다.
유럽의 주권 확보를 위한 노력이 조달 동향을 주도하고 있습니다. EU의 ‘디지털 유럽 프로그램’은 클라우드 마켓플레이스와 보안 센터에 9억 유로를 배정하여 국내 역량 강화를 촉진하고 있습니다. 독일과 프랑스는 원자력 및 수력 발전의 혼합 전력 공급을 내세우며, AI 훈련 클러스터 유치를 놓고 경쟁하고 있습니다. ‘가이아-엑스(Gaia-X)’는 상호운용성 기준을 수립하고 있으나, 당초 구상보다는 지연되고 있습니다. 북유럽 국가들은 저렴한 수력발전을 활용하고 있지만, 광섬유 회선 경로가 제한적이라는 과제에 직면해 있습니다. 동유럽 국가들은 경제특구를 통해 투자자를 유치하고 있으나, 지정학적 리스크는 여전히 장벽으로 작용하고 있습니다. 특히 주목할 점은 브렉시트 이후 영국이 데이터센터 장비에 대한 부가가치세(VAT)를 완화하여 대서양을 가로지르는 투자를 유치하고, 런던의 주도적 지위를 강화하고 있다는 점입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the data processing and hosting services market size is expected to grow from USD 118.83 billion in 2025 to USD 131.06 billion in 2026 and is forecast to reach USD 213.74 billion by 2031 at 10.29% CAGR over 2026-2031.
This report is Segmented by Organisation (Large Enterprise and Small and Medium Enterprises [SME]), Offering (Data Processing Services and Hosting Services), Deployment Model (Public Cloud, Private Cloud, and Hybrid and Multi-Cloud), End-User Industry (IT and Telecommunication, BFSI, Retail and E-Commerce, Manufacturing, Healthcare and Life Sciences, and More), and Geography
Global Data Processing And Hosting Services Market Trends and Insights
Growing Migration of Enterprise Workloads to Hyperscale Cloud Data-Centers
Enterprises continue to de-risk capital budgets by shifting mission-critical systems to hyperscale regions, with U.S. datacenter power demand expected to double to 35 GW by 2030. The move is increasingly capability-driven, anchored in access to AI accelerators and managed security services that remain prohibitively expensive on-prem. Pre-lease agreements now secure capacity years ahead of physical handover, particularly in Ashburn, Phoenix, Dublin, and Frankfurt, where power allotments are constrained.
AI/ML Workload Explosion Elevating Demand for High-Density GPU Hosting
By 2025, over 40,000 companies will run production AI on discrete GPUs, raising computational density and cooling requirements. Dedicated GPU clouds such as Lambda and CoreWeave post triple-digit growth as they guarantee H100 and MI300 inventory for training, fine-tuning, and inference workloads.
Power-Grid Instability and Rising Energy Tariffs Limiting Data-Center Expansion
Electricity supply shortfalls and surcharges in South Asia and Africa throttle new builds. Data centers consumed 176 TWh of U.S. power in 2023, or 4.4% of national demand, underscoring the tension between compute growth and grid capacity. Operators pivot to onsite solar-plus-battery and micro-grid solutions, inflating capital requirements and elongating deployment schedules.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Edge-Native Applications Requiring Distributed Micro-Hosting
- Emergence of Sovereign-Cloud Mandates Boosting In-Country Hosting
- Data-Sovereignty Conflicts Hindering Cross-Border Hosting
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large enterprises controlled 70.35% of 2025 revenue, leveraging deep coffers to modernize mainframes, adopt container orchestration, and spin up global DR replicas. In contrast, SMEs are the fastest movers, accelerating at 11.55% CAGR as simplified migration tooling, marketplace credits, and managed DevOps services flatten technical barriers. In African and Latin American markets, more than 90% of SMEs have adopted digital payments, underscoring widespread digital adoption. Governments subsidize training and cloud vouchers, further broadening reach. The absolute data processing and hosting services market size for SMEs is projected to double by 2030, while their slice of overall spending remains under 30% because large-enterprise estates also keep expanding.
SME cloud maturation creates new partner ecosystems. Resellers bundle point-of-sale, analytics, and local-language support, embedding compute costs into service fees. Advanced observability stacks surface anomalies and auto-apply remediation scripts, mitigating the skill gap that once stymied smaller firms. Those efficiencies, in turn, reinforce subscription renewals and incremental upsell, positioning the SME segment as a durable growth flywheel within the broader data processing and hosting services market.
Hosting services delivered 63.40% of sector revenue in 2025, anchored by reliable compute, storage, and network primitives. The sub-segment of cloud hosting (IaaS, PaaS, SaaS) commands a 13.85% CAGR to 2031, fueled by elastic scaling, bundled APIs, and declining unit pricing as hyperscalers aggregate demand. Customers increasingly favor workload-optimized tiers, GPU clusters for AI, ARM cores for web tier, and z-parity CICS as a service for financial ledgers. Concurrently, professional services revenue grows as firms seek cloud-native redesign, data pipeline refactor, and FinOps governance. Edge and colocation providers embed cloud-like provisioning into portals, blurring the lines between core and distributed hosting. Over time, integrated pipelines that marry data preparation with compute will erode standalone ETL vendors, folding their economics into the data processing and hosting services market gatekeepers.
Financial flexibility remains a draw. Pay-by-the-second billing and sustained-usage credits lower the total cost of ownership. As energy costs fluctuate, workloads re-balance across regions based on real-time power spot prices, a capability accessible only through cloud automation. The result is a structurally higher utilization rate, translating to margin expansion for providers and cost predictability for tenants.
Complete Report Scope:
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises (SME)
- By Offering
- Data Processing Services
- Data Entry Services
- Data Mining Services
- Data Cleansing and Formatting
- Data Scanning and Indexing
- Managed ETL and Analytics
- Hosting Services
- Shared (Reseller) Hosting
- Virtual Private Server (VPS) Hosting
- Dedicated Server Hosting
- Cloud Hosting
- IaaS
- PaaS
- SaaS
- Managed WordPress Hosting
- Application Hosting
- Colocation and Bare-Metal
- Data Processing Services
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid and Multi-Cloud
- By End-user Industry
- IT and Telecommunication
- BFSI
- Retail and E-commerce
- Manufacturing
- Healthcare and Life Sciences
- Media and Entertainment
- Government and Public Sector
- Others (Education, Hospitality, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- North America
Geography Analysis
North America claimed 38.62% of 2025 revenue on the back of vast fiber backbones, generous tax incentives, and dense hyperscale clusters. Loudoun County, Virginia, alone hosts over 30 million square feet of raised floor and is now facing grid-interconnection pauses due to transformer constraints. Providers respond with campus-scale micro-grids, 24X7 renewable PPAs, and reclaimed-heat reuse programs to counter sustainability scrutiny. AWS, Microsoft, and Google collectively earmarked more than USD 255 billion for new U.S. halls in 2025, ensuring the region's capacity lead. Privacy legislation at the state level, such as California CCPA and Texas privacy bills, could demand that data copies remain in-state, subtly reshaping deployment footprints inside the data processing and hosting services market.
Asia records the fastest 13.18% CAGR as 5G proliferation, digital banking, and AI start-up ecosystems converge. Singapore's moratorium on new datacenter permits diverts cap-ex toward Johor, Batam, Bangkok, and Hyderabad, all vying to become the region's latency hubs. Japanese operators exploit underused geothermal in Hokkaido while Chinese hyperscalers replicate domestic super-app stacks to Southeast Asia, blending compute with payments and logistics. Smartphone saturation and real-time translation services multiply data flows, anchoring durable demand.
Europe's sovereignty agenda steers procurement trends. The EU's Digital Europe Programme has allocated EUR 900 million to cloud marketplaces and security centers, catalysing domestic capacity. Germany and France vie for AI training clusters by touting nuclear and hydro power mixes. Gaia-X lays interoperability standards, albeit slower than first envisioned. Nordic states leverage cheap hydroelectricity yet grapple with limited fiber routes; Eastern European states woo investors through special economic zones, though geopolitical risk remains a hurdle. Notably, post-Brexit UK relaxes VAT on datacenter gear, attracting trans-Atlantic investment and reinforcing London's pole position.
- Amazon Web Services Inc.
- Microsoft Corporation (Azure)
- Alphabet Inc. (Google Cloud Platform)
- International Business Machines Corporation
- Alibaba Cloud
- Oracle Corporation
- SAP SE
- Teradata Corporation
- Hewlett Packard Enterprise Development LP
- GoDaddy Operating Company LLC
- Bluehost (Newfold Digital Inc.)
- HostGator.com LLC
- Hostinger International Ltd.
- SiteGround Hosting Ltd.
- A2 Hosting Inc.
- DreamHost LLC
- GreenGeeks LLC
- DigitalOcean Holdings Inc.
- OVHcloud
- Equinix Inc.
- Hetzner Online GmbH
- Cloudflare Inc.
- Salesforce.com Inc.
- Alteryx Inc.
- Cloudera Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Migration of Enterprise Workloads to Hyperscale Cloud Data-Centers (North America and Europe)
- 4.2.2 Proliferation of Edge-Native Applications Requiring Distributed Micro-Hosting (Asia and Oceania)
- 4.2.3 Emergence of Sovereign Cloud Mandates Boosting In-Country Hosting (EU and Middle-East)
- 4.2.4 Zero-Trust and Data-Residency Compliance Driving Managed Processing Contracts (BFSI and Healthcare)
- 4.2.5 AI/ML Workload Explosion Elevating Demand for High-Density GPU Hosting (Global)
- 4.2.6 SME Digital-First Strategies Fueling Bundled Processing?Hosting Packages (South America and Africa)
- 4.3 Market Restraints
- 4.3.1 Power-Grid Instability and Rising Energy Tariffs Limiting Data-Center Expansion (Africa and South Asia)
- 4.3.2 Escalating Cloud Egress Fees Creating Vendor-Lock Concerns (Global)
- 4.3.3 Data-Sovereignty Conflicts Hindering Cross-Border Hosting (Europe vs US)
- 4.3.4 Shortage of Certified Cloud Talent Delaying Migration Projects (Nordics and GCC)
- 4.4 Value/Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technological Outlook
- 4.6.1 Container-Native Hosting and Kubernetes Automation
- 4.6.2 Serverless Data-Processing Platforms
- 4.6.3 Silicon Specialisation (DPUs/G-chips)
- 4.7 Investment Analysis
- 4.8 Regulatory Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Organisation Size
- 5.1.1 Large Enterprises
- 5.1.2 Small and Medium Enterprises (SME)
- 5.2 By Offering
- 5.2.1 Data Processing Services
- 5.2.1.1 Data Entry Services
- 5.2.1.2 Data Mining Services
- 5.2.1.3 Data Cleansing and Formatting
- 5.2.1.4 Data Scanning and Indexing
- 5.2.1.5 Managed ETL and Analytics
- 5.2.2 Hosting Services
- 5.2.2.1 Shared (Reseller) Hosting
- 5.2.2.2 Virtual Private Server (VPS) Hosting
- 5.2.2.3 Dedicated Server Hosting
- 5.2.2.4 Cloud Hosting
- 5.2.2.4.1 IaaS
- 5.2.2.4.2 PaaS
- 5.2.2.4.3 SaaS
- 5.2.2.5 Managed WordPress Hosting
- 5.2.2.6 Application Hosting
- 5.2.2.7 Colocation and Bare-Metal
- 5.2.1 Data Processing Services
- 5.3 By Deployment Model
- 5.3.1 Public Cloud
- 5.3.2 Private Cloud
- 5.3.3 Hybrid and Multi-Cloud
- 5.4 By End-user Industry
- 5.4.1 IT and Telecommunication
- 5.4.2 BFSI
- 5.4.3 Retail and E-commerce
- 5.4.4 Manufacturing
- 5.4.5 Healthcare and Life Sciences
- 5.4.6 Media and Entertainment
- 5.4.7 Government and Public Sector
- 5.4.8 Others (Education, Hospitality, etc.)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Rest of Europe
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 UAE
- 5.5.4.3 Turkey
- 5.5.4.4 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Nigeria
- 5.5.5.3 Rest of Africa
- 5.5.6 Asia Pacific
- 5.5.6.1 China
- 5.5.6.2 India
- 5.5.6.3 Japan
- 5.5.6.4 South Korea
- 5.5.6.5 Rest of Asia Pacific
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA, Partnerships, Funding)
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amazon Web Services Inc.
- 6.4.2 Microsoft Corporation (Azure)
- 6.4.3 Alphabet Inc. (Google Cloud Platform)
- 6.4.4 International Business Machines Corporation
- 6.4.5 Alibaba Cloud
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Teradata Corporation
- 6.4.9 Hewlett Packard Enterprise Development LP
- 6.4.10 GoDaddy Operating Company LLC
- 6.4.11 Bluehost (Newfold Digital Inc.)
- 6.4.12 HostGator.com LLC
- 6.4.13 Hostinger International Ltd.
- 6.4.14 SiteGround Hosting Ltd.
- 6.4.15 A2 Hosting Inc.
- 6.4.16 DreamHost LLC
- 6.4.17 GreenGeeks LLC
- 6.4.18 DigitalOcean Holdings Inc.
- 6.4.19 OVHcloud
- 6.4.20 Equinix Inc.
- 6.4.21 Hetzner Online GmbH
- 6.4.22 Cloudflare Inc.
- 6.4.23 Salesforce.com Inc.
- 6.4.24 Alteryx Inc.
- 6.4.25 Cloudera Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


