|
시장보고서
상품코드
2123439
가금류 포장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Poultry Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
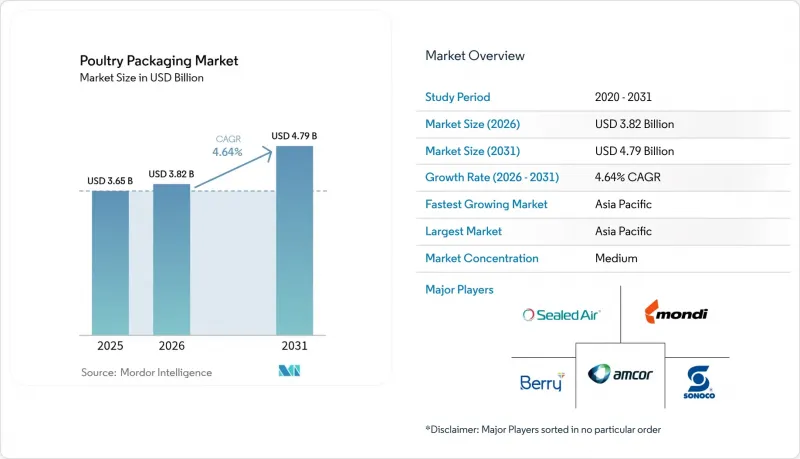
에 의하면, 가금류 포장 시장 규모는 2025년 36억 5,000만 달러에서 2026년에는 38억 2,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 4.64%로 성장을 지속하여, 2031년에는 47억 9,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 육류 유형(닭고기, 칠면조, 오리), 포장 형태(고정형/경질, 유연형),포장재(플라스틱, 종이 및 판지, 금속), 포장 기술(가스 치환 포장, 진공 스킨 포장 등), 유통 채널(소매, 외식 산업/호레카, 산업·기관용), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 가금류 포장 시장 동향 및 인사이트
편의성이 높은 제품 및 바로 조리 가능한 가금류에 대한 수요 증가
밀레니얼 세대 및 Z세대 소비자들은 쉽게 떼어낼 수 있는 트레이나 오븐용 파우치에 담겨 있어 빠르고 간편하게 먹을 수 있는 가금류 요리를 선호합니다. 이에 따라 주요 소매업체들은 매장 내 업무 부담을 줄이고 제품의 품질 안정성을 향상시키는 통합된 ‘케이스 레디’ 프로그램을 지정하고 있습니다. 트레이 제조업체들은 현재 신선도를 며칠간 연장해 주는 흡수 패드와 가스 주입 밸브를 트레이에 통합하고 있습니다. G.Mondini와 같은 설비 공급업체들은 정밀한 분량 조절과 얇은 필름 두께를 동시에 실현한 모듈식 생산 라인을 공급함으로써, 외관의 매력을 해치지 않으면서도 재료 사용량을 줄이고 있습니다. 외식 체인점들도 이러한 변화에 발맞추어, 미리 양념된 진공 스킨 팩을 주문함으로써 냉장 진열대에서 그릴로 한 번에 옮길 수 있도록 하고 있습니다. 프리미엄 밀키트 플랫폼 역시 유사한 포장을 활용하여 운송 중 유통 기한을 연장하고, 필름 비용 상승분을 상쇄할 수 있는 높은 이익률을 확보하고 있습니다.
MAP 및 진공 스킨 기술의 급증
가스 치환 포장은 미생물의 증식을 늦춤으로써 유통 기한을 연장하지만, 초기 고산소 혼합 가스는 지질의 산화 및 색상 변화를 가속화했습니다. 현재 각 컨버터 업체들은 안전상의 우려를 일으키지 않으면서 블룸 현상을 안정화시키는 일산화탄소 첨가제에 대한 시험을 진행하고 있습니다. Duropac 등의 기업이 제공하는 진공 스킨 필름은 가스 누출을 방지하고 천공에도 견디기 때문에 뼈가 붙은 고기에 최적입니다. 포장 내부에서 오존을 발생시키는 플라즈마 처리 트레이는 화학 약품을 사용하지 않고도 캄필로박터를 90%, 살모넬라를 60% 감소시킵니다. MULTIVAC과 같은 장비 제조업체들은 MAP 밸브와 미세 천공 뚜껑을 결합하여, 가공업체가 각 SKU에 맞추어 가스 비율을 조정할 수 있도록 하고 있습니다.
조류 인플루엔자로 인한 공급 차질
2024년부터 2025년까지 발생한 고병원성 조류 인플루엔자(HPAI) 유행으로 인해 수백만 마리의 가금류가 공급망에서 사라졌고, 생산 일정에 차질이 생기며 중량 등급별 트레이 수요에도 변화가 발생했습니다. 미국 농무부(USDA)는 18억 달러를 보상금으로 지출했으나, 양계장의 재사육에는 최대 24주가 소요되기 때문에 공급량 불안정 상태가 장기화되고 있습니다. 워싱턴 대학교가 개발한 고속 바이오센서를 통해 H5N1 바이러스를 5분 만에 검출할 수 있게 되어, 조기 봉쇄 조치와 표적을 좁힌 살처분이 가능해졌습니다. 가금류 사육 주기의 단축으로 인해 가공업체들은 보다 유연한 규모의 주문 및 브랜드 구성 조정을 강요받고 있으며, 이는 다시 컨버터의 생산 로트 계획에 영향을 미치고 있습니다.
부문 분석
닭고기 부문은 소비자들의 폭넓은 수용과 효율화된 뼈 제거 라인 덕분에 가금류 포장 시장의 65.34%를 차지하고 있습니다. 높은 처리 능력 덕분에 가공업체들은 필름 가격을 협상할 수 있게 되었으며, 식품 폐기물을 줄이는 ‘떼어내고 다시 밀봉할 수 있는 뚜껑’에 대한 실험을 촉진하고 있습니다. 오리는 시장 규모는 작지만, 고급 소매점들이 세련된 진공 스킨 포장 트레이에 담긴 분량 조절된 가슴살을 도입함에 따라 연평균 성장률(CAGR) 5.45%로 성장하고 있습니다. 여기서 이색적인 단백질 공급원이 일반 냉동 식품 시장에 침투함에 따라, 오리를 위한 가금류 포장 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 암콜(Amcor)사의 차단 성능이 강화된 봉지는 기름이 스며나오는 것을 방지하고 살코기의 색상을 유지함으로써 프리미엄 상품 진열 기준을 충족하고 있습니다.
오리 고기의 부상으로 인해 각 가공업체들은 소매에서의 어필력을 높이는 투명성을 유지하면서 내유성 코팅을 통합해야 할 필요가 있습니다. 현재 자동화를 통해 오리 고기는 중량 사양에 따라 분량이 조절되어, 닭고기와 마찬가지로 ‘케이스 레디(매장에 진열할 준비가 된 상태)’로 출시될 수 있게 되었습니다. 칠면조는 계절 한정 통조리 제품으로 시장 점유율을 유지하고 있지만, 부가가치가 높은 로스트나 미리 슬라이스된 델리 팩이 연중 수요를 뒷받침하고 있습니다. 따라서 각 단백질 제품에는 개별적인 차단성, 내천자성, 형태가 요구되며, 필름 공급업체들은 SKU 수를 늘리지 않고도 제품 라인업을 확충하도록 장려받고 있습니다.
2025년에는 유연한 구조의 포장이 가금류 포장 시장의 62.45%를 차지하며, 이는 재료 사용량 감소와 매장에서의 존재감을 높이는 고품질 그래픽 디자인에 힘입은 결과입니다. 이러한 형태는 앞으로도 성장의 견인차 역할을 계속할 것이며, 단층 PET 및 PE 라미네이트가 매장에서 재활용이 가능해짐에 따라 매년 5.27%의 성장률이 예상됩니다. 가금류 포장 시장 전체에서 경질 트레이는 프리미엄 오븐 조리용 SKU 및 적재 안정성이 요구되는 통닭 진열에 있어 여전히 중요한 역할을 하고 있습니다.
GEA사의 ‘PowerPak 1000’과 같은 설비를 통해 중규모 공장에서는 단일 프레임에서 진공포장, MAP(수정 대기 포장), 스킨 팩 등 각 방식을 전환할 수 있게 되어, 전환에 따른 가동 중단 시간을 줄일 수 있습니다. 현재 플렉서블 파우치에는 pH가 상승하면 색이 변하는 신선도 센서가 내장되어 있어, 포장재 자체가 품질 모니터링 역할을 수행하고 있습니다. 이러한 개선을 통해 비용에 민감한 단백질 식품 카테고리에서 가격대를 유지하는 동시에, 손실 감소를 위해 유통기한 연장을 요구하는 소매업체의 요구에도 부응하고 있습니다.
지역별 분석
아시아태평양은 2025년에 가금류 포장 시장의 38.45%를 차지하며, 2031년까지 연평균 성장률(CAGR) 5.11%로 확대될 것으로 전망됩니다. 중국과 인도에서 급속한 도시 인구 이동과 가처분 소득 증가가 냉장 가금류 수요를 끌어올리고 있는 반면, 태국은 수출에서의 입지를 강화하고 있습니다. 각국의 순환 경제 관련 규제로 인해 재활용 가능한 라미네이트 소재의 채택이 촉진되고 있으며, 현지 가공업체들은 수출 위생 기준을 충족하기 위해 전 세계 기계 제조업체들과 제휴하고 있습니다. 인도네시아와 베트남에 진출하는 다국적 소매업체들은 ‘케이스 레디(매장에 진열 가능한 상태)’ 프로그램을 지정하고 있으며, 이로 인해 지역 가공업체들에게 새로운 비즈니스 기회가 창출되고 있습니다.
북미는 시장 규모에서 2위를 차지하고 있습니다. 연방 규제는 안정적이지만, 캘리포니아주나 오리건주 등 일부 주에서는 단일 소재 포장을 장려하는 생산자 책임 제도에 기반한 수수료가 도입되었습니다. 소비자들은 항생제 미사용 및 지속가능성 인증을 받은 포장에 대해 높은 지불 의향을 보이고 있으며, 이에 따라 각 브랜드는 퇴비화 가능한 트레이의 시범 도입을 추진하고 있습니다. 캐나다의 개정된 ‘제로 플라스틱 폐기물(Zero Plastic Waste)’ 의제는 EU의 목표와 발을 맞추며, 종이와 폴리머의 하이브리드 소재로의 전환을 더욱 가속화하고 있습니다. 대형 유통업체들이 추적성을 위한 포장재 QR 코드를 시범 도입하고 있어, 스마트 라벨의 채택이 조기에 진행되고 있습니다.
유럽에서는 표면적인 성장률은 낮지만, 혁신의 밀도가 높은 상황입니다. 규정 2025/40에 따라 2030년까지 100% 재활용 가능성이 의무화되었고, PFAS가 금지됨에 따라 가공업체들은 급속한 소재 교체를 강요받고 있습니다. 소매업체들은 공급업체와 협력하여, Coveris사의 신제품 ‘BarrierFresh’ 시리즈에서 볼 수 있듯이, 닭고기를 21일간 신선하게 유지하는 완전 섬유제 트레이의 유효성을 검증하고 있습니다. 독일에서는 스마트 센서를 활용한 실증 실험을 통해 온도 및 시간 관리 미흡 사항을 추적하고, 해당 데이터를 바탕으로 동적인 가격 할인을 실시함으로써 폐기물 감축을 도모하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 동향
JHS 26.09.09According to Mordor Intelligence, the poultry packaging market size is expected to grow from USD 3.65 billion in 2025 to USD 3.82 billion in 2026 and is forecast to reach USD 4.79 billion by 2031 at 4.64% CAGR over 2026-2031.
This report is Segmented by Meat Type (Chicken, Turkey, Duck), Packaging Format (Fixed/Rigid, Flexible), Packaging Material (Plastics, Paper and Paperboard, Metals), Packaging Technology (Modified Atmosphere Packaging, Vacuum Skin Packaging, and More), Distribution Channel (Retail, Foodservice/HORECA, Industrial and Institutional), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Poultry Packaging Market Trends and Insights
Rising Demand for Convenience and Case-Ready Poultry
Millennial and Generation Z shoppers favor quick, no-mess poultry meals that arrive in easy-peel trays or ovenable pouches. Large retailers therefore specify centralized case-ready programs that cut in-store labor and improve product consistency. Tray producers now integrate absorbent pads and gas-flush valves that extend freshness by several days. Equipment vendors such as G.Mondini supply modular lines that blend precise portioning with lower film gauge, trimming material use without sacrificing visual appeal. Foodservice chains mirror this shift by ordering pre-marinated, vacuum-skin packs that move from cooler to grill in one step. Premium meal-kit platforms exploit the same packaging to boost shelf life during shipping, capturing higher margins that offset advanced film costs.
Surge in MAP and Vacuum-Skin Technologies
Modified-atmosphere packaging improves shelf life by slowing microbial growth, yet early high-oxygen blends accelerated lipid oxidation and color shifts. Converters now trial carbon-monoxide adjuncts that stabilize bloom without raising safety concerns. Vacuum-skin films from firms like Duropac prevent purge and withstand puncture, making them attractive for bone-in cuts. Plasma-treated trays that create in-pack ozone cut Campylobacter by 90% and Salmonella by 60% without chemicals. Equipment makers such as MULTIVAC pair MAP valves with micro-perforated lids so processors can tune gas ratios to each SKU.
Avian-Influenza Supply Disruptions
The 2024-2025 HPAI wave removed millions of birds from supply chains, unsettling production schedules and altering tray demand by weight class. USDA spent USD 1.8 billion on indemnities, but barns need up to 24 weeks to repopulate, prolonging volume instability. Rapid biosensors from Washington University now detect H5N1 in five minutes, enabling earlier lockdowns and targeted culls. Shorter flock cycles force processors to order more flexible sizes and adjust brand mix, which in turn influences run-length planning for converters.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Bio-Based and Recyclable Materials
- E-Commerce Cold-Chain Expansion
- Stringent Food-Contact Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The chicken category owns 65.34% of the poultry packaging market, thanks to broad consumer acceptance and streamlined deboning lines. High throughput lets processors negotiate film cost and spur experimentation with peel-reseal lids that cut food waste. Duck, despite its modest base, grows at a 5.45% CAGR as upscale retailers introduce portion-controlled breasts in sleek vacuum-skin trays. Here, the poultry packaging market size for duck is forecast to climb steadily as exotic proteins move into mainstream freezers. Enhanced barrier bags from Amcor prevent grease migration and preserve dark-meat color, meeting premium presentation standards.
Duck's rise compels converters to integrate oil-resistant coatings while keeping clarity for retail appeal. Automation now portions duck to weight specs, enabling case-ready rollouts similar to chicken. Turkey holds share through seasonal whole-bird formats, yet value-added roasts and sliced deli packs sustain year-round demand. Each protein therefore demands tailored barrier, puncture strength, and silhouette, nudging film suppliers to broaden portfolios without inflating SKU count.
Flexible structures delivered 62.45% of the poultry packaging market in 2025, supported by lower material intensity and high graphics that elevate shelf presence. The format will remain the growth leader, advancing 5.27% each year as mono-PET and PE laminates become store-drop recyclable. Within the poultry packaging market size, rigid trays retain roles in premium oven-ready SKUs and whole-bird presentations that benefit from stacking stability.
Equipment such as GEA's PowerPak 1000 lets mid-scale plants swing between vacuum, MAP, and skin variants on a single frame, cutting change-over downtime . Flexible pouches now embed freshness sensors that change color when pH rises, turning the wrapper into a quality monitor. These upgrades defend price points in a cost-sensitive protein category and satisfy retailers that push for longer coded life to lower shrink.
Complete Report Scope:
- By Meat Type
- Chicken
- Turkey
- Duck
- By Packaging Format
- Fixed / Rigid
- Flexible
- By Packaging Material
- Plastics
- Paper and Paperboard
- Metals
- By Packaging Technology
- Modified Atmosphere Packaging (MAP)
- Vacuum Skin Packaging (VSP)
- Active and Intelligent Packaging
- High-Pressure and Others
- By Distribution Channel
- Retail
- Foodservice / HORECA
- Industrial and Institutional
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific controlled 38.45% of the poultry packaging market in 2025 and is projected to expand at a 5.11% CAGR to 2031. Rapid urban migration and rising disposable income in China and India lift chilled-poultry demand, while Thailand strengthens its export position. National circular-economy rules spur adoption of recyclable laminates, and local processors engage global machinery firms to meet export hygiene codes. Multinational retailers entering Indonesia and Vietnam specify case-ready programs, unlocking new business for regional converters.
North America ranks second in value. Federal regulation remains stable, but states such as California and Oregon add producer-responsibility fees that reward mono-material formats . Consumers display strong willingness to pay for antibiotic-free and sustainability-certified packs, encouraging brands to pilot compostable trays. Canada's updated Zero Plastic Waste agenda echoes EU targets, further accelerating the shift to paper-polymer hybrids. Intelligent labels see early uptake as big-box stores test on-pack QR codes for traceability.
Europe shows low headline growth yet high innovation density. Regulation 2025/40 enforces 100% recyclability by 2030 and bans PFAS, forcing converters into rapid material substitution. Retailers collaborate with suppliers to validate fully fiber trays that keep poultry fresh for 21 days, exemplified by Coveris' new BarrierFresh line. Smart-sensor pilots in Germany track time-temperature abuse, delivering data that informs dynamic discounting to curb waste.
- Amcor plc
- Berry Global Group Inc.
- Mondi plc
- Sealed Air Corporation
- Sonoco Products Company
- ProAmpac Holdings LLC
- UFlex Limited
- Huhtamaki Oyj
- Winpak Ltd.
- Glenroy Inc.
- LINPAC SEALPAC International BV
- Coveris Holding SA
- Smurfit Kappa Group plc
- Klockner Pentaplast GmbH
- Cascades Inc.
- DS Smith plc
- Printpack Inc.
- Graphic Packaging Holding Company
- Innovia Films Ltd.
- Flexopack SA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Market Definition and Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for convenience and case-ready poultry
- 4.2.2 Surge in MAP and vacuum-skin technologies
- 4.2.3 Shift toward bio-based and recyclable materials
- 4.2.4 E-commerce cold-chain expansion
- 4.2.5 Adoption of intelligent freshness sensors
- 4.2.6 Recycled-content mandates in key markets
- 4.3 Market Restraints
- 4.3.1 Avian-influenza supply disruptions
- 4.3.2 Stringent food-contact compliance costs
- 4.3.3 Feedstock-price volatility for polyolefins
- 4.3.4 Consumer skepticism of high-O2 MAP
- 4.4 Value / Supply-Chain Analysis
- 4.5 Evaluation of Critical Regulatory Framework
- 4.6 Impact Assessment of Key Stakeholders
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Meat Type
- 5.1.1 Chicken
- 5.1.2 Turkey
- 5.1.3 Duck
- 5.2 By Packaging Format
- 5.2.1 Fixed / Rigid
- 5.2.2 Flexible
- 5.3 By Packaging Material
- 5.3.1 Plastics
- 5.3.2 Paper and Paperboard
- 5.3.3 Metals
- 5.4 By Packaging Technology
- 5.4.1 Modified Atmosphere Packaging (MAP)
- 5.4.2 Vacuum Skin Packaging (VSP)
- 5.4.3 Active and Intelligent Packaging
- 5.4.4 High-Pressure and Others
- 5.5 By Distribution Channel
- 5.5.1 Retail
- 5.5.2 Foodservice / HORECA
- 5.5.3 Industrial and Institutional
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Berry Global Group Inc.
- 6.4.3 Mondi plc
- 6.4.4 Sealed Air Corporation
- 6.4.5 Sonoco Products Company
- 6.4.6 ProAmpac Holdings LLC
- 6.4.7 UFlex Limited
- 6.4.8 Huhtamaki Oyj
- 6.4.9 Winpak Ltd.
- 6.4.10 Glenroy Inc.
- 6.4.11 LINPAC SEALPAC International BV
- 6.4.12 Coveris Holding SA
- 6.4.13 Smurfit Kappa Group plc
- 6.4.14 Klockner Pentaplast GmbH
- 6.4.15 Cascades Inc.
- 6.4.16 DS Smith plc
- 6.4.17 Printpack Inc.
- 6.4.18 Graphic Packaging Holding Company
- 6.4.19 Innovia Films Ltd.
- 6.4.20 Flexopack SA
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-need Assessment