|
시장보고서
상품코드
2123443
미국의 자동차 애프터마켓 부품 및 컴포넌트 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Aftermarket Automotive Parts And Components - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
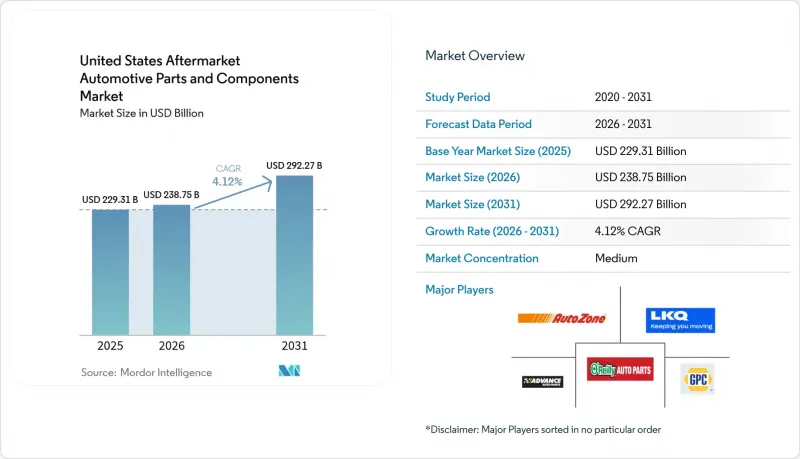
에 의하면, 미국 자동차 애프터마켓 부품 및 컴포넌트 시장 규모는 2025년 2,293억 1,000만 달러에서 2026년에는 2,387억 5,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 4.12%로 성장을 지속하여, 2031년에는 2,922억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 차량 유형별(승용차, 소형 상용차 등),부품별(엔진 부품, 변속기 및 구동계 등), 판매 채널별(온라인 및 오프라인), 추진 방식별(내연기관 차량 등), 서비스 채널별(DIY, DIFM 독립 정비 공장 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국 자동차 애프터마켓 부품 및 컴포넌트 시장 동향 및 인사이트
대형 SUV 및 픽업 트럭으로의 전환이 소모성 부품 매출을 끌어올리고 있습니다.
소형 트럭은 자동차 시장을 휩쓸 기세로, 2027년까지 신차 판매에서 상당한 점유율을 차지할 전망입니다. 이러한 견고한 차량은 특유의 요구 사항과 성능을 반영하여 기존 승용차에 비해 애프터마켓 지출액이 더 높습니다. 이 트럭을 구성하는 부품, 즉 서스펜션, 브레이크, 드라이브트레인 부품은 견인 및 적재하는 무거운 화물로 인해 상당히 큰 하중을 견뎌야 합니다.
오버랜딩, 트레일러 견인, 아웃도어 어드벤처와 같은 라이프스타일 트렌드가 인기를 끌면서, 성능을 향상시키는 업그레이드에 대한 수요도 높아지고 있습니다. 애호가들은 운전 경험을 개선하고 험한 지형에도 대처하기 위해 리프트 키트, 헤비 듀티 쇼크, 초대형 타이어 등을 찾고 있습니다. 픽업 트럭 전용 장비 시장 규모는 이미 연간 160억 달러라는 경이로운 수준에 달했으며, 각 제조업체들은 이러한 다목적 차량을 위한 전용 제품 라인을 전개하고 있습니다.
경트럭 소유주들은 커스터마이징에 열정을 쏟는 경우가 많아, 그 결과 업그레이드 평균 거래액은 표준 교체 부품의 거래액을 자주 상회합니다. 이러한 추세는 트럭의 외관과 기능성을 향상시킬 뿐만 아니라, 자동차 애프터마켓 부품 업계 전체의 이익률을 끌어올리며, 무한한 가능성을 지닌 활기찬 시장을 보여주고 있습니다.
전자상거래의 확산이 롱테일 SKU의 접근성을 가속화
현재 애프터마켓 거래의 대부분은 역동적인 디지털 채널을 통해 이루어지고 있으며, 그 비율은 미국 소매 전자상거래 보급률을 훨씬 웃돌고 있습니다. 이러한 놀라운 변화로 인해 온라인 스토어는 기존의 오프라인 도매업체가 직면하는 재고 관리 부담 없이 전문적인 SKU를 취급할 수 있게 되었습니다. 그 결과, 빈티지 모델용 구하기 어려운 부품을 전국 어디서나 손쉽게 공급할 수 있게 되어 애호가와 수집가의 요구를 충족시키고 있습니다. 드롭쉬핑을 통한 물류와 실시간 재고 데이터 덕분에 DIY 애호가 및 소규모 정비소를 위한 리드타임이 단축되었으며, 시장 내 영향력은 디지털에 정통한 공급업체로 이동하고 있습니다. 그러나 위조품의 유입은 여전히 심각한 위험 요소이며, 연방 정부의 단속 조치는 브랜드 보호 프로그램의 중요성을 부각시키고 있습니다. 견고한 진위 확인 기술과 사용자 친화적인 인터페이스를 결합한 기업들은 계속 확대되는 디지털 애프터마켓에서 타의 추종을 불허하는 시장 점유율을 확보하고 있습니다.
ADAS가 충돌 관련 부품의 판매량을 감소시키고 있다.
자동 긴급 제동 및 차선 유지 시스템 덕분에 사고율이 낮아지면서 범퍼, 펜더, 램프 등에 대한 수요가 감소하고 있습니다. ADAS 보급률이 가장 높은 최신형 고급차에서 충돌 빈도 감소가 가장 두드러지며, 외장 부품의 판매량이 줄어들고 있습니다. 이러한 감소를 상쇄하듯, ADAS 탑재 차량의 수리 시 센서 보정이 필수적이고 작업 시간이 길어짐에 따라 수리 청구액이 높아지고 있습니다. 손상된 카메라나 레이더 모듈의 교체는 전문 전자기기 하위 부문의 성장을 가속하고 있습니다. 충돌 수리 센터는 기술력 향상을 도모하며 첨단 스캔 툴에 대한 투자를 확대하고 있으며, 이에 따라 OE 등급의 센서나 교정 지그를 제공하는 부품 공급업체들이 혜택을 보고 있습니다.
부문 분석
2025년, 승용차는 광범위한 보급 대수를 배경으로 미국 자동차 애프터마켓 부품 및 컴포넌트 시장 전체 매출의 52.74%를 차지했습니다. 그럼에도 불구하고, 상용 경트럭은 연평균 성장률(CAGR) 7.05%를 나타낼 것으로 예측되며, 소포 배송 및 서비스용 차량의 일일 주행 거리가 증가함에 따라 애프터마켓 자동차 부품 시장 규모에 대한 기여도가 높아질 것으로 전망됩니다. 가혹한 가동 주기와 엄격한 가동률 요건이 결합되어 브레이크 어셈블리, 구동계 조인트 및 냉각 부품의 교체 빈도가 증가하고 있습니다. 차량 운영사의 조달 관행은 신속한 공급과 효율적인 보증 절차를 보장하는 공급업체를 우선시하기 때문에 부품 제조업체들은 창고 수준의 재고 관리 및 예측형 주문 처리 시스템 도입으로 나아가고 있습니다.
중형 및 대형 트럭은 판매 대수는 적지만 개별 부품의 단가가 높고 가동 중단으로 인한 손실도 크기 때문에 경제적 가치가 매우 높습니다. EPA의 2027년 배기가스 규제로 인해 선택적 촉매 환원(SCR) 시스템 및 미립자 필터의 선제적 구매와 애프터마켓에서의 사후 장착이 촉진되어 대형 트럭 수요가 일시적으로 증가하고 있습니다. 이번에 예측에서 새롭게 분류된 버스 및 장거리 버스는 대용량 열 관리 제품 및 서스펜션 제품을 전문으로 하는 공급업체에게 부수적인 비즈니스 기회를 열어주고 있습니다. 승용차 부문은 여전히 중요한 위치를 차지하고 있지만, 하이브리드 근무 방식이 보편화되는 시대에 각 가정이 여러 대의 차량 보유 필요성을 재고함에 따라 판매 대수는 정체 상태에 있습니다. 한편, 플릿 차량은 물류 확대에 연동된 성장 궤도에 오른 것으로 보입니다.
2025년, 미국 자동차 애프터마켓 부품 및 컴포넌트 시장에서 엔진 부품은 31.45%의 점유율을 유지하고 있으며, 이는 여전히 지배적인 내연기관(ICE) 보유 대수를 반영하고 있습니다. 그러나 ADAS 센서는 연평균 성장률(CAGR) 7.52%가 예상되며, 가치의 중심이 기계적 요소에서 전자적 요소로 이동하고 있음을 시사합니다. 카메라 모듈, 레이더 유닛, 제어용 ECU는 경미한 충돌로 고장이 나거나 환경 오염 물질의 영향을 받는 경우가 많아, 높은 수익률을 보이는 교체 주기를 만들어내고 있습니다. 콘티넨탈이 2024년에 700종의 새로운 엔진 관리용 SKU를 출시한 것은 공급업체가 기계 분야의 강점을 지키면서 전자기기 포트폴리오를 확대하는 이중 전략(두 가지 축)을 취하고 있음을 보여줍니다.
서스펜션, 브레이크, 타이어 각 카테고리에서는 SUV와 픽업트럭의 대형화 추세에 따라 수요가 지속적으로 증가하고 있습니다. 운전자가 커넥티비티 업그레이드와 OTA 기능을 요구함에 따라 전기 시스템 및 인포테인먼트 하위 부문이 확대되고 있으며, 애프터마켓 하드웨어와 소프트웨어 서비스의 경계가 모호해지고 있습니다. 차체 및 외장 부품은 장단점이 공존하는 상황입니다. ADAS 덕분에 충돌 빈도는 감소하고 있지만, 개인화 문화와 지역별 기후로 인한 손상으로 인해 기본적인 수요는 유지되고 있습니다. 독립 정비소가 소프트웨어 중심의 복잡한 차량 시스템에 대한 정비 체계를 구축함에 따라, 공구, 진단 장비 및 정비용 소모품에 대한 수요가 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the United States aftermarket automotive parts and components market size is expected to grow from USD 229.31 billion in 2025 to USD 238.75 billion in 2026 and is forecast to reach USD 292.27 billion by 2031 at 4.12% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Component Type (Engine Components, Transmission and Driveline, and More), Sales Channel (Online and Offline), Propulsion Type (ICE Vehicles, and More), and by Service Channel (DIY, DIFM Independent Garages, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Aftermarket Automotive Parts And Components Market Trends and Insights
Shift to Larger SUVs and Pickups Raises Wear-Part Revenues
Light trucks are poised to take the automotive market by storm, likely capturing a substantial share of new-vehicle sales by 2027. Each of these robust vehicles commands a higher aftermarket expenditure compared to traditional passenger cars, reflecting their unique demands and capabilities. The components that comprise these trucks, suspension, braking, and drivetrain parts, must endure considerably greater stress due to the hefty loads they tow and carry.
As lifestyle trends like overlanding, trailering, and outdoor adventures gain popularity, the appetite for performance-enhancing upgrades swells. Enthusiasts are seeking out lift kits, heavy-duty shocks, and oversized tires to elevate their driving experiences and tackle rugged terrains. The market for specialty equipment tailored to pickups has already surpassed an impressive USD 16 billion annually, prompting manufacturers to roll out dedicated product lines for these versatile vehicles.
Light-truck owners are often passionate about customization, leading to an average transaction value for upgrades that frequently eclipses that of standard replacements. This trend not only enhances the aesthetics and functionality of their trucks but also elevates profit margins across the aftermarket automotive parts sector, signaling a thriving market with boundless potential.
E-Commerce Penetration Accelerates Long-Tail SKU Availability
The vast majority of aftermarket transactions now traverse the dynamic landscape of digital channels, far surpassing the overall adoption of retail e-commerce across the United States. This remarkable shift allows online storefronts to showcase specialized SKUs without the burdensome costs of inventory that traditional brick-and-mortar wholesalers encounter. As a result, they can effortlessly provide nationwide access to hard-to-find parts for vintage models, catering to enthusiasts and collectors alike. Drop-shipment logistics and real-time inventory data reduce lead times for DIYers and small garages, redistributing market power toward digitally savvy suppliers. Yet counterfeit inflow remains an acute risk; federal enforcement actions underscore the importance of brand-protection programs . Firms that combine robust authentication technology with user-friendly interfaces are capturing a disproportionate share of the expanding digital aftermarket.
ADAS Lowers Collision-Part Volumes
Automatic emergency braking and lane-keeping systems are cutting crash rates, trimming demand for bumpers, fenders, and lamps. Collision frequency declines most among late-model premium vehicles, where ADAS penetration is highest, compressing volumes for cosmetic body parts. Offsetting this decline, repairs on ADAS-equipped vehicles command higher invoice values due to mandatory sensor calibration and longer labor hours. Replacement of damaged cameras or radar modules fosters growth in specialized electronics sub-segments. Collision-repair centers are upskilling and investing in advanced scan tools, benefiting parts suppliers that offer OE-grade sensors and calibration fixtures.
Other drivers and restraints analyzed in the detailed report include:
- Electrified Retrofit Kits Open High-Margin Specialty Niches
- Post-Pandemic Rebound in Vehicle Miles Traveled Lifts Service Frequency
- OEM "Service-as-Software" Subscriptions Cannibalize Hardware Sales
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars accounted for 52.74% of the United States Aftermarket Automotive Parts and Components Market overall revenue in 2025, anchored through an expansive installed base. Nevertheless, commercial light trucks are projected to post a 7.05% CAGR, elevating their contribution to the aftermarket automotive parts market size as parcel delivery and service fleets log higher daily mileage. Combining intensive duty cycles and stringent uptime requirements lifts replacement frequency for brake assemblies, driveline joints, and cooling components. Fleet operators' procurement practices favor suppliers that guarantee rapid availability and streamlined warranty processes, nudging parts makers toward depot-level inventory and predictive fulfillment systems.
Medium and heavy trucks yield outsized monetary value, while smaller in volume, because individual components carry higher price tags and downtime penalties. EPA 2027 emissions rules motivate prebuy activity and aftermarket retrofits of selective catalytic reduction and particulate filters, temporarily boosting heavy-duty demand. Buses and coaches, newly segmented in the forecast, open ancillary potential for specialist providers of high-capacity thermal-management and suspension products. Passenger-car segments remain relevant but confront a plateauing unit base as households question the need for multiple vehicles in the era of hybrid work, whereas fleet vehicles appear locked into growth trajectories tied to logistics expansion.
Engine components retained 31.45% of the United States Aftermarket Automotive Parts and Components Market in 2025, mirroring the still-dominant ICE parc. Yet ADAS sensors are forecast for a 7.52% CAGR, signaling the pivot from mechanical to electronic value. Camera modules, radar units, and control ECUs often fail in minor collisions or succumb to environmental contaminants, creating high-margin replacement cycles. Continental's 2024 launch of 700 new engine-management SKUs illustrates suppliers' dual strategy of defending mechanical strongholds while scaling electronics portfolios.
Suspension, brake, and tire categories see ongoing lift from the trend toward heavier SUVs and pickups. Electrical and infotainment sub-segments increase as drivers seek connectivity upgrades and over-the-air functionality, blurring the line between aftermarket hardware and software services. Body and exterior parts face mixed fortunes: ADAS reduces collision frequency, yet personalization culture and regional climate damage sustain baseline demand. Tools, diagnostics, and shop consumables are expanding as independent garages gear up to service complex, software-driven vehicle systems.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (Class 1-3)
- Medium & Heavy Trucks (Class 4-8)
- Buses & Coaches (NEW)
- By Component Type
- Engine Components (filters, gaskets, pistons)
- Transmission & Driveline
- Electrical & Electronics (sensors, alternators, ADAS)
- Suspension & Brakes
- Body & Exterior (bumpers, lighting)
- Tires
- Interior & Accessories
- Fluids & Lubricants
- Others (Seat and Covers, etc.)
- By Sales Channel
- Online
- Offline
- By Propulsion Type
- Internal-Combustion Engine (ICE) Vehicles
- Hybrid Electric Vehicles (HEV)
- Battery Electric Vehicles (BEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Fuel-Cell Electric Vehicles (FCEV)
- By Service Channel
- DIY (Do-It-Yourself)
- DIFM Independent Garages
- Fleet / Commercial Service Providers
List of Companies Covered in this Report:
- Magna International Inc.
- Continental AG
- ZF Friedrichshafen AG
- DENSO Corporation
- Robert Bosch GmbH
- Lear Corporation
- Flex-N-Gate Corporation
- Panasonic Automotive Systems Co. of America
- Aisin World Corp. of America
- American Axle & Manufacturing
- Yazaki North America
- Adient PLC
- Faurecia SE
- Aptiv PLC
- LKQ Corporation
- Advance Auto Parts Inc.
- O'Reilly Automotive Inc.
- AutoZone Inc.
- Genuine Parts Co. (NAPA)
- Tenneco Inc.
- Dana Incorporated
- BorgWarner Inc.
- Goodyear Tire & Rubber Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Light-Vehicle Parc Drives Replacement Demand.
- 4.2.2 Shift To Larger SUVs and Pickups Raises Wear-Part Revenues.
- 4.2.3 E-Commerce Penetration Accelerates Long-Tail SKU Availability.
- 4.2.4 Electrified Retrofit Kits Open High-Margin Specialty Niches.
- 4.2.5 Right-To-Repair Statutes Widen Independent Aftermarket Access.
- 4.2.6 Post-Pandemic Rebound In Vehicle-Miles-Traveled Lifts Service Frequency
- 4.3 Market Restraints
- 4.3.1 EVs Contain 30-40 % Fewer Moving Parts.
- 4.3.2 ADAS Lowers Collision-Part Volumes
- 4.3.3 OE Service-As-Software Subscriptions Cannibalize Hardware Sales.
- 4.3.4 Counterfeit Inflow Via Cross-Border E-Commerce Erodes Brand Share.
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Light Commercial Vehicles (Class 1-3)
- 5.1.3 Medium & Heavy Trucks (Class 4-8)
- 5.1.4 Buses & Coaches (NEW)
- 5.2 By Component Type
- 5.2.1 Engine Components (filters, gaskets, pistons)
- 5.2.2 Transmission & Driveline
- 5.2.3 Electrical & Electronics (sensors, alternators, ADAS)
- 5.2.4 Suspension & Brakes
- 5.2.5 Body & Exterior (bumpers, lighting)
- 5.2.6 Tires
- 5.2.7 Interior & Accessories
- 5.2.8 Fluids & Lubricants
- 5.2.9 Others (Seat and Covers, etc.)
- 5.3 By Sales Channel
- 5.3.1 Online
- 5.3.2 Offline
- 5.4 By Propulsion Type
- 5.4.1 Internal-Combustion Engine (ICE) Vehicles
- 5.4.2 Hybrid Electric Vehicles (HEV)
- 5.4.3 Battery Electric Vehicles (BEV)
- 5.4.4 Plug-in Hybrid Electric Vehicles (PHEV)
- 5.4.5 Fuel-Cell Electric Vehicles (FCEV)
- 5.5 By Service Channel
- 5.5.1 DIY (Do-It-Yourself)
- 5.5.2 DIFM Independent Garages
- 5.5.3 Fleet / Commercial Service Providers
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Magna International Inc.
- 6.4.2 Continental AG
- 6.4.3 ZF Friedrichshafen AG
- 6.4.4 DENSO Corporation
- 6.4.5 Robert Bosch GmbH
- 6.4.6 Lear Corporation
- 6.4.7 Flex-N-Gate Corporation
- 6.4.8 Panasonic Automotive Systems Co. of America
- 6.4.9 Aisin World Corp. of America
- 6.4.10 American Axle & Manufacturing
- 6.4.11 Yazaki North America
- 6.4.12 Adient PLC
- 6.4.13 Faurecia SE
- 6.4.14 Aptiv PLC
- 6.4.15 LKQ Corporation
- 6.4.16 Advance Auto Parts Inc.
- 6.4.17 O'Reilly Automotive Inc.
- 6.4.18 AutoZone Inc.
- 6.4.19 Genuine Parts Co. (NAPA)
- 6.4.20 Tenneco Inc.
- 6.4.21 Dana Incorporated
- 6.4.22 BorgWarner Inc.
- 6.4.23 Goodyear Tire & Rubber Co.