|
시장보고서
상품코드
2123487
잔디 보호 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Turf Protection - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
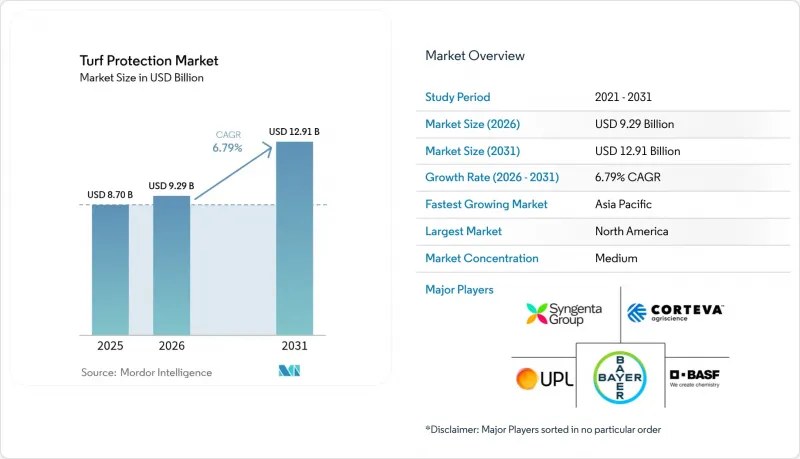
에 의하면, 잔디 보호 시장 규모는 2025년에 87억 달러로 평가되었고 2026년 92억 9,000만 달러에서 2031년까지 129억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.79%를 나타낼 전망입니다.
본 보고서는 제품 유형별(살균제, 제초제 등), 용도별(조경, 골프장, 스포츠 경기장 등), 최종 사용자별(주거용 등), 작용기전별(화학적, 생물학적, 통합 솔루션), 제형별(과립제 등), 지역별(북미, 유럽,아시아태평양 등)별로 분류되어 있습니다. 본 보고서에서는 금액(달러) 기준의 예측을 제시하고 있습니다.
전 세계 잔디 보호 시장 동향 및 인사이트
골프장 및 프로 스포츠 시설 건설 증가
팬데믹 이후, 특히 인도, 중국 및 걸프 국가들에서 신규 시설에 대한 자본 배분이 급증하면서 내구성과 자연스러운 플레이성을 모두 갖춘 하이브리드형 잔디 시스템에 대한 꾸준한 수요가 발생하고 있습니다. 프로 리그에서는 피치 품질에 대한 평가 기준이 공식적으로 제정됨에 따라, 경기장 소유주들은 더욱 엄격한 안전성 테스트를 통과한 살균제, 식물 성장 조절제 및 스트레스 완화 제품을 지정하고 있습니다. 일단 건설되면 각 경기장에서는 시즌 내내 병해 방제가 필요하며, 이는 공급업체에게 지속적인 수익원이 되고 있습니다. 또한 개발업자들은 종자, 영양제, 디지털 모니터링을 한 세트로 묶은 통합 패키지를 선호하여 채택하고 있으며, 이는 잔디 보호 시장에서 교차 판매의 기회를 창출하고 있습니다.
잔디 병해 발생 증가
겨울철 기온 상승과 장기간 지속되는 높은 습도로 인해 돌스팟과 브라운 패치의 발생이 심화되고 있으며, 코스 관리 책임자들은 달력에 기반한 일정 대신 병원체의 위협에 실시간으로 대응하는 동적인 윤작 프로그램을 채택하고 있습니다. 조사에 따르면, 고농도의 질소를 시비한 토울페스크 구역에서는 적정량의 비료를 시비한 잔디에 비해 브라운 패치 발생률이 40% 더 높은 것으로 나타나, 균형 잡힌 영양 관리 전략의 필요성이 부각되고 있습니다. 첨단 진단 키트와 AI 모델을 통해 돌스팟을 97%의 정확도로 감지할 수 있게 되어, 조기 대책 수립과 살균제 사용량의 최적화가 가능해졌습니다. 이러한 추세에 따라 잔디 보호 업계는 유익한 토양 미생물을 보존하는 예측 분석과 부지별 상황에 맞춘 처리를 지향하고 있습니다.
인조잔디 솔루션의 급속한 보급
인조잔디 구장은 정기적인 잔디 깎기나 농약 비용이 필요 없기 때문에 인력과 수자원 제약으로 어려움을 겪는 교육위원회나 지자체들의 관심을 끌고 있습니다. 현재 미국에서는 연간 1,200-1,500건의 설치가 이루어지고 있습니다. 그러나 PFAS 오염 보고와 유럽에서 연간 1만 6,000톤의 미세 플라스틱 배출 추정치를 계기로 정책 재검토가 진행되고 있으며, 이는 인조잔디로의 전환을 주춤하게 하고 천연잔디 대안에 새로운 활력을 불어넣을 가능성이 있습니다. 각 잔디 관리 업체들은 하이브리드 기술 도입과 천연 시스템의 건강 및 지속가능성 측면에서의 이점을 강조하는 홍보 캠페인을 통해 이러한 동향에 대응하고 있습니다.
부문 분석
2025년에는 달러 스팟병, 브라운 패치병, 피시움병에 의한 지속적인 위협을 반영하여, 살균제가 잔디 보호 시장 매출에서 37.50%의 점유율을 차지하며 가장 큰 비중을 차지했습니다. 토너먼트 수준의 잔디를 유지하는 것을 목표로 하는 골프장의 경우, SDHI, QoI, DMI 계열 약제를 조합한 정교한 윤작 계획은 여전히 필수적입니다. 그러나 연평균 성장률(CAGR) 10.81%로 성장을 지속하고, 있는 생물 자극제는 입증된 스트레스 내성과 뿌리 건강 증진 효과를 바탕으로, 지속 가능한 자재로 시장이 전환되고 있음을 여실히 보여줍니다. 관리자들이 일년생 블루그래스나 광엽 잡초를 처리하는 가운데, 제초제는 총 수요에서 큰 비중을 차지하는 반면, 식물 성장 조절제는 잔디 깎기 기계의 연료비와 인건비를 절감함으로써 지지를 얻고 있습니다.
식물 성장 조절제의 잔디 보호 시장 규모는 노동력 부족이 심화되고 지속가능성 목표가 높아짐에 따라 확대될 전망입니다. 철계 대체제 및 미생물 혼합 제제가 기존의 살균제를 보완하게 되어, 환경적 위험을 줄이면서도 달러스팟병 억제 효과 면에서 동등한 성능을 발휘하고 있습니다. 생물 유래 제품과 합성 제품을 결합한 복합 제제가 등장하여 흡수성과 지속성을 높임으로써 코스 관리자의 선택 폭이 넓어지고 있습니다.
조경 분야는 주택 및 상업시설의 외관 미관에 대한 안정적인 지출에 힘입어 2025년에도 전체 수요의 42.10%를 계속 차지했습니다. 제품 구성은 광범위한 잡초 방제, 방출 조절 비료, 그리고 균일한 외관을 구현하는 착색제에 중점을 두고 있습니다. 대조적으로, 스포츠 경기장은 프랜차이즈와 대학이 선수의 안전과 경기장 표면의 균일성을 우선시함에 따라 연평균 성장률(CAGR) 9.36%로 가장 높은 성장률을 기록하고 있습니다. NFL에 의한 경기장 검사 표준화 추진은 이미 조달 사양을 고성능 살균제 프로그램 및 하이브리드 오버시딩 블렌드로 방향을 전환시키고 있습니다.
골프 코스용 잔디 보호 시장 규모는 큰 비중을 차지하고 있지만, 많은 성숙한 코스가 자본 확장에서 개보수 모드로 전환되고 있어 스포츠 경기장에 비해 성장이 정체되어 있습니다. 잔디 농장은 틈새 시장이지만, 철저한 해충 방제가 필요한 병해 없는 잔디를 공급하는 역할을 통해 시장에 영향력을 행사하고 있습니다.
지역별 분석
북미는 2025년, 15,000곳 이상의 골프 코스와 세계 최대 규모의 프로용 경기장군을 기반으로 전 세계 매출의 34.70%를 차지했습니다. 미국은 지역 수요의 약 90%를 차지하고 있으며, IoT 토양 프로브 및 AI 살포 일정 관리 도구의 조기 도입으로 혜택을 보고 있습니다. 캐나다에서는 생육 기간이 짧아 병해 발생이 여름 성수기에 집중되므로, 고품질 살균제 프로그램의 도입이 촉진되고 있습니다. 멕시코의 리조트 지역에서는 해안 토양에서 자라는 내염성 잔디 품종 및 비료 시비 프로그램에 대한 투자가 진행되고 있습니다.
아시아태평양은 세계 최고 수준인 연평균 성장률(CAGR) 8.32%를 나타낼 것으로 예측됩니다. 중국의 연구 기관은 스트레스 내성이 있는 잔디 유전자원 컬렉션을 확대하고 있지만, 코스 운영자들은 여전히 많은 고품질 품종을 수입하고 있습니다. 인도의 도시 지역에서 골프 및 크리켓 인프라가 몬순의 급격한 변화를 견딜 수 있는 살균제 및 생장 조절제 패키지에 대한 견고한 수요를 뒷받침하고 있습니다. 일본의 성숙한 골프 업계에서는 정부의 지속가능성 목표를 달성하기 위해 정밀 관개 및 생물 유래 자재로 전환이 진행되고 있습니다. 호주의 코스 관리자들은 엄격한 물 사용 할당량에 직면해 있으며, 플레이 품질을 유지하기 위해 습윤제나 가뭄에 강한 배합제에 대한 의존도를 높이고 있습니다.
유럽은 여전히 기술과 규제가 주도하는 시장입니다. 유럽연합 집행위원회의 농약 지속 가능한 사용 및 미세 플라스틱 금지 추진은 생물학적 프로그램과 생분해성 캐리어의 도입을 뒷받침하고 있습니다. 독일과 영국은 살균제 살포 시기를 미세하게 조정하는 센서 연동 네트워크 도입을 선도하고 있습니다. 프랑스의 그라운드 관리 팀은 국가의 농약 감축 목표를 준수하기 위해 생물 자극제를 이용한 종자 처리를 조기에 도입함으로써, 정책이 조달 선택에 어떤 영향을 미치는지 보여주고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the turf protection market size was valued at USD 8.7 billion in 2025 and estimated to grow from USD 9.29 billion in 2026 to reach USD 12.91 billion by 2031, at a CAGR of 6.79% during the forecast period (2026-2031).
This report is Segmented by Product Type (Fungicides, Herbicides, and More), Application (Landscaping, Golf Courses, Sports Fields, and More), by End-User (Residential Customers, and More), by Mode of Action (Chemical, Biological, and Integrated Solution), by Formulation (Granular, and More) and Geography (North America, Europe, Asia-Pacific, and More). The Report Offers Forecasts in Terms of Value (USD).
Global Turf Protection Market Trends and Insights
Rising construction of golf courses and professional sports venues
Capital allocations for new facilities surged after the pandemic, particularly across India, China, and Gulf states, creating steady pull-through demand for hybrid turf systems that balance durability with natural playability. Professional leagues have formalized surface-quality metrics, prompting venue owners to specify fungicides, plant growth regulators, and stress-mitigation products that pass stricter safety tests. Once built, each venue requires season-long disease control, anchoring recurring revenue for suppliers. Developers also lean on integrated packages that bundle seed, nutrition, and digital monitoring, opening cross-selling opportunities in the turf protection market.
Increasing incidence of turfgrass diseases
Milder winters and prolonged humidity are intensifying outbreaks of dollar spot and brown patch, prompting superintendents to adopt dynamic rotation programs that respond to real-time pathogen pressure instead of calendar schedules. Research shows tall fescue plots receiving high nitrogen suffer 40% higher brown patch severity than moderately fertilized turf, underscoring the need for balanced nutrition strategies. Advanced diagnostic kits and AI models now detect dollar spot with 97% accuracy, enabling earlier interventions and optimized fungicide loads. The trend is pushing the turf protection industry toward predictive analytics and site-specific treatments that preserve beneficial soil organisms.
Rapid penetration of artificial turf solutions
Synthetic fields eliminate routine mowing and pesticide spending, enticing school boards and municipalities wrestling with labor and water constraints. Installations in the United States now run between 1,200 and 1,500 per year. Nonetheless, PFAS contamination findings and microplastic-shed estimates of 16,000 tons annually in Europe have triggered policy reviews that could stall conversions and breathe life into natural alternatives. Turf protection vendors are responding with hybrid technology and communication campaigns highlighting the health and sustainability benefits of natural systems.
Other drivers and restraints analyzed in the detailed report include:
- Growing residential demand for aesthetic lawns
- Shift toward biological fungicides and biostimulants
- Regulatory pressure on conventional fungicides
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fungicides generated the largest slice of turf protection market revenue with a 37.50% share in 2025, reflecting the continual threat of dollar spot, brown patch, and Pythium. Sophisticated rotation plans mixing SDHI, QoI, and DMI chemistry remain indispensable for courses aiming to maintain tournament-grade surfaces. However, biostimulants, posting an 10.81% CAGR, highlight the market's pivot toward sustainable inputs backed by proven stress tolerance and root health gains. Herbicides hold a prominent share in total demand as managers tackle annual bluegrass and broadleaf weeds, while plant growth regulators find traction by trimming mower fuel and labor costs.
The turf protection market size for plant growth regulators is poised to expand in tandem with heightened labor constraints and sustainability targets. Iron-based alternatives and microbial cocktails now supplement conventional fungicides, demonstrating equivalent dollar spot suppression with lower environmental risk. Biologicals and synthetics are spawning co-formulations that enhance uptake and persistence, broadening choice for superintendents.
Landscaping maintained 42.10% of overall demand in 2025, supported by steady residential and commercial spending on curb appeal. Product mixes focus on broad-spectrum weed control, slow-release nutrition, and colorants that deliver a uniform appearance. In contrast, sports fields are leading the growth table with a 9.36% CAGR, as franchises and universities prioritize athlete safety and surface consistency. The NFL's push for standardized field testing is already shaping purchasing specifications toward high-performance fungicide programs and hybrid overseeding blends.
The turf protection market size dedicated to golf courses holds a significant share, but growth plateaus relative to sports arenas, as many mature courses transition from capital expansion to a renovation mode. Sod farms, while niche, exert influence through their role in supplying disease-free sod that demands intensive pest control.
Complete Report Scope:
- By Product Type
- Fungicides
- Herbicides
- Insecticides
- Plant Growth Regulators
- Biostimulants and Bio-fertilizers
- By Application
- Landscaping
- Golf Courses
- Sports Fields
- Sod Farms
- By End-user
- Residential Customers
- Commercial Landscape Contractors
- Sports Facility Owners
- Municipalities and Schools
- By Mode of Action
- Chemical
- Biological
- Integrated Solutions
- By Formulation
- Granular
- Liquid Concentrate
- Wettable Powder
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of the North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America retained 34.70% of global revenue in 2025, anchored by more than 15,000 golf courses and one of the world's largest portfolios of professional stadiums. The United States represents roughly 90% of regional demand and benefits from the early adoption of IoT soil probes and AI spray scheduling tools. Canada's shorter growing window concentrates disease outbreaks into intense summer peaks, encouraging premium fungicide programs. Mexico's resort corridors channel investment into salt-tolerant turf cultivars and fertility programs that thrive in coastal soils.
Asia-Pacific is projected to clock an 8.32% CAGR, the fastest worldwide. China's research institutes are expanding germplasm collections for stress-resistant turf, but course operators still import many premium cultivars. India's urban golf and cricket infrastructure underpins robust demand for fungicide and growth-regulator packages capable of withstanding monsoon swings. Japan's mature golf scene is pivoting toward precision irrigation and biological inputs to meet government sustainability targets. Australian course managers face stringent water quotas, increasing reliance on wetting agents and drought-resilient blends to safeguard playing quality.
Europe remains a technology- and regulation-driven arena. The European Commission's push for sustainable pesticide use and microplastic bans incentivizes biological programs and biodegradable carriers. Germany and the United Kingdom spearhead the uptake of connected-sensor networks that fine-tune fungicide timing. France's grounds crews are early adopters of biostimulant seed treatments to comply with national pesticide-reduction objectives, showcasing how policy influences procurement choices.
- Syngenta Group
- Bayer AG
- BASF SE
- UPL Limited
- Nufarm Limited
- AMVAC Chemical Corporation
- Sumitomo Group
- Bioceres LLC (Morrone Bio Innovations)
- ICL Group
- FMC Corporation
- Corteva Agriscience
- SePRO Corporation
- Gowan Company, L.L.C.
- Koch Agronomic Services, LLC
- LebanonTurf (Lebanon Seaboard Corporation)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising construction of golf courses and professional sports venues
- 4.2.2 Increasing incidence of turfgrass diseases
- 4.2.3 Growing residential demand for aesthetic lawns
- 4.2.4 Shift toward biological fungicides and biostimulants
- 4.2.5 Adoption of sensor-based precision turf management
- 4.2.6 Climate-change-induced heat-stress mitigation solutions
- 4.3 Market Restraints
- 4.3.1 Rapid penetration of artificial turf solutions
- 4.3.2 High Research and Development cost for novel chemistries
- 4.3.3 Regulatory pressure on conventional fungicides
- 4.3.4 Micro- and nanoplastic pollution concerns from turf inputs
- 4.4 Technological Outlook
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Fungicides
- 5.1.2 Herbicides
- 5.1.3 Insecticides
- 5.1.4 Plant Growth Regulators
- 5.1.5 Biostimulants and Bio-fertilizers
- 5.2 By Application
- 5.2.1 Landscaping
- 5.2.2 Golf Courses
- 5.2.3 Sports Fields
- 5.2.4 Sod Farms
- 5.3 By End-user
- 5.3.1 Residential Customers
- 5.3.2 Commercial Landscape Contractors
- 5.3.3 Sports Facility Owners
- 5.3.4 Municipalities and Schools
- 5.4 By Mode of Action
- 5.4.1 Chemical
- 5.4.2 Biological
- 5.4.3 Integrated Solutions
- 5.5 By Formulation
- 5.5.1 Granular
- 5.5.2 Liquid Concentrate
- 5.5.3 Wettable Powder
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.1.4 Rest of the North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 Australia
- 5.6.4.5 South Korea
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Syngenta Group
- 6.4.2 Bayer AG
- 6.4.3 BASF SE
- 6.4.4 UPL Limited
- 6.4.5 Nufarm Limited
- 6.4.6 AMVAC Chemical Corporation
- 6.4.7 Sumitomo Group
- 6.4.8 Bioceres LLC (Morrone Bio Innovations)
- 6.4.9 ICL Group
- 6.4.10 FMC Corporation
- 6.4.11 Corteva Agriscience
- 6.4.12 SePRO Corporation
- 6.4.13 Gowan Company, L.L.C.
- 6.4.14 Koch Agronomic Services, LLC
- 6.4.15 LebanonTurf (Lebanon Seaboard Corporation)