|
시장보고서
상품코드
2123493
소비자 유전체학 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Consumer Genomics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 소비자 유전체학 시장 규모는 2025년에 23억 9,000만 달러로 평가되었고 2026년 29억 6,000만 달러에서 2031년까지 86억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 23.95%를 나타낼 전망입니다.
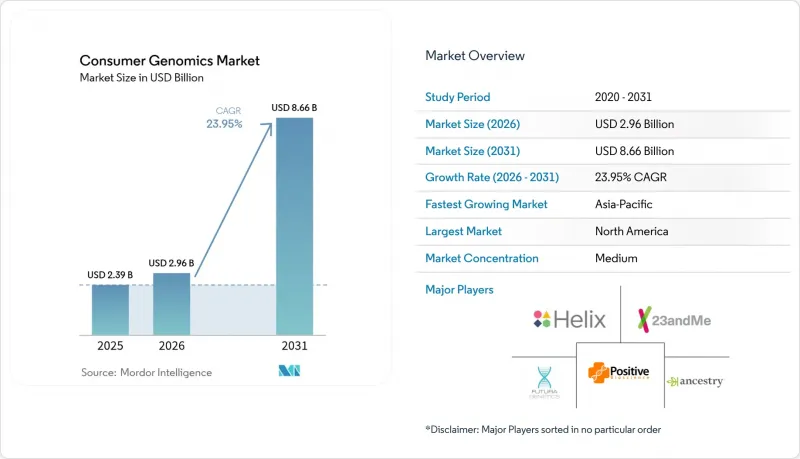
본 보고서는 용도(유전적 친화도, 진단 등), 기술(마이크로어레이·유전자형 분석,SNP 유전형 분석 등), 검체 유형(타액, 구강 점막 면봉 등), 유통 채널(소비자 직접 판매, 의사·클리닉 경유 등), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
전 세계 소비자 대상 유전체학 시장 동향 및 인사이트
DTC 키트에 대한 소비자와 의사의 관심 증가
2023년에는 3,300만 건 이상의 검사가 실시되었으며, 이는 유전체 문해력이 이제 일상적인 건강 관련 의사 결정에 얼마나 큰 영향을 미치고 있는지를 보여줍니다. 의사들은 특히 유전 상담을 통한 해석 지원이 있을 경우, 자가 검사 결과를 예방 의학 상담의 계기로 삼는 경향이 강해지고 있습니다. 데이터를 정확한 식단, 운동, 약물 복용 선택과 연결하고, 조상, 약물 유전학 및 질병 소인을 결합한 서비스에 대한 수요는 소비자의 자기 주도성을 여실히 보여주고 있습니다. 의료 기관에서는 이러한 추세에 대응하여, DTC(소비자 직접 유전자 검사) 파일을 전자 차트에 통합하고 경과에 따른 모니터링을 수행하기 위해 보안 조치가 적용된 포털을 구축하고 있습니다. 이러한 변화는 일회성 검사에서 지속적인 유전체 활용으로의 행동 양식 변화를 뒷받침하고 있습니다.
시퀀싱 비용의 지속적인 하락과 기술의 진보
최초의 인간 유전체 분석에는 30억 달러가 소요되었습니다. 오늘날 전체 유전체 시퀀싱 서비스의 가격은 일반적으로 1,000달러 미만으로, 과거 주류로 확산되는 것을 제한했던 경제적 장벽이 줄어들고 있습니다. 차세대 시퀀서는 더 높은 정확도와 짧은 처리 시간을 실현하여, 신속한 결과를 원하는 소비자의 기대에 부응하는 1주일 이내 결과 제공을 가능하게 하고 있습니다. GeneDx사는 최근 AI 기반 변이 해석 기능을 통합하기 위해 Fabric Genomics사를 5,100만 달러에 인수했습니다. 이번 거래는 대규모 자동 분석에 대한 시장 수요를 여실히 보여주고 있습니다. 이러한 발전은 심혈관 질환, 대사 질환, 종양성 질환을 아우르는 보다 상세한 다유전자 점수로 직접 이어지고 있습니다.
데이터 개인정보 보호 및 사이버 보안 침해
2023년에 발생한 23andMe의 700만 건 프로파일 유출 사건은 유전체 데이터 저장소가 침해되었을 때 신뢰가 얼마나 급속도로 훼손되는지를 여실히 보여주었습니다. 이에 따라 미국 연방거래위원회(FTC)는 감독을 강화하고, 보안 조치를 허위로 표시한 기업이나 고객이 동의를 철회했을 때 원시 데이터 파일을 삭제하지 않은 기업에 대해 벌금을 부과하고 있습니다. 유전정보차별금지법(GINA) 등의 보호 조치가 있음에도 불구하고, 보험 분야에서 유전적 차별에 대한 일반 시민들의 불안은 여전히 심각합니다. 업계 선도 기업들은 현재 회의적인 구매자들을 안심시키기 위해 은행 수준의 암호화, 제로 지식 증명 아키텍처, 정기적인 제3자 감사를 마케팅의 핵심으로 삼고 있습니다.
부문 분석
2025년 매출 중 계보 서비스가 37.85%를 차지하고 있으며, 이는 키트를 처음 구매하는 계층에서 선점 기업의 매력을 보여줍니다. 건강, 영양, 스포츠 성능에 관한 검사의 보급이 진행됨에 따라, 식단 지도, 수면 코칭, 맞춤형 보충제를 통합한 프리미엄 제품을 중심으로 소비자 유전체학 시장 규모가 재편되고 있습니다. 엘리트 선수와 아마추어 선수들이 유전자형에 맞춘 주요 영양소 비율을 추구하는 가운데, 스포츠 영양 검사만으로도 2031년까지 연평균 성장률(CAGR) 28.1%를 기록할 전망입니다. 단일 유전자 질환 진단 패널도 보인자 선별 검사와 실질적인 생식 상담을 결합함으로써 시장 점유율을 확대되고 있습니다. 소비자들은 조상, 형질, 웰니스를 하나의 구독 서비스로 묶은 번들형 서비스를 점점 더 선호하고 있으며, 이는 단일 목적의 계보 키트에 대한 수요가 점차 감소하고 있음을 시사합니다. 모바일 코칭 앱 등 보다 광범위한 디지털 헬스 생태계 내에 검사를 위치시키는 이해관계자들은 일회성 판매에서 지속적인 인사이트 제공으로 진화함으로써 고객 생애 가치를 강화하고 있습니다.
현재 2세대 플랫폼에는 약물 대사 상태를 항응고제, 항우울제, 스타틴 등의 실용적인 투약 조정에 반영하는 약리유전학 모듈이 통합되어 있습니다. 진료소 측에서는 처방 결정에 앞서 이러한 데이터가 전자 차트에 반영됨으로써 약물 부작용이 감소했다고 보고하고 있습니다. 웰니스 및 진단 관련 주장에 대한 규제의 명확화는 기능 설계에 계속 영향을 미치고 있지만, 초기 증거에 따르면 다중 범주 대응 키트는 검사 결과 반환 기간을 연장하지 않으면서도 더 높은 평균 판매 가격을 확보하고 있는 것으로 나타났습니다.
SNP 유전형 분석은 2025년 키트 판매량의 44.12%를 차지하고 있으며, 비용 효율성과 10년에 걸친 정확도 실적을 바탕으로 지지를 받고 있습니다. 그럼에도 불구하고, 보험사의 지원 프로그램을 통해 수십만 개의 변이를 통합하여 복잡한 질환에 대한 연속적인 위험 곡선을 제공하는 다유전자 위험 점수 산정 엔진으로의 전환이 가속화되고 있습니다. 이 하위 부문은 연평균 성장률(CAGR) 31.1%로 확대될 것으로 예상되며, 소비자 유전체학 시장 내의 다른 어떤 기술 스택보다 높은 성장률을 보이고 있습니다. 전체 유전체 시퀀싱은 1,000달러 미만의 가격 전환점을 맞이하고 있으며, 이에 따라 Bupa는 300개 유전자에 걸친 종합적인 검사 범위를 원하는 특정 가입자를 대상으로 유전체 웰니스 패키지의 시범 도입을 시작했습니다. 마이크로어레이는 역사적 참조 라이브러리가 변이 선택과 매끄럽게 매핑되기 때문에 조상 분석에 여전히 유용합니다. 한편, 타겟 시퀀싱 패널은 커버리지 깊이가 중요한 심혈관 질환 및 종양학에 특화된 키트에서 독자적인 틈새 시장을 개척하고 있습니다.
클라우드 파이프라인이 성숙해짐에 따라 원시 데이터의 서열 정렬, 변이 감지, 주석 처리가 며칠이 아닌 몇 시간 만에 완료될 수 있게 되었으며, 공급업체는 며칠 이내의 납기를 약속할 수 있을 만큼의 민첩성을 확보했습니다. 또한, 컨테이너화된 바이오인포매틱스의 성숙으로 인해 소규모 신생 기업도 고가의 On-Premise 인프라를 구축하지 않고도 하이퍼스케일러의 마켓플레이스에서 용량을 대여할 수 있게 되어, 데이터가 풍부한 분야로의 진입이 민주화되고 있습니다.
지역별 분석
북미는 높은 소비자 인지도, 성숙한 디지털 결제 인프라, 그리고 유전체 기반 의사 결정 지원 도구에 대한 임상의들의 숙련도 덕분에 2025년에도 매출의 41.12%를 계속 차지했습니다. 이 지역의 소비자 유전체학 시장 규모는 주별 법규가 명확해지고, 개인정보 보호 및 데이터 소유권을 둘러싼 초기 소송 위험이 완화됨에 따라 계속 확대될 것입니다. 주요 대학들은 키트 공급업체와 빈번하게 제휴하여 연구 코호트를 크라우드소싱하고 있으며, 무료 또는 할인된 가격의 검사를 제공함으로써 참조 데이터베이스에 추가 데이터를 유도하고 있습니다.
연평균 성장률(CAGR) 26.3%로 성장하고 있는 아시아태평양은 주요 성장의 최전선으로 두각을 나타내고 있습니다. 중국, 인도, 동남아시아에서 가처분 소득 증가와 생활습관병 증가가 맞물리면서, 예방적 유전체 위험 평가가 매력적인 가계 지출 항목이 되고 있습니다. 지방 자치 단체는 소비자의 관심을 불러일으키는 국가 유전체 프로젝트에 투자하고 있는 반면, 공급업체들은 언어의 장벽을 극복하기 위해 컨텐츠를 중국어, 힌디어, 인도네시아어로 현지화하고 있습니다. 집에서 타액을 채취하면 대도시 병원의 대기 시간을 피할 수 있어, 바쁜 일정을 소화하는 중산층 가정에게 매우 편리한 수단이 되고 있습니다.
유럽에서는 진보적인 데이터 권리와 국가별로 상이한 검사 규정이라는 양면성이 존재합니다. 일반 데이터 보호 규정(GDPR(EU 개인정보보호규정))은 명시적인 동의 획득, 다단계 인증, 그리고 암호화된 데이터 전송을 의무화하고 있어, 규정 준수 비용은 상승하지만 소비자의 신뢰는 높아지고 있습니다. 네덜란드나 영국 등 일부 국가에서는 직접 주문이 허용되고 있지만, 프랑스에서는 의료 전문가의 감독이 필수로 규정되어 있습니다. 각 벤더사는 현지 법률에 맞추어 기능을 활성화하거나 비활성화할 수 있는 모듈식 플랫폼을 도입하고 있어, 획일적인 확장 전략이 아닌 지역에 맞춘 전략을 채택하고 있음을 알 수 있습니다. 소비자들 사이에서는 건강 지향적인 검사 패키지에 대한 관심이 높아지고 있으며, 특히 지역 공중보건 우선순위에 부합하는 심혈관계 및 대사계 특징을 통합한 패키지에 대한 수요가 증가하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the consumer genomics market size was valued at USD 2.39 billion in 2025 and estimated to grow from USD 2.96 billion in 2026 to reach USD 8.66 billion by 2031, at a CAGR of 23.95% during the forecast period (2026-2031).
This report is Segmented by Application (Genetic Relatedness, Diagnostics, and More), Technology (Microarray Genotyping, SNP Genotyping, and More), Sample Type (Saliva, Buccal Swab, and More), Distribution Channel (Direct-To-Consumer, Physician-Mediated & Clinics, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Consumer Genomics Market Trends and Insights
Rising Consumer & Physician Interest in DTC Kits
More than 33 million tests were performed in 2023, illustrating how genomic literacy now influences everyday health decisions. Physicians increasingly view home-based results as a conversation starter for preventive care, especially when genetic counseling supports interpretation. Consumer empowerment is evident in demand for combined ancestry, pharmacogenetic, and disease-predisposition offerings that translate data into precise diet, exercise, and medication choices. Clinics complement this trend by integrating secure portals that import DTC files into electronic health records for longitudinal monitoring. The shift confirms a behavioral move from episodic testing toward continuous genomic engagement.
Continuous Fall in Sequencing Costs & Tech Advances
The first human genome cost USD 3 billion. Today, whole genome sequencing services are regularly priced below USD 1,000, shrinking the economic barrier that once limited mainstream adoption. Next-generation sequencers deliver higher accuracy and shorter run times, enabling week-long turnarounds that align with consumer expectations for rapid insights. GeneDx recently paid USD 51 million for Fabric Genomics to integrate AI-based variant interpretation, a deal that highlights market demand for automated analytics at scale. These advances feed directly into richer polygenic scores covering cardiovascular, metabolic, and oncologic conditions.
Data-Privacy & Cybersecurity Breaches
The 2023 breach that exposed 7 million 23andMe profiles demonstrated how quickly trust can erode when genomic vaults are compromised. The U.S. Federal Trade Commission has since tightened oversight, fining firms that misrepresent security practices or fail to purge raw DNA files when customers withdraw consent. Public anxiety remains acute around genetic discrimination in insurance, despite protections such as the Genetic Information Nondiscrimination Act. Industry leaders now anchor marketing around bank-grade encryption, zero-knowledge proof architectures, and regular third-party audits to reassure skeptical buyers.
Other drivers and restraints analyzed in the detailed report include:
- Expansion Of Supportive DTC Regulatory Corridors
- Integration Of Polygenic Risk Scores Within Insurance Plans
- Patchy, Evolving Multi-Country Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ancestry services commanded 37.85% of 2025 revenue, illustrating their early mover appeal among first-time kit buyers. Growing penetration of health, nutrition, and sports performance assays is reshaping the consumer genomics market size for premium products that integrate dietary guidance, sleep coaching, and personalized supplements. Sports nutrition tests alone are charting a 28.1% CAGR through 2031 as elite and amateur athletes seek genotype-matched macronutrient ratios. Diagnostic panels for monogenic disorders also gain ground by pairing carrier screening with actionable reproductive counseling. Consumers increasingly prefer bundled offerings that fold ancestry, traits, and wellness into one subscription, suggesting a gradual fade of single-purpose genealogy kits. Stakeholders that position tests within broader digital health ecosystems, including mobile coaching apps, strengthen customer lifetime value as they evolve from one-off sales to recurring insights.
Second-generation platforms now embed pharmacogenomic modules that translate metabolizer status into practical medication adjustments covering anticoagulants, antidepressants, and statins. Clinics report reduced adverse drug events when such data appears in electronic health records ahead of prescribing decisions. Regulatory clarity around wellness versus diagnostic claims continues to influence feature design, yet early evidence indicates multi-category kits secure higher average selling prices without prolonging turnaround times.
SNP genotyping underpins 44.12% of 2025 kit volumes, favored for cost efficiency and a decade-long legacy of accuracy. Even so, insurance-backed programs are accelerating the shift toward polygenic risk-scoring engines that integrate hundreds of thousands of variants to deliver continuous risk curves for complex diseases. This subsegment is expected to expand at a 31.1% CAGR, outpacing any other technology stack inside the consumer genomics market. Whole-genome sequencing enjoys a price inflection point below USD 1,000, prompting Bupa to pilot genomic wellness packages for select enrollees seeking comprehensive coverage across 300 genes. Microarrays remain relevant for ancestry work because historical reference libraries map seamlessly to their variant selection, whereas targeted sequencing panels carve niches in cardiovascular or oncology-focused kits where depth of coverage matters.
Cloud pipelines have matured to the point where raw read alignment, variant calling, and annotation complete in hours rather than days, giving vendors the agility to promise single-digit-day delivery windows. The maturation of containerized bioinformatics also enables smaller upstarts to rent capacity from hyperscaler marketplaces without building expensive on-premise infrastructure, democratizing entrance into data-rich segments.
Complete Report Scope:
- By Application
- Genetic Relatedness
- Diagnostics
- Lifestyle, Wellness & Nutrition
- Ancestry
- Personalized Medicine & Pharmacogenetics
- Sports Nutrition & Health
- Recreational Traits
- Other Application Types
- By Technology
- Microarray Genotyping
- SNP Genotyping
- Targeted Sequencing Panels
- Whole Exome Sequencing (WES)
- Whole Genome Sequencing (WGS)
- Polygenic Risk Scoring Analytics
- Other Technologies
- By Sample Type
- Saliva
- Buccal Swab
- Blood Spot
- Other Samples
- By Distribution Channel
- Direct-to-Consumer
- Physician-mediated & Clinics
- Pharmacies & Retail
- Health & Wellness Partnerships
- Insurance Partnerships
- Corporate Wellness Programs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 41.12% revenue in 2025 due to high consumer awareness, mature digital payment infrastructure, and clinician familiarity with genomic decision-support tools. The consumer genomics market size in the region will keep expanding as state-by-state legislative clarity tempers earlier litigation risks surrounding privacy and data ownership. Leading universities frequently partner with kit vendors to crowd-source research cohorts, offering free or discounted tests that funnel additional volume into reference databases.
Asia-Pacific, advancing at a 26.3% CAGR, stands out as the prime expansion frontier. Rising disposable incomes in China, India, and Southeast Asia intersect with escalating lifestyle diseases, making preventive genomic risk assessment an attractive household expenditure. Local governments are investing in national genome projects that stimulate consumer curiosity while suppliers localize content in Mandarin, Hindi, and Bahasa to overcome linguistic hurdles. At-home saliva collection bypasses hospital queues in megacities, a convenience valued by middle-class families balancing busy schedules.
Europe presents a dichotomy of progressive data rights and heterogeneous testing rules. The General Data Protection Regulation forces explicit consent practices, multi-factor authentication, and encrypted transfer, elevating compliance costs but building consumer confidence. Countries like the Netherlands and the UK permit direct ordering, yet France insists on medical oversight. Vendors deploy modular platforms that activate or deactivate features to fit local laws, indicating a tailored rather than blanket expansion strategy. Consumers show a growing appetite for health-oriented packages, especially those integrating cardiovascular and metabolic traits that align with regional public-health priorities.
- 23andMe
- AncestryDNA
- MyHeritage
- Helix
- Illumina
- Color Genomics
- Veritas Genetics
- Nebula Genomics
- Futura Genetics
- Gene by Gene
- Pathway genomics
- Xcode Life
- Toolbox Genomics
- CircleDNA
- Dante Labs
- LifeDNA
- Living DNA
- Invitae
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Consumer & Physician Interest In DTC Kits
- 4.2.2 Continuous Fall In Sequencing Costs & Tech Advances
- 4.2.3 Expansion Of Supportive DTC Regulatory Corridors
- 4.2.4 Integration Of Polygenic Risk Scores Within Insurance Plans
- 4.2.5 Retail-Pharmacy Genomic Kiosks & Partnerships
- 4.2.6 Blockchain-Enabled Genomic Data Monetization Ecosystems
- 4.3 Market Restraints
- 4.3.1 Data-Privacy & Cybersecurity Breaches
- 4.3.2 Patchy, Evolving Multi-Country Regulations
- 4.3.3 Insolvency-Driven Liquidation Of Genetic Databases
- 4.3.4 AI-Driven Bias From Over-Indexed Ethnicity Datasets
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Application
- 5.1.1 Genetic Relatedness
- 5.1.2 Diagnostics
- 5.1.3 Lifestyle, Wellness & Nutrition
- 5.1.4 Ancestry
- 5.1.5 Personalized Medicine & Pharmacogenetics
- 5.1.6 Sports Nutrition & Health
- 5.1.7 Recreational Traits
- 5.1.8 Other Application Types
- 5.2 By Technology
- 5.2.1 Microarray Genotyping
- 5.2.2 SNP Genotyping
- 5.2.3 Targeted Sequencing Panels
- 5.2.4 Whole Exome Sequencing (WES)
- 5.2.5 Whole Genome Sequencing (WGS)
- 5.2.6 Polygenic Risk Scoring Analytics
- 5.2.7 Other Technologies
- 5.3 By Sample Type
- 5.3.1 Saliva
- 5.3.2 Buccal Swab
- 5.3.3 Blood Spot
- 5.3.4 Other Samples
- 5.4 By Distribution Channel
- 5.4.1 Direct-to-Consumer
- 5.4.2 Physician-mediated & Clinics
- 5.4.3 Pharmacies & Retail
- 5.4.4 Health & Wellness Partnerships
- 5.4.5 Insurance Partnerships
- 5.4.6 Corporate Wellness Programs
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 23andMe
- 6.3.2 AncestryDNA
- 6.3.3 MyHeritage
- 6.3.4 Helix
- 6.3.5 Illumina
- 6.3.6 Color Genomics
- 6.3.7 Veritas Genetics
- 6.3.8 Nebula Genomics
- 6.3.9 Futura Genetics
- 6.3.10 Gene by Gene
- 6.3.11 Pathway Genomics
- 6.3.12 Xcode Life
- 6.3.13 Toolbox Genomics
- 6.3.14 CircleDNA
- 6.3.15 Dante Labs
- 6.3.16 LifeDNA
- 6.3.17 Living DNA
- 6.3.18 Invitae
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment