|
시장보고서
상품코드
2123503
치과용 주사기 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Dental Syringes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 치과용 주사기 시장 규모는 2025년 1억 6,061만 달러에서 2026년에는 1억 6,893만 달러로 확대되어 2026년부터 2031년까지 CAGR 5.18%로 성장을 지속하여, 2031년까지 2억 1,752만 달러에 이를 것으로 예측됩니다.
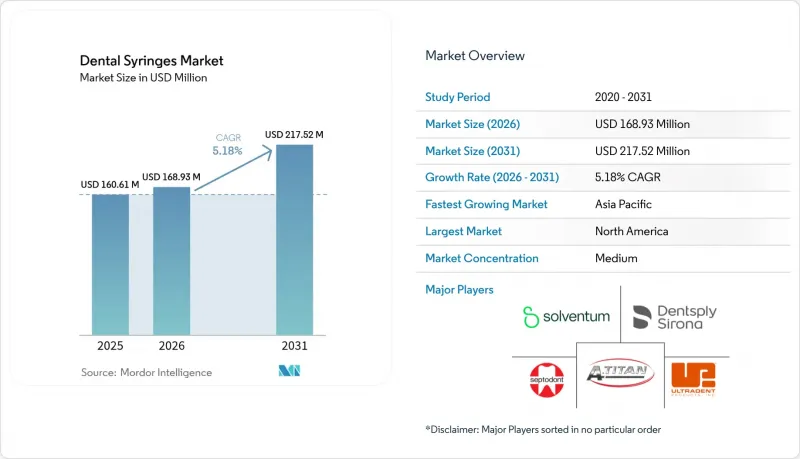
본 보고서는 용도별(재사용 가능한 치과용 주사기 등), 제품 유형별(흡입식 및 비흡입식), 소재별(금속 및 플라스틱), 최종 사용자별(치과 병원 및 클리닉, 치과 기공소 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 치과용 주사기 시장 동향 및 인사이트
고령화에 따른 보철 치료 증가
60세 이상 성인 인구는 이미 10억 명에 달하며, 2030년까지 14억 명을 넘어설 전망입니다. 이 연령대에서 주류를 이루는 보철 치료에는 정확한 마취제 투여가 요구되며, 이로 인해 치과 병원들은 컴퓨터 제어 국소 마취 장치 등 첨단 치과용 주사기 솔루션의 도입을 서두르고 있습니다. 말레이시아에서는 25-54세 성인이 가장 큰 환자층을 차지하고 있어 진료 의자의 가동률에 추가적인 부담이 가중되고 있습니다. 치과 보험사들은 구강 건강과 전신 건강의 연관성을 강조하고 있으며, 이는 예방적 진료를 촉진하고 고품질 주사기에 대한 수요를 뒷받침하고 있습니다. 그 결과, 치과에서는 시술자의 피로를 줄이면서 여러 번의 주사를 놓을 수 있는 인체공학적 디자인이 선호되고 있습니다. 전악 수복이 증가함에 따라, 주사기의 배럴 부분이 시야가 확보되고 흡입량을 조절할 수 있는 설계가 표준으로 자리 잡고 있습니다.
충치 및 치주질환 유병률의 상승
세계적으로 2억 8,000만 명 이상의 고령자가 치료되지 않은 충치나 치주질환으로 고통받고 있습니다. 개정된 CDC 지침에서는 환자마다 카트리지식 주사기를 멸균해야 하며, 바늘과 마취제 카트리지는 일회용이어야 한다고 규정하고 있습니다. 신흥 경제국에서는 당분이 많은 식단과 예방 조치의 부족으로 인해 질환 발생률이 급격히 증가하고 있으며, 비용 대비 효과가 높고 규제를 준수하는 주사기에 대한 수요가 생겨나고 있습니다. 텔레덴티스트리(원격 치과 진료)를 통해 청소년층의 조기 진단이 가능해지면서, 국소 마취가 필요한 저침습적 수복 치료의 기회가 증가하고 있습니다. ‘Curodont Repair Fluoride Plus’와 같은 제품을 이용한 드릴이 필요 없는 충치 수복과 같은 초기 단계의 개입은 치료 시간을 단축하지만, 복잡한 증례에서는 안전한 약제 도포를 확인하기 위해 여전히 흡입 장치에 의존하고 있습니다.
저소득 지역의 숙련된 치과의사 부족
많은 신흥국에서는 주민 1만 명당 치과의사가 1명도 채 되지 않습니다. WHO는 지리적 및 경제적 장벽으로 인해 고령자들이 적절한 시기에 치료를 받지 못하고 있다고 지적하고 있습니다. 연수 체계가 미흡하여 흡인 및 유량 설정에 대한 지도가 필요한 첨단 컴퓨터 제어 장치의 도입이 지연되고 있습니다. 정부는 이동 진료소에 자금을 지원하여 대응하고 있지만, 지출은 기본적인 기구에 중점을 두고 있습니다. 그 결과, 치과용 주사기 업계에서는 가혹한 재처리 과정을 견디고 제한된 운영 예산에 부합하는 단순화된 금속 제품이 공급되고 있습니다.
부문 분석
2025년에는 확립된 오토클레이브 인프라의 혜택을 받아 재사용 가능한 기기가 매출의 58.20%를 차지했습니다. 같은 해, 감염 관리에 대한 경계심 고조를 반영하여 치과용 주사기 시장에서 일회용 제품 시장 규모는 연평균 성장률(CAGR) 6.28%를 기록하며 급속히 확대되었습니다. 하루에 30회 이상 주사를 시행하는 진료소에서는 멸균기의 처리 능력 한계가 과제로 지적되고 있으며, 그 때문에 처리 시간을 단축할 수 있는 색상별로 구분된 일회용 주사기 배럴을 선호하여 채택하고 있습니다.
일회용 제품의 도입에는 환경적인 측면에서 엄격한 시선이 쏠리고 있습니다. EU의 규정에 따라 2030년까지 재활용 가능한 포장이 의무화됨에 따라, 공급업체들은 퇴비화 목표를 충족하는 PLA 및 PHA 소재의 주사기 배럴 출시를 추진하고 있습니다. 대규모 그룹 진료소에서는 가격 안정화와 공급 확보를 위해 다년 계약을 체결하고 있습니다. 자본 예산을 통해 고성능 세척·소독기 도입이 가능하고, 단위 비용 절감이 인력 부족의 제약을 상회하는 경우, 재사용 가능한 제품이 여전히 주류를 이루고 있습니다. 안전성과 지속가능성의 균형을 맞추기 위해, 금속 흡입 핸들에 일회용 바늘이나 카트리지를 결합하는 하이브리드 전략도 등장하고 있습니다.
흡입식 모델은 주입 전에 혈관 내부에 들어가지 않았음을 임상의가 확인할 수 있기 때문에 2025년에는 치과용 주사기 시장의 61.55% 점유율을 차지했습니다. 한편, 비흡입식 디자인은 일상적인 복합레진 충전이나 예방 처치에서 더 간편한 취급을 원하는 젊은 치과의사들에게 지지를 받고 있습니다.
디지털 CCLAD 플랫폼에는 수동 흡입 없이도 조직의 차이를 식별할 수 있는 압력 센서가 내장되어 있습니다. 얇은 바늘과 결합함으로써, 이러한 시스템은 거의 통증 없는 침윤 마취를 실현하여 선택적 심미 치과 치료에서 환자의 수용도가 높아지고 있습니다. LED 방식의 ‘Nuralyte’와 같은 무바늘 장치는 더 큰 변화를 가져올 것으로 기대되지만, 적응증이 얕은 치료로 한정되어 있어 보급 여부는 향후 FDA의 승인에 달려 있습니다. 기존의 흡입식 주사기는 끊임없이 진화하는 치과용 주사기 시장에서 입지를 유지하기 위해 실리콘 코팅 적용 및 플런저 마찰 저감 등의 개선이 이루어지고 있습니다.
지역별 분석
북미는 2025년 매출의 43.10%를 차지했습니다. 이는 CDC의 엄격한 프로토콜과 보험 적용 범위 확대에 따라 고가 장비 도입이 지속되었기 때문입니다. 대규모 그룹 진료소에서는 컴퓨터 제어 시스템이 일반적이며, 성인의 91%가 치과 진료를 연례 건강 검진과 동등하게 인식하고 있다는 점이 시술 건수의 기반이 되고 있습니다. 2025년 4월에 부과된 관세로 인해 장비 비용이 상승함에 따라, 판매업체들은 제품 라인업을 유지하기 위해 멕시코와 베트남 등 조달처를 다각화하고 있습니다. 3M에서 분사한 Solventum은 매출이 1.8% 감소했음에도 불구하고, 2024년 1분기 치과 솔루션 매출에서 3억 3,500만 달러를 기록하며 해당 지역의 치과용 주사기 시장에서 회복력을 보여주었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 6.22%로 가장 빠르게 성장하는 지역입니다. 말레이시아는 이러한 추세를 여실히 보여주고 있으며, 2027년까지 치과 서비스 시장 규모는 28억 달러에 달할 전망이며, 그 중 70%를 민간 클리닉이 차지할 것으로 예측됩니다. 중산층의 소득 증가에 따라 정확한 국소 마취가 필요한 심미 교정 치과 및 임플란트 치료에 대한 수요가 높아지고 있습니다. 치과 관광에서는 호텔과 같은 회복실과 EU 기준에 부합하는 감염 관리 프로토콜이 결합되어 있으며, 의료 기관에서는 바코드가 부착된 필오프 파우치에 포장된 일회용 흡입용 주사기가 선호되고 있습니다. 국내 제조업체는 비용 효율이 높은 폴리스티렌 실린더를 공급하는 한편, 수입업체는 고급 CCLAD 유닛을 판매하고 있어 치과용 주사기 시장 내에서 다층적인 비즈니스 기회가 창출되고 있습니다.
순환형 경제의 추진으로 인해 소재 선정 방식이 재편되는 가운데, 유럽에서는 꾸준한 성장이 유지되고 있습니다. EU의 ‘포장 및 포장 폐기물에 관한 규정’에 따라 제조업체는 2030년까지 재활용성을 고려한 부품 재설계를 의무화해야 합니다. 독일에서는 임상용 바이오플라스틱에 대한 지자체 차원의 수거가 시범적으로 실시되고 있으며, 조기에 움직이기 시작한 기업들은 브랜드 측면에서 우위를 점하고 있습니다. 프랑스와 스칸디나비아의 치과에서는 탄소 중립적인 수복 치료를 홍보하고 있으며, 그 결과 PLA나 PHA로 제작된 주사기 본체가 선호되고 있습니다. 동유럽에서는 합리적인 가격의 풀 아치 임플란트를 찾는 해외 치과 관광객이 증가하고 있으며, 이는 중가대 흡입 장치의 판매를 견인하고 있습니다. 중동 및 아프리카에서는 수요가 가속화되고 있으며, 특히 의료 관광과 호화로운 접객를 결합한 GCC 국가들에서 두드러집니다. 남미에서는 점진적인 성장이 나타나고 있으며, 브라질과 아르헨티나에서는 현지 플라스틱 생산을 활용하여 치과용 주사기 시장공급망 안정화를 도모하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the dental syringes market size is expected to grow from USD 160.61 million in 2025 to USD 168.93 million in 2026 and is forecast to reach USD 217.52 million by 2031 at 5.18% CAGR over 2026-2031.
This report is Segmented by Usability (Reusable Dental Syringes, and More), Product Type (Aspirating and Non-Aspirating), Material (Metallic and Plastic), End-User (Dental Hospitals & Clinics, Dental Laboratories, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market and Forecasts are Provided in Terms of Value (USD).
Global Dental Syringes Market Trends and Insights
Ageing Population Expanding Prosthodontic Workload
Adults aged 60 and older already number 1.0 billion and will pass 1.4 billion by 2030. Prosthodontic interventions that dominate this cohort demand precise anesthetic delivery, pushing clinics to adopt advanced dental syringes market solutions such as computer-controlled local anesthetic devices . In Malaysia, adults aged 25-54 form the largest patient group, further straining chair capacity. Dental insurers highlight the link between oral and systemic health, driving preventive visits and reinforcing demand for premium syringes. Practices consequently prefer ergonomic designs that perform multiple injections without user fatigue. As full-arch restorations rise, syringe designs featuring high barrel clarity and controlled aspiration are becoming standard .
Rising Prevalence of Caries & Periodontal Disease
More than 280 million older adults face untreated caries or gum disease worldwide. Updated CDC guidelines stipulate that cartridge syringes must be sterilized between patients and that needles as well as anesthetic cartridges remain single use . Emerging economies report faster disease incidence due to sugary diets and limited prophylaxis, opening space for cost-effective yet compliant syringes. Teledentistry is enabling earlier diagnosis among younger adults, creating more occasions for minimally invasive restorations that still need local anesthesia. Early-stage interventions such as drill-free cavity repair delivered by products like Curodont Repair Fluoride Plus lower chair time, but complex cases continue to rely on aspirating devices that confirm safe deposition.
Shortage of Skilled Dentists in Low-Income Regions
Many emerging economies record fewer than one dentist per 10,000 residents. The WHO notes that geographic and economic barriers keep older adults from timely care. Limited training capacity delays the uptake of advanced computer-controlled devices that require instruction on aspiration and flow-rate settings. Governments respond by funding mobile clinics but focus spending on basic instruments. In turn, syringe makers supply simplified metallic formats that tolerate rugged reprocessing and align with thin operating budgets inside the dental syringes industry.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Shift to Single-Use Safety Syringes for Infection Control
- Growth in Dental Tourism Across APAC & CEE
- Up-Front Cost of Electronic & Smart Syringes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reusable devices retained 58.20% revenue in 2025, benefiting from well-established autoclave infrastructures. In the same year disposables grew swiftly as the dental syringes market size for single-use formats recorded a 6.28% CAGR, reflecting heightened infection control vigilance. Practices with patient loads exceeding 30 daily injections cite sterilizer bottlenecks, thus preferring color-coded disposable barrels that cut turnaround time.
Disposable adoption faces environmental scrutiny; the EU framework compels recyclable packaging by 2030, prompting suppliers to launch PLA and PHA barrels that meet compostability targets. Large group practices lock in multi-year contracts to stabilize pricing and guarantee supply. Reusables still dominate where capital budgets cover advanced washer-disinfectors and where unit cost savings outweigh staffing constraints. Hybrid strategies emerge, with clinics using metallic aspirating handles paired with single-use needles and cartridges to balance safety and sustainability.
Aspirating models captured 61.55% of dental syringes market share in 2025 because they allow clinicians to verify they are not in a blood vessel before injecting. Non-aspirating designs appeal to younger practitioners seeking simpler handling during routine composites and prophylaxis.
Digital CCLAD platforms incorporate pressure sensors that can identify tissue differences without manual aspiration. When paired with narrow-gauge needles, these systems deliver near-painless infiltration which is expanding patient acceptance in elective cosmetic work. Needle-free devices such as LED-based Nuralyte promise further disruption; however, indications remain limited to shallow treatments and adoption hinges on upcoming FDA clearance. Traditional aspirating syringes now integrate silicone coating and reduced plunger friction to maintain relevance within an evolving dental syringes market.
Complete Report Scope:
- By Usability
- Reusable Dental Syringes
- Disposable Dental Syringes
- By Product Type
- Aspirating
- Non-aspirating
- By Material
- Metallic
- Plastic
- By End-User
- Dental Hospitals & Clinics
- Dental Laboratories
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 43.10% of 2025 revenue as stringent CDC protocols and widespread insurance coverage sustained premium device uptake. Computer-controlled systems are common in large group practices, and 91% of adults equate dental visits with annual physicals which underpins procedure volumes. Tariffs imposed in April 2025 raise equipment costs so distributors diversify toward Mexico and Vietnam sources to maintain catalog breadth. Solventum, spun off from 3M, posted USD 335 million in Q1-2024 dental solutions sales in spite of a 1.8% revenue dip, demonstrating resilience in the regional dental syringes market.
Asia-Pacific is the fastest-growing territory with a 6.22% CAGR to 2031. Malaysia illustrates the trend: a USD 2.8 billion dental services sector by 2027 with private clinics holding 70% share. Rising middle-class incomes boost demand for cosmetic orthodontics and implantology, both reliant on accurate local anesthesia. Dental tourism blends hotel-style recovery suites with EU-compliant infection protocols, leading facilities to favor single-use aspirating syringes packaged in bar-coded peel pouches. Domestic manufacturers supply cost-efficient polystyrene barrels while importers market premium CCLAD units, creating tiered opportunities inside the dental syringes market.
Europe maintains consistent growth as the circular-economy agenda reshapes material selection. The EU Packaging and Packaging Waste Regulation forces producers to redesign components for recyclability by 2030. Germany pilots municipal collection of clinical-grade bioplastics, giving early movers brand advantage. Clinics in France and Scandinavia advertise carbon-neutral restorations which in turn favor PLA or PHA syringe bodies. Eastern Europe gains momentum from inbound dental tourists seeking affordable full-arch implants, driving mid-range aspirating device sales. The Middle East and Africa record accelerating demand, especially in GCC countries that pair medical tourism with luxury hospitality. South America exhibits incremental gains, with Brazil and Argentina leveraging local plastics production to stabilize supply chains within the dental syringes market.
- Solventum
- Dentsply Sirona
- Septodont
- Vista Dental Products
- Integra LifeSciences
- A. Titan Instrument
- Ultradent Products
- Power Dental USA
- Accesia
- Anthogyr
- Carl Martin
- Asa Dental
- Faro
- DiaDent
- Milestone Scientific
- Orsing AB
- Kulzer
- Henry Schein
- Coricama S.r.l
- Tillid Dental
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Ageing population expanding prosthodontic workload
- 4.2.2 Rising prevalence of caries & periodontal disease
- 4.2.3 Rapid shift to single-use safety syringes for infection control
- 4.2.4 Growth in dental tourism across APAC & CEE
- 4.2.5 Chair-side digital anesthesia delivery boosting premium syringe demand
- 4.2.6 RFID-enabled instrument-tracking mandates in high-income clinics
- 4.3 Market Restraints
- 4.3.1 Shortage of skilled dentists in low-income regions
- 4.3.2 Up-front cost of electronic & smart syringes
- 4.3.3 Regulatory crack-down on single-use plastics raising compliance cost
- 4.3.4 Volatile supply of medical-grade stainless steel
- 4.4 Regulatory Landscape
- 4.5 Porters Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Usability
- 5.1.1 Reusable Dental Syringes
- 5.1.2 Disposable Dental Syringes
- 5.2 By Product Type
- 5.2.1 Aspirating
- 5.2.2 Non-aspirating
- 5.3 By Material
- 5.3.1 Metallic
- 5.3.2 Plastic
- 5.4 By End-User
- 5.4.1 Dental Hospitals & Clinics
- 5.4.2 Dental Laboratories
- 5.4.3 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Solventum
- 6.3.2 Dentsply Sirona
- 6.3.3 Septodont
- 6.3.4 Vista Dental Products
- 6.3.5 Integra LifeSciences
- 6.3.6 A. Titan Instrument Inc.
- 6.3.7 Ultradent Products
- 6.3.8 Power Dental USA
- 6.3.9 Accesia
- 6.3.10 Anthogyr SAS
- 6.3.11 Carl Martin GmbH
- 6.3.12 Asa Dental SpA
- 6.3.13 Faro SpA
- 6.3.14 Diadent Group International
- 6.3.15 Milestone Scientific
- 6.3.16 Orsing AB
- 6.3.17 Kulzer GmbH
- 6.3.18 Henry Schein Inc.
- 6.3.19 Coricama S.r.l
- 6.3.20 Tillid Dental
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment