

|
시장보고서
상품코드
2123516
디지털 정량 흡입기 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Digital Dose Inhaler - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
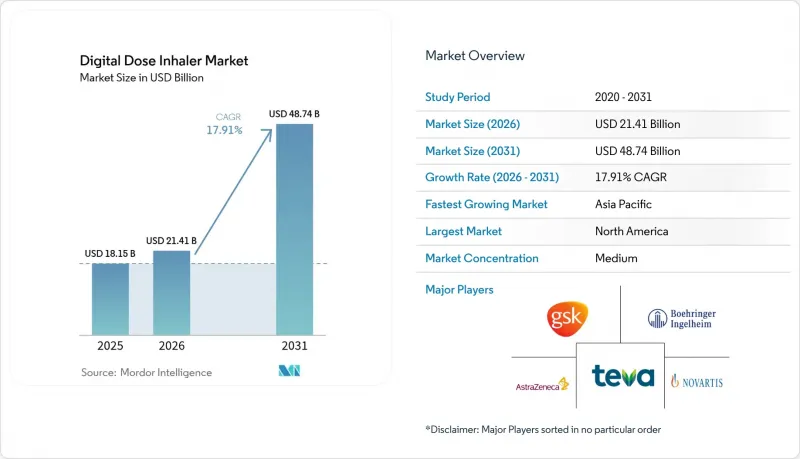
에 의하면, 디지털 정량 흡입기 시장 규모는 2025년 181억 5,000만 달러에서 2026년에는 214억 1,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 17.91%로 성장을 지속하여, 2031년에는 487억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품별(건조 분말 흡입기 등), 적응증별(COPD 등),유형별(브랜드 제품 및 제네릭 제품), 환자 연령대별(소아 등), 유통 채널별(병원 약국 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 디지털 정량 흡입기 시장 동향 및 인사이트
전 세계적으로 증가하는 호흡기 질환의 부담
2021년에는 2억 1,339만 명이 만성 호흡기 질환을 앓고 있으며, 복약 순응도를 객관적으로 기록하는 커넥티드 흡입기에 대한 수요가 지속되고 있습니다. 연구에 따르면, 스마트 기기와 연동된 행동 변화 프로그램을 활용한 COPD 환자의 약물 복용 준수율이 44% 향상된 것으로 나타났습니다. 인공지능(AI)의 통합을 통해 증상 악화 시 조기 경보가 가능해지면서, 디지털 기기는 수동적인 추적 도구에서 능동적인 질환 관리 도구로 진화하고 있습니다.
고령 환자층의 확대
고령층은 2030년까지 연평균 성장률(CAGR)이 18.67%로 가장 빠르게 확대되고 있는 사용자층입니다. 노화에 따른 손의 불편함으로 인해 직관적으로 조작할 수 있는 호흡 감지식 기기가 주목받고 있습니다. 인터페이스의 단순화와 디스플레이의 대형화로 사용 편의성이 향상되고 있는 한편, 메디케어 지급 시범 프로그램에서는 센서 비용의 환급이 시험적으로 도입되고 있지만, 전국적인 보험 적용 범위에는 여전히 편차가 나타나고 있습니다.
연결형 흡입기의 프리미엄 가격 책정
스마트 흡입기는 기존 제품보다 훨씬 비싸며, 총 소유 비용에는 데이터 통신 요금제와 소프트웨어 구독료가 포함됩니다. 경제성 평가에서는 임상적 이점이 인정되고 있으나, 약국의 이익률이 낮은 상황에서는 비용 대비 효과에 의문이 제기되고 있습니다. 단계적 가격 책정이나 보험사와의 제휴는 진전되고 있지만, 특히 공적 의료 제도에서 일관된 보상 체계가 부재하기 때문에 개발도상 지역에서의 보급이 제한되고 있습니다.
부문 분석
2025년 시점에서 정량 흡입기는 디지털 정량 흡입기 시장 점유율의 48.05%를 차지하고 있으며, 이는 사용자가 익숙한 제품이라는 점과 제조 측면에서의 경제성이 성숙해졌음을 보여줍니다. 기업들이 초저 GWP(지구 온난화 지수) 추진제로 전환함에 따라, 이 부문의 디지털 정량 흡입기 시장 규모는 연평균 성장률(CAGR) 13.97%로 확대될 것으로 예측됩니다. 환경 규제로 인해 제제 재설계가 가속화되고 있으며, 아스트라제네카사의 HFO-1234ze(E) 도입으로 광범위한 환경에 미치는 영향이 99.9% 감소했습니다.
소프트 미스트식 흡입기는 폐 침착률이 높고 추진제가 필요하지 않아, 디지털 정량 흡입기 시장 전체를 상회하는 연평균 성장률(CAGR) 19.62%로 성장을 지속하고, 있습니다. 기기의 소형화와 내장 센서를 통해 실시간 유량 측정이 가능해져, 정확한 투여량 확인을 원하는 의료 제공업체들에게 지지를 받고 있습니다. 드라이 파우더식 흡입기는 기후가 서늘하고 성인 사용자의 흡기 유량이 충분한 지역에서는 여전히 수요가 있지만, 높은 습도로 인해 열대 지역에서의 보급은 제한적입니다.
2025년에는 천식이 매출의 41.02%를 차지했습니다. 이는 소아 및 청년 환자층이 방대하다는 점과, 연결형 복약 순응도 솔루션을 뒷받침하는 풍부한 임상 증거에 기인한 것입니다. 한편, COPD용 디지털 정량 흡입기 시장 규모는 고령화로 인해 질병의 이환 기간이 길어지고, 보험사가 입원 횟수 감소를 통해 비용 절감을 도모함에 따라 연평균 성장률(CAGR) 18.56%라는 더 빠른 속도로 확대되고 있습니다. HealthPrize의 RespiPoints는 티오트로피움 사용자의 복약 순응도가 44% 향상되었음을 입증했으며, 이는 실질적인 비용 절감으로 이어지고 있습니다.
낭포성 섬유증 시장이 연평균 성장률(CAGR) 19.18%로 성장하고 있는 것은 간병인들이 고부가가치 투약 요법을 최적화하기 위해 프리미엄 모니터링에 투자하려는 의지를 보여줍니다. AI 알고리즘은 현재 질환별 흡입 패턴을 구별하고 각 적응증에 맞춘 개별 지도를 실현함으로써, 커넥티드 플랫폼의 임상적 의의를 높이고 있습니다.
지역별 분석
북미는 정교한 보험 시스템, 높은 COPD 유병률, 그리고 디지털 치료제의 조기 FDA 승인을 배경으로 2025년 매출의 42.85%를 차지했습니다. GSK와 Propeller Health는 센서가 탑재된 Ellipta 흡입기를 전미에 출하하기 위해 제휴를 확대하여, 처방전과 기술을 통합한 번들 제품의 상업적 실행 가능성을 입증했습니다. 캐나다는 단일 지불자 제도에 따른 조달력의 혜택을 받고 있으며, 각 주의 의약품 목록에서는 복약 순응도 보고서와 연동된 성과 기반 조달을 시범적으로 도입하고 있습니다. 멕시코에서는 중산층의 확대와 디지털 헬스 인센티브로 인해 중저가 의료기기 시장이 열리고 있습니다.
아시아태평양은 도시 지역의 대기 오염과 흡연이 COPD 환자 수 증가에 기여하고 있어, 2031년까지 연평균 성장률(CAGR)이 19.12%로 가장 빠르게 성장하는 지역입니다. 중국에서는 국민 전체에 걸친 질병 부담이 정책 입안자들에게 예방책 도입을 촉구하고 있으며, 공립 병원에서는 흡입기 데이터를 전자 차트와 통합하는 클라우드 대시보드의 시범 운영이 진행되고 있습니다. 인도에서는 4G 통신 지역 확대와 원격의료 지침 개정에 힘입어 센서 키트의 온라인 약국 판매가 활성화되고 있으나, 여전히 가격 격차가 남아 있습니다. 일본은 급속한 고령화와 성숙한 기술 문화를 겸비하고 있어, AI 코칭 기능을 탑재한 프리미엄 소프트 미스트 흡입기에게 유망한 시장이 되고 있습니다. 유럽은 성숙해 가면서도 혁신적인 시장이며, 환경 규제가 전 세계적인 선례를 만들고 있습니다. F가스 규제(2024/573)는 2025년 이후 할당량 외 HFC 충전식 흡입기의 신규 판매를 금지하고 있어, 저GWP 제품의 도입 일정을 가속화하고 있습니다. 독일의 DiGA(디지털 의료기기) 체계에서는 인증된 디지털 헬스 앱 비용이 보험 적용 대상이 되므로, 흡입기용 컴패니언 소프트웨어의 급속한 보급이 예상됩니다. 영국은 현실적인 입장을 유지하고 있으며, 입원 방지 효과가 입증된 의료기기에 대해 보험 적용을 실시했습니다. 중동 및 아프리카 및 남미는 아직 발전 단계에 있지만 유망한 시장이며, 인프라, 의료진 교육, 소비자의 구매력 등과 같은 제약이 존재합니다. 기부 프로그램이나 단계적 가격 책정 모델을 통해 이러한 격차 해소를 도모하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the digital dose inhaler market size is expected to grow from USD 18.15 billion in 2025 to USD 21.41 billion in 2026 and is forecast to reach USD 48.74 billion by 2031 at 17.91% CAGR over 2026-2031.
This report is Segmented by Product (Dry Powder Inhalers, and More), Indication (COPD, and More), Type (Branded and Generic), Patient Age Group (Pediatric, and More), Distribution Channel (Hospital Pharmacies, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Dose Inhaler Market Trends and Insights
Escalating Global Respiratory Disease Burden
Chronic respiratory diseases affected 213.39 million people in 2021, sustaining demand for connected inhalers that objectively record adherence. Studies show 44% adherence improvement among COPD patients using behavior-change programs linked to smart devices. Integration of artificial intelligence is enabling early exacerbation alerts, moving digital devices from passive trackers to proactive disease-management tools.
Expanding Geriatric Patient Pool
The geriatric cohort is the fastest-growing user group at an 18.67% CAGR through 2030 as age-related dexterity limitations make intuitive breath-activated devices attractive. Simplified interfaces and larger displays improve usability, while Medicare payment pilots are experimenting with sensor reimbursement, although national coverage remains uneven.
Premium Pricing of Connected Inhaler Devices
Smart inhalers cost substantially more than conventional units, and total ownership expenses include data plans and software subscriptions. Economic evaluations find clinical benefits but question cost-effectiveness when pharmacy margins are narrow. Tiered pricing and payer partnerships are evolving, yet the lack of consistent reimbursement, especially in public systems, limits penetration in developing regions.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advancements in Smart Inhaler Platforms
- Transition Toward Digital Therapeutics and Remote Monitoring
- Complex Regulatory and Reimbursement Pathways
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Metered dose inhalers retained 48.05% of digital dose inhaler market share in 2025, underscoring user familiarity and mature manufacturing economics. The digital dose inhaler market size for this segment is projected to rise at a 13.97% CAGR as companies transition to ultra-low-GWP propellants. Environmental mandates are accelerating formulation re-engineering, with AstraZeneca's HFO-1234ze(E) rollout reducing broad environmental impact by 99.9%.
Soft-mist inhalers provide higher lung deposition and need no propellant, fueling a 19.62% CAGR that outpaces the broader digital dose inhaler market. Device miniaturization and embedded sensors allow real-time flow measurement, appealing to providers seeking precise dose verification. Dry-powder inhalers remain relevant in regions with cooler climates and robust inspiratory flow among adult users, yet high humidity limits uptake in tropical geographies.
Asthma accounted for 41.02% of revenue in 2025, buoyed by large pediatric and young-adult cohorts and plentiful clinical evidence supporting connected adherence solutions. The digital dose inhaler market size for COPD is expanding faster at 18.56% CAGR as aging populations lengthen disease duration and payers seek cost offsets through fewer hospitalizations. HealthPrize RespiPoints documented a 44% adherence increase among tiotropium users, translating to material cost savings.
Cystic fibrosis growth at 19.18% CAGR demonstrates willingness of caregivers to invest in premium monitoring to optimize high-value medication regimens. AI algorithms now differentiate disease-specific inhalation patterns, personalizing coaching for each indication and raising the clinical relevance of connected platforms.
Complete Report Scope:
- By Product
- Dry Powder Inhalers
- Metered Dose Inhalers
- Soft-Mist Inhalers
- By Indication
- COPD
- Asthma
- Cystic Fibrosis
- Other Respiratory Disorders
- By Type
- Branded
- Generic
- By Patient Age Group
- Pediatric
- Adult
- Geriatric
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 42.85% of revenue in 2025 on the back of sophisticated payer systems, high COPD prevalence, and early FDA approvals of digital therapeutics. GSK and Propeller Health broadened their collaboration to ship sensor-enabled Ellipta inhalers nationwide, demonstrating the commercial viability of integrated prescription-tech bundles. Canada benefits from single-payer purchasing leverage, while Provincial formularies are piloting outcome-based procurement tied to adherence reports. Mexico's growing middle class and digital-health incentives open gateways for mid-priced devices.
Asia-Pacific is the fastest-growing region at 19.12% CAGR through 2031 as urban air pollution and smoking contribute to rising COPD cases. China's population-level burden pressures policymakers to adopt preventive tools; public hospitals are trialling cloud dashboards that integrate inhaler data with electronic medical records. India's expanding 4G coverage and revised telemedicine guidelines underpin online pharmacy distribution of sensor kits, yet affordability gaps persist. Japan couples rapidly aging demographics with a mature technology culture, making it a fertile market for premium soft-mist inhalers bundled with AI coaching. Europe remains a mature but innovative market where environmental regulation sets global precedents. The F-Gas Regulation 2024/573 bans new HFC-filled inhalers outside of quota allocations from 2025, accelerating low-GWP adoption schedules. Germany's DiGA framework reimburses certified digital health apps, positioning inhaler companion software for rapid uptake. The United Kingdom maintains a pragmatic stance, reimbursing devices that demonstrate hospital-admission avoidance. Middle East & Africa and South America are nascent yet promising, limited by infrastructure, clinician training, and consumer purchasing power. Donation programs and tiered pricing models aim to bridge these gaps.
- Teva Pharmaceutical Industries
- GlaxoSmithKline
- AstraZeneca
- Boehringer Ingelheim
- Novartis
- Glenmark Pharmaceuticals
- Koninklijke Philips
- Propeller Health
- AptarGroup Inc.
- H&T Presspart Manufacturing Ltd.
- Trudell Medical Group
- Adherium Ltd.
- Resmed
- Vectura Group plc
- Mundipharma International
- 3M Drug Delivery Systems
- Cipla
- Opko Health Inc.
- Amiko Digital Health
- Pneuma Respiratory
- Findair
- Cohero Health
- BreatheSuite
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Global Respiratory Disease Burden
- 4.2.2 Expanding Geriatric Patient Pool
- 4.2.3 Technological Advancements in Smart Inhaler Platforms
- 4.2.4 Transition Toward Digital Therapeutics and Remote Monitoring
- 4.2.5 Integration of Data Analytics And Value-Based Care Models
- 4.2.6 Environmental Compliance and Low-Gwp Propellant Adoption
- 4.3 Market Restraints
- 4.3.1 Premium Pricing of Connected Inhaler Devices
- 4.3.2 Complex Regulatory and Reimbursement Pathways
- 4.3.3 Stringent Data Privacy and Cybersecurity Requirements
- 4.3.4 Semiconductor Supply Chain Constraints
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Dry Powder Inhalers
- 5.1.2 Metered Dose Inhalers
- 5.1.3 Soft-Mist Inhalers
- 5.2 By Indication
- 5.2.1 COPD
- 5.2.2 Asthma
- 5.2.3 Cystic Fibrosis
- 5.2.4 Other Respiratory Disorders
- 5.3 By Type
- 5.3.1 Branded
- 5.3.2 Generic
- 5.4 By Patient Age Group
- 5.4.1 Pediatric
- 5.4.2 Adult
- 5.4.3 Geriatric
- 5.5 By Distribution Channel
- 5.5.1 Hospital Pharmacies
- 5.5.2 Retail Pharmacies
- 5.5.3 Online Pharmacies
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Russia
- 5.6.2.7 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Teva Pharmaceutical Industries
- 6.3.2 GlaxoSmithKline plc
- 6.3.3 AstraZeneca plc
- 6.3.4 Boehringer Ingelheim
- 6.3.5 Novartis AG
- 6.3.6 Glenmark Pharmaceuticals
- 6.3.7 Koninklijke Philips N.V.
- 6.3.8 Propeller Health
- 6.3.9 AptarGroup Inc.
- 6.3.10 H&T Presspart Manufacturing Ltd.
- 6.3.11 Trudell Medical Group
- 6.3.12 Adherium Ltd.
- 6.3.13 ResMed Inc.
- 6.3.14 Vectura Group plc
- 6.3.15 Mundipharma International
- 6.3.16 3M Drug Delivery Systems
- 6.3.17 Cipla Ltd.
- 6.3.18 Opko Health Inc.
- 6.3.19 Amiko Digital Health
- 6.3.20 Pneuma Respiratory
- 6.3.21 FindAir
- 6.3.22 Cohero Health
- 6.3.23 BreatheSuite Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


