

|
시장보고서
상품코드
2123526
의료기기 교정 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Medical Equipment Calibration - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
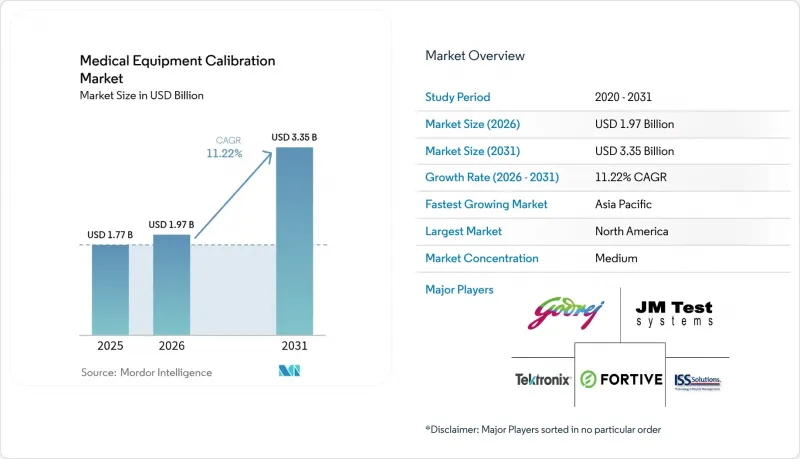
에 의하면, 의료기기 교정 시장 규모는 2026년에 19억 7,000만 달러로 추정되고 있어 2025년 17억 7,000만 달러에서 확대되어, 2031년에는 33억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 11.22%를 나타낼 것으로 전망됩니다.
본 보고서에서는 업계를 기기 유형(생체 징후 모니터, 인공호흡기, 태아 모니터 등), 서비스 유형(사내 교정 서비스 등), 최종 사용자(임상 실험실, 병원 등), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류하고 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 의료기기 교정 시장 동향 및 인사이트
엄격한 세계 규제가 교정 표준화를 촉진
규제 조화를 통해 품질 감사 및 의료기기 승인에 교정의 추적 가능성이 통합됨에 따라 의료기기 교정 시장이 확대되고 있습니다. FDA의 QMSR은 현재 ISO 13485:2016을 준수하고 있으며, 이중 규정 준수 요건으로 인한 분열을 해소하고 문서화의 깊이를 확대되고 있습니다. 유럽의 MDR 및 IVDR은 기본적인 안전 점검을 훨씬 뛰어넘는 동등한 기록 유지 의무를 부과하고 있으며, 공급업체에게 모든 교정 작업에 대한 보관 이력 기록을 유지할 것을 요구하고 있습니다. 중국 NMPA의 개혁도 유사한 규격과 조화를 이루면서 현지 임상시험 요건을 추가하고 있어, 국내 및 다국적 검사 기관에 새로운 인증 업무가 발생하고 있습니다. 규제 당국은 사이버 보안에 대한 감독도 확대하고 있으며, 미국의 지침 초안에서는 ‘사이버 기기’에 대한 소프트웨어 부품표(BOM) 제출을 요구하고 있기 때문에 교정 절차에는 보안 검증 단계가 점점 더 많이 포함되고 있습니다. 이러한 상호 연관된 규제들이 맞물리면서 조달, 서비스 계약 및 기술자 교육의 방식이 재구성되고 있습니다.
고부가가치 영상 진단 및 생명 유지 시스템 도입 대수 증가
현재 병원의 설비 투자 예산은 AI 지원 CT, MRI 및 인공호흡기 플랫폼을 중심으로 돌아가고 있습니다. Philips의 헬륨 프리 MRI 아키텍처는 운영 비용을 절감하지만, 기존의 1,500리터 자석 용기 대신 7리터 자석을 채택하고 있어 새로운 교정 프로토콜이 필요합니다. GE 헬스케어와 엔비디아(NVIDIA)의 자율형 X선 및 초음파 장치에 관한 제휴는 소프트웨어 모델에도 기계 부품과 동일한 추적성이 요구되기 때문에 교정 단계가 하나 더 추가되는 결과를 낳습니다. 이러한 혁신으로 인해 기기 유형가 증가하고, 서비스 구성이 알고리즘 검증, IoT 센서 점검, 다중 모드 성능 시험으로 전환됨에 따라 의료기기 교정 시장은 확대되고 있습니다. 신흥 생명 유지 시스템에는 실시간 피드백 루프가 내장되어 있어, 환자의 안전을 보장하고 가치 기반 서비스 계약에서 합의된 가동 시간을 유지하기 위해서는 더 빈번한 미세 조정 교정이 필요합니다.
신흥 시장의 높은 비용과 일정 관리의 복잡성
저소득 지역의 의료 시스템에서는 수명 주기 서비스보다 하드웨어 조달을 우선시하고 있습니다. 2024년에는 공급망 혼란으로 인해 물류 비용이 제조업체 매출의 최대 5%까지 상승하여, 수입된 기준 기기의 교정 비용을 끌어올렸습니다. 지리적으로 광범위하게 분포되어 있어 기술자가 서비스 수행 1일당 2일의 이동 시간이 소요될 수 있으며, 이는 정기적인 방문을 방해하고 의료기기 교정 시장의 성장을 둔화시키고 있습니다. 환율 변동은 강세 통화로 체결된 다년 계약을 더욱 복잡하게 만들고 있습니다. 이에 대응하여 주요 공급업체들은 수요를 통합하거나 Trescal과 같은 세계 기업에 지역 허브 설립을 요청하는 방식으로 대처하고 있으며, 비용 부담은 점차 완화되고 있습니다.
부문 분석
2025년, 의료기기 교정 시장의 32.78%를 영상 진단 플랫폼이 차지하고 있으며, 이는 건트리 정렬에서 선량 교정에 이르기까지 광범위한 교정 지점이 존재함을 반영합니다. 소프트웨어 개정이나 하드웨어 개조가 이루어질 때마다 서비스 수익이 서서히 증가하여 장기 계약의 기반이 되고 있습니다. 알고리즘을 활용한 영상 진단 기법에서는 기존의 기하학적 점검을 넘어 비디오 속도로 조정이 가능해지면서 그 적용 범위가 확대되고 있습니다. 대조적으로, 바이탈 사인 모니터는 재택 간호 분야로의 도입으로 인해 판매 대수가 두 배로 증가하여 13.73%의 연평균 성장률(CAGR)을 기록하고 있습니다. 거실로 배송되는 모니터 1대당, 의료기기 교정 시장은 의료 기관 외의 환경으로 확대되며 휴대용 현장 교정 키트에 대한 수요를 창출하고 있습니다. 그라디언트 프리 헬륨 MRI, AI 탑재 초음파 진단 장치, 그리고 네트워크 연결형 주입 펌프는 모두 전용 절차가 필요하기 때문에 전문가에 대한 수요를 공고히 하고 있습니다.
네트워크 연결형 기기의 급속한 보급으로 인해, 교정 대상은 현재 센서, 임베디드 펌웨어, 클라우드 API에 이르기까지 일상적으로 확대되고 있습니다. 주입 펌프는 유량의 정확도를 확보하기 위해 중량법에 의한 교정에 의존하고 있으며, 펌웨어 패치가 적용될 때마다 규정 준수 유효 기간이 재설정됩니다. 인공호흡기 교정은 팬데믹 기간 동안 주목을 받았으며, 중환자실의 중요한 안전 대책으로서 여전히 중요한 역할을 수행하고 있습니다. 수술 기구 및 검사용 분석 장비는 꾸준한 성장을 유지하고 있으며, 의료기기 교정 시장의 수익 다각화를 뒷받침하고 있습니다.
지역별 분석
북미는 ISO 13485에 대한 조기 준수와 FDA의 정기적인 감시 감사에 힘입어 2025년에는 전 세계 매출의 39.12%를 차지했습니다. 조달 팀은 계약에 ISO/IEC 17025 인증을 의무화하는 서비스 조항을 포함하고 있으며, 이로 인해 진입 장벽이 높아져 대규모 사업자가 우위를 점하고 있습니다. 캐나다의 규제 현대화와 멕시코의 수출 지향형 의료기기 생산도 이 지역에 긍정적인 요인으로 작용하고 있습니다. 북미 의료기기 교정 시장 규모는 영상 진단 시스템의 갱신, 원격 ICU 도입, 그리고 사이버 보안 규제 강화와 발맞추어 확대될 것으로 예측됩니다.
아시아태평양은 중국, 인도, 한국의 제조 거점 확대와 동남아시아 전역의 신규 병원 건설에 힘입어 연평균 성장률(CAGR) 12.14%라는 견실한 성장을 이루고 있습니다. 고급 제품의 현지 생산을 촉진하는 정부의 인센티브에 힘입어, 공급업체들은 국내에서 교정 역량을 구축하기 위해 움직이고 있으며, 국경을 초월한 합작 사업이 활성화되고 있습니다. 일본에서는 고령화에 따라 영상 진단 이용이 활발해지는 한편, ASEAN 의료기기 지침에 따라 10개국 전체에서 행정 절차가 간소화되어 벤더 시장 진입이 가속화되고 있습니다. 이러한 요인들이 복합적으로 작용하여, 해당 지역 전체에서 의료기기 교정 시장이 자리 잡아가고 있습니다.
유럽은 대규모 도입 실적과 상세한 규제 지침을 보유하고 있습니다. MDR 및 IVDR 개정에 따라 교정 대상이 방사선 진단에서 체외 진단으로 확대되면서 작업 목록이 증가하고, 서비스 계약 기간이 장기화되고 있습니다. 독일의 수출 프로젝트, 프랑스의 병원 투자, 그리고 영국의 브렉시트 이후 규제 조화를 위한 노력이 맞물려 수요는 높은 수준을 유지하고 있습니다. 지속가능성에 대한 지향으로 인해 헬륨 프리 MRI와 같은 새로운 교정 기법의 길이 열리고 있으며, 기존의 냉각 시스템이나 극저온 액체의 점검은 점차 구식이 되어가고 있습니다. 그 밖의 지역에서는 중동 및 아프리카, 남미에서 구형 장비의 교체 및 새로운 3차 의료 센터 건설이 진행됨에 따라 상대적으로 빠른 성장이 나타나고 있으나, 기술 인력 부족과 환율 리스크가 보급을 저해하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, medical equipment calibration market size market size in 2026 is estimated at USD 1.97 billion, growing from 2025 value of USD 1.77 billion with 2031 projections showing USD 3.35 billion, growing at 11.22% CAGR over 2026-2031.
This report Segments the Industry Into by Equipment Type (Vital Sign Monitors, Ventilators, Fetal Monitors, and More), Type of Service (In-House Calibration Services, and More ), End User (Clinical Laboratories, Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Equipment Calibration Market Trends and Insights
Stringent Global Regulations Drive Calibration Standardization
Regulatory harmonization elevates the medical equipment calibration market by embedding calibration traceability into quality audits and device approvals. The FDA QMSR now mirrors ISO 13485:2016, eliminating dual compliance silos and expanding documentation depth. Europe's MDR and IVDR impose comparable file-keeping obligations that reach far beyond basic safety checks and push suppliers to maintain chain-of-custody records for every calibration event. China's NMPA reforms dovetail with the same standards while adding local clinical-trial demands, creating new accreditation work for domestic and multinational laboratories. Regulators also extend oversight to cybersecurity, with draft U.S. guidance requiring a software bill of materials for "cyber devices," so calibration routines increasingly include security-verification steps. Collectively, these intertwined rules reshape procurement, service contracting, and technician training.
Growing Installed Base of High-Value Imaging & Life-Support Systems
Hospital capital budgets now revolve around AI-ready CT, MRI, and ventilator platforms. Philips' helium-free MRI architecture trims running costs yet requires new calibration protocols for a 7-liter magnet in place of traditional 1,500-liter vessels. GE HealthCare's alliance with NVIDIA for autonomous x-ray and ultrasound adds another calibration layer because software models need the same traceability as mechanical parts. These innovations multiply device variants and expand the medical equipment calibration market by shifting the service mix toward algorithm validation, IoT sensor checks, and multi-modal performance tests. Emerging life-support systems embed real-time feedback loops that demand more frequent micro-calibrations to guard patient safety and maintain uptime guarantees negotiated in value-based service contracts.
High Cost & Scheduling Complexity in Emerging Markets
Healthcare systems in lower-income regions prioritize hardware acquisition over lifecycle services. Supply-chain disruptions raised logistics costs by up to 5% of manufacturer revenue in 2024, inflating calibration expenses for imported reference instruments. Geographic sprawl means a technician may spend two travel days for every service day, which deters routine visits and dampens the medical equipment calibration market. Currency swings further complicate multiyear contracts priced in hard currencies. Large providers respond by pooling demand or inviting global firms like Trescal to set up regional hubs, slowly easing cost burdens.
Other drivers and restraints analyzed in the detailed report include:
- Preventive-Maintenance Contracts to Cut Device Downtime
- IoT-Linked Self-Diagnostic Sensors Enabling Micro-Calibration
- Scarcity of ISO/IEC 17025-Accredited Technicians
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Imaging platforms accounted for 32.78% of the medical equipment calibration market in 2025, reflecting extensive calibration touchpoints from gantry alignment to dose calibration. Each software revision and hardware retrofit drives incremental service revenue and anchors long-term contracts. Algorithmic imaging methods add video-rate adjustments that go beyond classical geometric checks, enlarging scope. Vital-sign monitors, by contrast, post a 13.73% CAGR because home-care adoption multiplies unit volume. Every monitor shipped into a living room extends the medical equipment calibration market to non-institutional settings and triggers portable field-calibration kits. Gradient-free helium MRI, AI-enabled ultrasound, and connected infusion pumps all require bespoke procedures, locking in specialist demand.
Rapid uptake of networked devices means calibration now routinely covers sensors, embedded firmware, and cloud APIs. Infusion pumps rely on gravimetric calibration for flow accuracy, and any firmware patch resets the clock on compliance. Ventilator calibration gained visibility during the pandemic and remains a critical safety hedge in intensive-care units. Surgical tools and laboratory analyzers sustain steady growth, rounding out revenue diversity within the medical equipment calibration market.
Complete Report Scope:
- By Equipment Type
- Vital Sign Monitors
- Ventilators
- Fetal Monitors
- Cardiovascular Monitors
- Imaging Equipment
- Infusion Pumps
- Other Equipment
- By Type of Service
- In-house Calibration Services
- Third-party Calibration Services
- OEM Calibration Services
- By End User
- Clinical Laboratories
- Hospitals
- Others (Home-care, Ambulatory, OEM Labs)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 39.12% of global revenue in 2025, supported by early alignment with ISO 13485 and routine FDA surveillance audits. Procurement teams embed service clauses that mandate ISO/IEC 17025 accreditation, cementing a high-entry barrier and rewarding scale operators. Canada's regulatory modernization and Mexico's export-oriented device production add regional tailwinds. The medical equipment calibration market size for North America is projected to advance in lockstep with imaging overhauls, tele-ICU rollouts, and cybersecurity mandates.
Asia-Pacific grows at a brisk 12.14% CAGR, propelled by expanding manufacturer hubs in China, India, and South Korea and by fresh hospital construction across Southeast Asia. Government incentives to localize high-end production spur suppliers to build domestic calibration capability, stimulating cross-border joint ventures. Japan's aging population drives heavy imaging utilization, while the ASEAN Medical Device Directive trims paperwork across 10 countries and speeds vendor onboarding. These factors converge to embed the medical equipment calibration market across the region.
Europe commands a large installed base and a detailed regulatory playbook. MDR and IVDR updates extend calibration from radiology into in vitro diagnostics, inflating task lists and lengthening service contracts. Germany's export pipeline, France's hospital investments, and the United Kingdom's post-Brexit alignment efforts collectively keep demand high. Sustainability preferences open space for newer calibration methods-for instance, helium-free MRI-and render traditional cooling and cryogen checks obsolete. Elsewhere, the Middle East, Africa, and South America register quicker relative growth as they retrofit outdated fleets and build new tertiary centers, though limited technician pools and currency risk temper uptake.
- Fortive
- Trescal
- GE Healthcare
- Siemens Healthineers
- Koninklijke Philips
- Transcat
- Tektronix
- JM Test Systems
- TAG Medical
- BC Group International
- Beamex
- Keysight Technologies
- JPen Medical
- NS Medical Systems
- Medserve Ltd
- Godrej Biomed
- Biomed Technologies (ISS Solutions)
- TBS Group
- Aramark Services
- Pentax Medical Services
- Rigel Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Global Regulations
- 4.2.2 Growing Installed Base of High-Value Imaging & Life-Support Systems
- 4.2.3 Preventive-Maintenance Contracts to Cut Device Downtime
- 4.2.4 IoT-Linked Self-Diagnostic Sensors Enabling Micro-Calibration
- 4.2.5 Value-Based Procurement Tying Reimbursement to Accuracy KPIs
- 4.2.6 Home/POC Devices Needing Field-Calibration Kits
- 4.3 Market Restraints
- 4.3.1 High Cost & Scheduling Complexity in Emerging Markets
- 4.3.2 Scarcity of ISO/IEC 17025-Accredited Technicians
- 4.3.3 Cyber-Security Rules Limiting Remote Calibration Access
- 4.3.4 AI Autocalibration Data-Integrity Concerns
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Equipment Type
- 5.1.1 Vital Sign Monitors
- 5.1.2 Ventilators
- 5.1.3 Fetal Monitors
- 5.1.4 Cardiovascular Monitors
- 5.1.5 Imaging Equipment
- 5.1.6 Infusion Pumps
- 5.1.7 Other Equipment
- 5.2 By Type of Service
- 5.2.1 In-house Calibration Services
- 5.2.2 Third-party Calibration Services
- 5.2.3 OEM Calibration Services
- 5.3 By End User
- 5.3.1 Clinical Laboratories
- 5.3.2 Hospitals
- 5.3.3 Others (Home-care, Ambulatory, OEM Labs)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Fortive
- 6.3.2 Trescal
- 6.3.3 GE Healthcare
- 6.3.4 Siemens Healthineers
- 6.3.5 Philips Healthcare
- 6.3.6 Transcat
- 6.3.7 Tektronix
- 6.3.8 JM Test Systems
- 6.3.9 TAG Medical
- 6.3.10 BC Group International
- 6.3.11 Beamex
- 6.3.12 Keysight Technologies
- 6.3.13 JPen Medical
- 6.3.14 NS Medical Systems
- 6.3.15 Medserve Ltd
- 6.3.16 Godrej Biomed
- 6.3.17 Biomed Technologies (ISS Solutions)
- 6.3.18 TBS Group
- 6.3.19 Aramark Services
- 6.3.20 Pentax Medical Services
- 6.3.21 Rigel Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


