

|
시장보고서
상품코드
2123531
다형성교모세포종(GBM) 치료 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Glioblastoma Multiforme Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
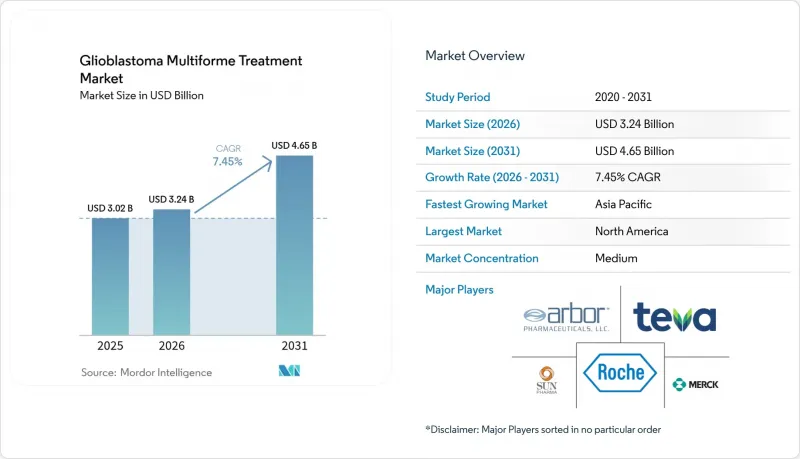
에 의하면, 2026년 다형성교모세포종(GBM) 치료 시장 규모는 32억 4,000만 달러로 추정되고 있어 2025년 30억 2,000만 달러에서 확대되어, 2031년에는 46억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR)은 7.45%를 나타낼 것으로 전망됩니다.
본 보고서는 치료법(화학요법, 방사선 요법 등), 환자 유형(신규 진단 GBM, 재발성 GBM), 최종 사용자(병원 및 진료소 등), 연령대(성인, 소아, 고령자) 및 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 다형성교모세포종 치료 시장 동향 및 인사이트
고악성도 신경교종의 발병률 증가
환자 수 동향에 따라 다형성교모세포종 치료 시장은 견조한 성장세를 유지하고 있습니다. 다형성교모세포종은 이미 전 세계 악성 원발성 뇌종양의 거의 절반을 차지하고 있으며, 진단에 대한 인식이 높아짐에 따라 더 많은 환자가 질병의 초기 단계에서 치료 과정에 포함되고 있습니다. 주요 학술 기관의 신경종양학 부서는 이러한 환자 수 증가에 대응하기 위해 규모를 확대하고 있으며, 이는 승인된 의약품, TTFields 기기 및 관련 진단제에 대한 예측 가능한 수요를 창출하고 있습니다. 사례 수 증가는 임상시험에 대한 피험자 등록을 가속화하여 차세대 치료법의 개발 주기를 단축시키고 있습니다. 제약 기업들은 대상 환자층의 확대를 배경으로, 추가적인 혁신의 자금원이 될 프리미엄 가격 전략을 정당화하고 있습니다.
확대되는 연구개발 파이프라인과 희귀질환 치료제(오펀 드럭)에 대한 인센티브
미국 및 EU 규정에 따른 패스트트랙 지정과 희귀질환 치료제 지정은 비용과 시장 출시까지의 시간을 단축시켜, 교모세포종을 기존에는 매력이 부족했던 틈새 분야에서 상업적 우선 분야로 탈바꿈시키고 있습니다. 악성 신경교종에 대한 ERAS-801의 FDA 희귀질환 의약품 승인 및 볼라시데닙에 대한 신속 승인 절차는 미충족 의료 수요가 높은 경우 규제 당국이 대체 평가 지표를 수용할 의향이 있음을 보여줍니다. 이러한 지정에 따른 독점 판매 기간을 통해 기업은 환자 수가 적다는 점과 관련된 위험을 상쇄할 수 있는 수익 보호를 얻을 수 있습니다. 이러한 환경은 국경을 초월한 라이선싱 계약, 테모졸로미드 내성을 극복하기 위한 머크사의 Modifi Biosciences 인수와 같은 대형 제약사의 인수를 촉진하고 있습니다.
신규 의료기기에 대한 엄격한 보험 급여 기준
의료 기술 평가 기관은 보험 적용을 승인하기 전에 실제 환경에서의 비용 대비 효과에 대한 증거를 점점 더 요구하고 있습니다. TTFields의 경우, 보험사는 종종 입원 건수 감소나 이상반응 관리 비용 절감을 보여주는 시판 후 조사를 요구합니다. 규제 당국의 승인부터 최종 보험 적용 결정까지 12-24개월의 지연이 발생함에 따라 수익 창출까지의 과정이 길어지고, 의료기기 제조업체의 자금 사정이 시험대에 오르고 있습니다. 재무적 위험을 제조업체에 전가하는 성과 연동형 계약이 유럽에서 표준화되고 있어, 소규모 신규 진출기업에게는 시장 진입 장벽이 높아지고 있습니다.
부문별 분석
2025년에는 제네릭 테모졸로미드가 1차 선택 프로토콜의 기반으로 남아 있는 가운데, 화학요법이 총 수익의 46.65%를 차지했습니다. 2031년까지 TTFields 요법의 연평균 성장률(CAGR) 8.62%는 전신 부작용을 피하는 기기 중심의 접근법에 대한 임상의들의 신뢰가 높아지고 있음을 보여줍니다. 양성자 치료를 포함한 방사선 치료는 국소 제어에 있어 여전히 필수적이지만, 계속 확대되고 있는 ‘기타’ 범주에는 중기 임상시험 단계에 있는 백신, 방사성 의약품 및 면역 요법의 병용 요법이 포함됩니다. 시장 진출기업들은 치료법 조합을 점점 더 적극적으로 추진하고 있으며, 노보큐어(Novocure)와 MSD는 등록 임상시험에서 TTFields와 펨브롤리주맙의 병용 요법을 평가했습니다. 이는 지속적인 생존을 위해서는 다각적인 치료 접근법이 필요하다는 공통된 인식을 반영한 것입니다.
치료법 조합의 변화는 공급망과 보험 지급 모델에 영향을 미치고 있습니다. TTFields 시스템은 일회성 약물 주입과 달리, 구독형 소모품 수요를 창출합니다. 새로운 병용 요법이 승인됨에 따라 임상 경로에는 순차적 또는 병행적인 치료 요법이 통합되어 복잡성은 증가하겠지만, 대상 지출 규모는 확대될 것입니다. 의료기기와 약물의 비용 효율적인 통합을 입증한 개발 기업은 압도적인 시장 점유율을 확보하게 될 것입니다.
2025년에는 신규 진단 사례가 매출의 67.92%를 차지할 것으로 전망됩니다. 이는 신규 발병 환자 수 증가와 Stupp 프로토콜의 보급이 배경에 있습니다. 그러나 재발 사례 부문의 2031년까지 연평균 성장률(CAGR) 8.55%는 혁신의 최전선이 어디에 있는지 보여줍니다. Alpha DaRT사가 실시한 라듐-224 요법과 RRx-001의 병용 프로토콜에 관한 FDA 지원 파일럿 임상시험은 구제 치료 현장에서의 적극적인 실험의 초기 사례입니다.
재발 사례에 대한 관심이 높아짐에 따라 소규모의 적응형 임상시험 설계가 촉진되어, 개발 기간 단축 및 자금 요건 감소로 이어지고 있습니다. 이러한 특징들은 바이오테크 기업에 대한 벤처 자금과 대형 제약 회사와의 옵션 계약을 유치하고 있으며, 테모졸로미드 내성을 해결하기 위해 머크(Merck)가 Modifi Biosciences를 인수한 사례가 이를 뒷받침하고 있습니다. 이 분야에서 성공을 거둔다면, 병용 요법의 확대를 통해 1차 치료의 표준으로 자리 잡게 될 것이며, 재발 사례와 신규 진단 사례 간의 치료 알고리즘 연계가 확립될 것입니다.
지역별 분석
북미는 메디케어 및 민간 보험사가 TTFields와 최신 화학요법제의 비용을 상환하고 있을 뿐만 아니라, 600개 이상의 임상 센터가 임상시험 인프라를 제공하고 있어 매출의 39.75%를 차지하고 있습니다. 규제의 명확성과 희귀질환 치료제(오펀 드럭)에 대한 우대 조치가 파이프라인 자산의 신속한 시장 출시를 뒷받침하고 있으며, 이 지역의 탄탄한 벤처 캐피탈 생태계가 초기 단계의 혁신에 자금을 지원하고 있습니다. 종합적인 신경종양학 프로그램에서는 수술, 방사선 치료, 의료기기 및 약물 임상시험이 결합되어 있으며, 미국은 새로운 치료법 도입에 있어 기준 시장으로서의 입지를 확립하고 있습니다.
유럽은 지역별 기준으로 두 번째로 큰 시장 기회를 지니고 있으나, 비용 대비 효과 기준이 마련되어 있으며 엄격한 의료 기술 평가가 의무화되어 있습니다. 독일은 치료가 어려운 암에 대한 수지상 세포 치료의 보험 적용을 선도적으로 도입하여, 고부가가치 치료법에 대해 선택적인 개방적 태도를 보이고 있습니다. 유럽의약품청(EMA)의 중앙 집중 심사 절차에 따라 판매 승인은 신속해지고 있지만, 보험 적용은 여전히 국가마다 다르기 때문에 널리 보급되기까지 시간이 오래 걸리고 있습니다. 개발 기업은 생존율이나 삶의 질(QOL) 지표를 바탕으로 지불을 결정하는 성과 연동형 계약에 대응해야 합니다.
아시아태평양은 연평균 성장률(CAGR) 8.8%로 가장 빠르게 성장하는 시장입니다. 각국 정부는 정밀의료 인프라 구축에 투자하고 있으며, 주요 종양 전문 병원에서는 고도의 뇌신경외과 수술에 대응할 수 있는 수술실 구축이 진행되고 있습니다. 일본에서는 국내 임상 데이터를 통해 유효성이 입증된 경우, 국민건강보험 제도를 통해 고액 치료에 대한 자금 지원이 확대되고 있으며, 중국에서는 집중형 일괄 조달 이니셔티브에 신경종양학용 의료기기가 서서히 포함되기 시작하고 있습니다. 현지 제조업체들이 TTFields 및 나노입자 분야에 진출함에 따라 가격 경쟁이 촉진되어 더 광범위한 접근이 가능해지고 있습니다. 다국적 기업들은 지역 계약 연구 기관(CRO)과 제휴하여 아시아 주요 시장에서 승인을 신속히 얻기 위한 적응형 임상시험을 실시했습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, glioblastoma multiforme treatment market size in 2026 is estimated at USD 3.24 billion, growing from 2025 value of USD 3.02 billion with 2031 projections showing USD 4.65 billion, growing at 7.45% CAGR over 2026-2031.
This report is Segmented by Treatment Modality (Chemotherapy, Radiation Therapy, and More), Patient Type (Newly Diagnosed GBM, Recurrent GBM), End User (Hospitals and Clinics, and More), Age Group (Adults, Pediatric, Geriatric), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Glioblastoma Multiforme Treatment Market Trends and Insights
Escalating Incidence of High-Grade Gliomas
Incidence trends keep the glioblastoma multiforme treatment market on a firm growth footing. Glioblastoma already represents nearly half of all malignant primary brain tumors worldwide, and rising diagnostic awareness is bringing more patients into care pathways earlier in their disease course. Neuro-oncology units at major academic centers are scaling to meet these volumes, creating predictable demand for approved drugs, TTFields devices, and related diagnostics. Higher case numbers also accelerate clinical-trial enrollment, shortening development cycles for next-generation therapies. Manufacturers leverage the larger addressable population to justify premium pricing strategies that fund further innovation.
Expanding R&D Pipelines and Orphan-Drug Incentives
Fast-track and orphan designations under U.S. and EU regulations reduce both cost and time-to-market, transforming glioblastoma from a historically unattractive niche into a commercial priority. The FDA's orphan approval of ERAS-801 for malignant glioma and the swift clearance pathway for vorasidenib demonstrate regulators' willingness to accept surrogate endpoints when unmet need is high. Exclusivity periods that follow such designations provide companies with revenue protection that offsets the risks associated with small patient populations. The environment is catalyzing cross-border licensing deals and big-pharma acquisitions, such as Merck's purchase of Modifi Biosciences, targeted at overcoming temozolomide resistance .
Stringent Reimbursement Hurdles for Novel Devices
Health-technology assessment bodies increasingly demand real-world cost-benefit evidence before granting coverage. For TTFields, payers often require post-market studies showing reductions in hospitalizations and adverse-event management costs. Delays of 12-24 months between regulatory clearance and final reimbursement decisions prolong the path to revenue, testing the liquidity of device firms. Outcome-based contracts that shift financial risk to manufacturers are becoming standard in Europe, raising hurdles for smaller entrants.
Other drivers and restraints analyzed in the detailed report include:
- Growing Adoption of Tumor-Treating Fields (TTFields) Devices
- Venture Funding Surge for BBB-Penetrating Nanocarriers
- Temozolomide Resistance and MGMT Heterogeneity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Chemotherapy generated 46.65% of total revenue in 2025 as generic temozolomide continues to anchor frontline protocols. TTFields therapy's 8.62% CAGR to 2031 signals accelerating clinician confidence in a device-centric approach that avoids systemic side effects. Radiation, including proton techniques, remains critical for local control, while a growing "others" basket contains vaccine, radiopharmaceutical, and immunotherapy combinations that are moving through mid-phase trials. Market participants increasingly bundle modalities: Novocure and MSD are evaluating TTFields plus pembrolizumab in registrational studies, reflecting consensus that multimodal attack is necessary for durable survival.
The treatment-mix shift influences supply chains and reimbursement models. TTFields systems create subscription-style consumables demand, distinct from one-time drug infusions. As new combinations reach approval, clinical pathways will feature sequential or concurrent regimens, adding complexity but enlarging the addressable spend. Developers that prove cost-effective integration of devices with drugs will capture outsized share.
Newly diagnosed cases dominated with 67.92% revenue in 2025, driven by the larger incident population and accepted Stupp protocol adoption. Yet the recurrent segment's 8.55% CAGR to 2031 illustrates where the innovation frontier lies. Alpha DaRT's FDA-supported pilot trial of radium-224 therapy and RRx-001 combination protocols are early examples of aggressive experimentation in salvage settings.
The recurrent focus encourages smaller, adaptive study designs, shortening timelines and reducing capital requirements. These features attract biotech venture funding and big-pharma option deals, as demonstrated by Merck's acquisition of Modifi Biosciences to tackle temozolomide resistance. Success here will likely ripple into frontline standards through combination expansion, closing the loop between recurrent and newly diagnosed care algorithms.
Complete Report Scope:
- By Treatment Modality
- Chemotherapy
- Radiation Therapy
- Tumor-Treating Fields
- Others
- By Patient Type
- Newly Diagnosed GBM
- Recurrent GBM
- By End User
- Hospitals and Clinics
- Ambulatory Surgical Centers
- Others
- By Age Group
- Adults
- Pediatric
- Geriatric
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America holds 39.75% of revenue because Medicare and private insurers reimburse TTFields and the latest chemotherapeutic agents, while more than 600 clinical centers provide trial infrastructure. Regulatory clarity and orphan-drug benefits encourage rapid launch of pipeline assets, and the region's dense venture-capital ecosystem funds early-stage innovation. Comprehensive neuro-oncology programs combine surgery, radiation, devices, and drug trials, positioning the United States as the reference market for new therapy rollouts.
Europe represents the second-largest regional opportunity but employs cost-effectiveness thresholds that mandate rigorous health-technology assessments. Germany has pioneered dendritic-cell therapy reimbursement for difficult-to-treat cancers, signaling selective openness to premium interventions. The European Medicines Agency's centralized procedure expedites marketing authorization, yet reimbursement remains country specific, lengthening time to broad uptake. Developers must navigate outcome-based agreements that align payment with survival or quality-of-life metrics.
Asia-Pacific is the fastest-growing territory at 8.8% CAGR. Governments are investing in precision-medicine infrastructures, and major oncology hospitals are equipping operating suites for advanced neurosurgery. Japan's universal coverage system increasingly funds high-cost therapies when domestic clinical data demonstrate benefit, and China's centralized volume-based procurement initiatives are beginning to include neuro-oncology devices. Local manufacturers are entering the TTFields and nanoparticle spaces, thereby driving competitive pricing and broader access. Multinational firms partner with regional contract research organizations to run adaptive trials that expedite approval in key Asian markets.
- Arbor Pharmaceuticals
- Bristol-Myers Squibb
- Eli Lilly and Company
- Roche
- Merck
- Sun Pharmaceuticals Industries
- Lantern Pharma Inc.
- Pfizer
- Amgen
- Teva Pharmaceutical Industries
- Novocure Ltd
- Celldex Therapeutic
- AstraZeneca
- GlaxoSmithKline
- Novartis
- Kazia Therapeutics Ltd
- Northwest Biotherapeutics Inc.
- Kintara Therapeutics Inc.
- Bluebird bio Inc.
- DelMar Pharmaceuticals (Chimerix)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Incidence of High-Grade Gliomas
- 4.2.2 Age-Associated Rise in GBM Cases
- 4.2.3 Expanding R&D Pipelines & Orphan-Drug Incentives
- 4.2.4 Growing Adoption of Tumor-Treating Fields (Ttfields) Devices
- 4.2.5 AI-Enabled Radiogenomics Improving Early Detection
- 4.2.6 Venture Funding Surge For BBB-Penetrating Nanocarriers
- 4.3 Market Restraints
- 4.3.1 Stringent Reimbursement Hurdles for Novel Devices
- 4.3.2 High Therapy Cost Burden & Limited Cost-Effectiveness in Lmics
- 4.3.3 Temozolomide Resistance & MGMT Heterogeneity
- 4.3.4 Low Real-World Compliance with Ttfields Therapy
- 4.4 Regulatory Landscape
- 4.5 Porters Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Treatment Modality
- 5.1.1 Chemotherapy
- 5.1.2 Radiation Therapy
- 5.1.3 Tumor-Treating Fields
- 5.1.4 Others
- 5.2 By Patient Type
- 5.2.1 Newly Diagnosed GBM
- 5.2.2 Recurrent GBM
- 5.3 By End User
- 5.3.1 Hospitals and Clinics
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Others
- 5.4 By Age Group
- 5.4.1 Adults
- 5.4.2 Pediatric
- 5.4.3 Geriatric
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 Arbor Pharmaceuticals LLC
- 6.3.2 Bristol-Myers Squibb Co.
- 6.3.3 Eli Lilly and Co.
- 6.3.4 F. Hoffmann-La Roche Ltd
- 6.3.5 Merck & Co. Inc.
- 6.3.6 Sun Pharmaceutical Industries Ltd
- 6.3.7 Lantern Pharma Inc.
- 6.3.8 Pfizer Inc.
- 6.3.9 Amgen Inc.
- 6.3.10 Teva Pharmaceutical Industries Ltd
- 6.3.11 Novocure Ltd
- 6.3.12 Celldex Therapeutics Inc.
- 6.3.13 AstraZeneca plc
- 6.3.14 GlaxoSmithKline plc
- 6.3.15 Novartis AG
- 6.3.16 Kazia Therapeutics Ltd
- 6.3.17 Northwest Biotherapeutics Inc.
- 6.3.18 Kintara Therapeutics Inc.
- 6.3.19 Bluebird bio Inc.
- 6.3.20 DelMar Pharmaceuticals (Chimerix)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessmen


