|
시장보고서
상품코드
2123579
경카테터 폐동맥판 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Transcatheter Pulmonary Valve - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
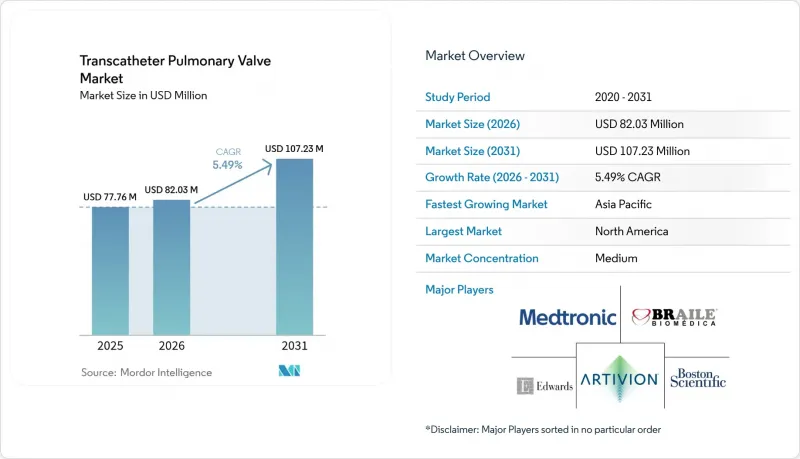
에 의하면, 세계의 경카테터 폐동맥판 시장 규모는 2025년에 7,776만 달러로 평가되었고, 2026년 8,203만 달러에서 2031년까지 1억 723만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.49%를 나타낼 전망입니다.
본 보고서는 기술별(풍선 확장형 판막 및 자가 확장형 판막), 적응증별(폐동맥 협착, 폐동맥 역류, 기타), 최종 사용자별(소아 병원, 폐동맥 역류, 기타), RVOT의 해부학적 특징별(도관 기반 RVOT 및 자가 RVOT·확장형 RVOT), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 경카테터 폐동맥판막 시장 동향 및 인사이트
성인 선천성 심장병(CHD) 생존자 수 증가
현재, 미국에서 선천성 심장 질환을 앓고 있는 성인의 수는 100만 명을 초과하며, 그 중 20%는 복잡한 심장 재시술이 필요합니다. 입원율은 91%로 높으며, 1회 입원당 평균 비용은 8만 1,332달러로, 선천성 심장병 이외의 심부전 치료 비용인 4만 9,000달러에 비해 고가이기 때문에 보험사들은 침습성이 낮은 치료법의 채택을 권장하고 있습니다. 장기적인 조직 내구성(8년 동안 99.3%에서 구조적 열화가 관찰되지 않음)은 기기의 긴 수명에 대한 기대를 뒷받침합니다. 이러한 인구 통계학적 추세로 인해 선진국 시장 전체에서 지속적인 환자 수가 확보될 것입니다.
자가 팽창형 TPV 플랫폼의 신속한 승인
미국 환자 243명을 대상으로 한 다기관 공동 등록 데이터에 따르면, 1년 후 추적 조사에서 98%에서 허용 가능한 혈역학이 확인되었으며, 99%에서 주요 복합 사건의 비발생이 확인되었습니다. 영국 규제 당국은 CE 마크 취득이 보류 중임에도 불구하고 Venus P-valve에 대해 예외적인 승인을 부여했습니다. 이는 미충족 의료 수요에 대응하는 솔루션을 신속하게 승인할 준비가 되어 있음을 시사합니다. 큰 우심실 유출로(RVOT) 해부학적 구조 내에서도 확실하게 삽입할 수 있는 능력 덕분에, 적용 가능한 임상 사례 수가 사실상 두 배로 늘어납니다.
내구성과 엄격한 시판 후 조사
FDA 등록 자료에 따르면, Melody 이식과 관련하여 스텐트 파편에 의한 색전증을 포함한 631건의 이상 반응이 기록되었습니다. 소아 코호트에서 10년간의 기능 부전 발생률은 53%에 그쳤으며, 규제 당국에서는 내구성에 대한 정의의 통일성을 요구하고 있습니다. RESILIA 조직은 8년간의 내구성에 있어 유망한 결과를 보여주고 있지만, 폐동맥 내 위치 결정에 관한 증거는 여전히 초기 단계에 있습니다.
부문 분석
세계 매출은 풍선 확장형 기기에 의해 주도되고 있으며, 2025년에는 경카테터 폐동맥 판막 시장 점유율의 57.62%를 차지했습니다. 정확한 도관 크기 선정, 즉각적인 고정, 견고한 장기 데이터가 임상의들의 신뢰를 뒷받침하고 있습니다. 에드워즈(Edwards)사의 SAPIEN 3 시스템은 1년 시점에서 기기 성공률 98.1%, 외과적 재시술 없음 비율 100%를 달성했습니다. 한편, 자가 팽창형 솔루션은 2031년까지 연평균 성장률(CAGR) 11.92%로 성장하고 있으며, 확장된 우심실 유출로(RVOT)의 해부학적 구조에 대한 치료 가능성을 혁신하고 있습니다. 1년간의 레지스트리 추적 조사에서 96%의 사례에서 복합 사건이 발생하지 않았으며, 98%의 사례에서 허용 가능한 혈역학이 확인되었습니다. ‘Venus P-valve’와 ‘Harmony’ 시스템은 현재 각각 아시아와 북미의 치료 알고리즘의 핵심을 이루고 있으며, CE 인증 획득을 통해 더욱 널리 보급되고 있습니다.
2025년 시술 건수의 45.02%는 폐동맥 역류가 차지한 것으로 평가되었으며, 이는 기존에 용적 부하 교정에 중점을 두어 왔음을 반영합니다. 그럼에도 불구하고, 폐동맥 협착의 적응증은 연평균 성장률(CAGR) 10.67%를 나타낼 것으로 예측되며, 이는 경카테터 폐동맥판막 시장 내에서 가장 강력한 성장 궤적을 보여주고 있습니다. 특히 파로우 4징후증 교정술을 받은 환자에서 우심실 기능 부전을 미연에 방지하기 위한 조기 중재 전략이 이러한 성장 가속화의 기반이 되고 있습니다. COMPASS 등의 비교 연구를 통해 최적의 시술 시기 및 치료법 선택이 명확해짐에 따라, 협착 관련 수술 건수가 증가할 가능성이 있습니다.
지역별 분석
북미는 첨단 의료시설, 보험사의 광범위한 지원, 활발한 임상시험 파이프라인에 힘입어 2025년에는 전 세계 매출의 38.30%를 차지했습니다. CMS의 외래 진료비 2.9% 인상 및 새로운 의료기기 카테고리 인증에 힘입어 카테터실 내 도입이 가속화되고 있습니다. 캐나다와 멕시코에서는 국경을 넘는 연수 및 지역별 임상 연구를 바탕으로 전문의 역량 강화가 진행되고 있습니다.
유럽은 성숙한 인프라와 입증된 수요가 있는 의료기기의 승인을 신속히 처리하려는 유연한 규제 당국의 지원에 힘입어 한 자릿수 중반의 성장률을 유지하고 있습니다. 영국에서 Venus P-valve에 대한 특별 승인은 수요 주도형 유연성을 여실히 보여주고 있습니다. 스페인의 의료경제학 연구에서는 QALY당 6,952유로라는 양호한 결과가 나타나 보험사의 신뢰를 강화하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 10.44%를 기록하며 지역별 가장 빠른 성장세를 보이고 있습니다. Venus Medtech와 같은 현지 혁신 기업들은 중국과 인도의 인구에서 흔히 나타나는 해부학적 특성에 맞추어 자가 팽창형 판막을 맞춤 제작하고 있습니다. 일본에서는 경카테터 대동맥판막 치환술의 사례 수가 8,000건을 넘어, 폐동맥 적용을 위한 시술 지침으로 자리 잡고 있습니다. 한국과 호주에서 심장 카테터 검사실 확충을 위해 정부가 추진한 정책이 추가적인 보급을 뒷받침하고 있습니다.
남미와 중동 및 아프리카는 다른 지역에 비해 뒤처져 있지만, 발표 체계가 성숙해짐에 따라 관심이 높아지고 있습니다. 전 세계 의료기기 제조업체와의 제휴 및 유럽 의료센터와의 연수 교류를 통해 시술 수행 체계가 점차 갖춰지고 있습니다. 특히 소아 선천성 심장병(CHD)에 대한 보험 적용 범위의 단계적 확대에 힘입어, 2030년까지 경카테터 폐동맥판막 시장에서 규모는 작지만 꾸준한 시장 점유율을 확보할 것으로 예측됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the global transcatheter pulmonary valve market size was valued at USD 77.76 million in 2025 and estimated to grow from USD 82.03 million in 2026 to reach USD 107.23 million by 2031, at a CAGR of 5.49% during the forecast period (2026-2031).
This report is Segmented by Technology (Balloon-Expanded Valve and Self-Expanded Valve), Application (Pulmonary Stenosis, Pulmonary Regurgitation, and More), End-User (Pediatric Hospitals, Pulmonary Regurgitation, and More), RVOT Anatomy (Conduit-Based RVOT and Native / Enlarged RVOT), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Transcatheter Pulmonary Valve Market Trends and Insights
Rising Adult-Survivor CHD Population
Adults living with congenital heart defects now exceed 1 million in the United States, 20% of whom require complex cardiac re-interventions. Hospitalizations are 91% higher and average USD 81,332 per stay versus USD 49,000 for non-congenital heart failure, incentivizing payers to endorse less invasive options. Strong long-term tissue durability-99.3% freedom from structural deterioration over eight years-supports device longevity expectations. The demographic trajectory ensures persistent case flow across developed markets.
Rapid Approvals of Self-Expanding TPV Platforms
Multicenter registry data covering 243 U.S. patients recorded 98% acceptable hemodynamics and 99% freedom from major composite events at one-year follow-up. UK regulators granted exceptional approval for the Venus P-valve despite a pending CE mark, signaling readiness to fast-track solutions addressing unmet needs. Ability to land securely in large native RVOT anatomies effectively doubles the clinical universe.
Durability and Strict Post-Market Surveillance
FDA registries logged 631 adverse events for Melody implants, including stent fragment embolization. Ten-year freedom from dysfunction sits at 53% in pediatric cohorts, driving regulatory calls for harmonized durability definitions. Although RESILIA tissue shows encouraging eight-year durability, pulmonary positioning evidence remains early stage.
Other drivers and restraints analyzed in the detailed report include:
- Patient and Clinician Shift to Minimally Invasive Therapies
- Investment Surge from Leading Med-Tech Strategics
- Endocarditis Uptick Triggering Caution in Key Centers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Global revenue remains anchored by balloon-expandable devices, which commanded 57.62% of the transcatheter pulmonary valve market share in 2025. Precise conduit sizing, immediate anchoring, and robust long-term data sustain clinician confidence. The Edwards SAPIEN 3 system achieved 98.1% device success and 100% freedom from surgical reintervention at one year. At the same time, self-expanding solutions are advancing at 11.92% CAGR through 2031, transforming therapeutic possibilities for enlarged native RVOT anatomies. One-year registry follow-up showed 96% freedom from composite events with acceptable hemodynamics in 98% of cases. The Venus P-valve and Harmony systems now anchor treatment algorithms in Asia and North America respectively, with CE certification further broadening access.
Pulmonary regurgitation generated 45.02% of 2025 procedure volume, reflecting historical focus on volume-overload correction. Nonetheless, pulmonary stenosis indications are forecast to post a 10.67% CAGR, the strongest trajectory within the transcatheter pulmonary valve market. Earlier intervention strategies that aim to pre-empt right-ventricular compromise underpin this acceleration, especially for repaired Tetralogy of Fallot patients. Comparative trials such as COMPASS will clarify optimal timing and modality selection, potentially increasing stenosis-related volumes.
Complete Report Scope:
- By Technology
- Balloon-Expandable Valve
- Self-Expanding Valve
- By Application
- Pulmonary Stenosis
- Pulmonary Regurgitation
- Tetralogy-of-Fallot Post-Repair
- Others
- By End-User
- Pediatric Hospitals
- Adult Congenital Heart Centers
- Ambulatory Surgical Centers
- By RVOT Anatomy
- Conduit-Based RVOT
- Native / Enlarged RVOT
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Rest of the World
- North America
Geography Analysis
North America generated 38.30% of global revenue in 2025, buoyed by advanced centers, widespread payer support, and active clinical-trial pipelines. CMS's 2.9% outpatient payment hike and new device categories accelerate catheter-lab uptake. Canada and Mexico are scaling specialist capabilities, supported by cross-border training and regional clinical studies.
Europe sustains mid-single-digit growth, underpinned by mature infrastructure and adaptable regulators willing to expedite devices with demonstrable need. Exceptional UK approval of Venus P-valve underscores demand-driven flexibility. Health-economic studies from Spain showed favorable EUR 6,952 per QALY, reinforcing payer confidence.
Asia-Pacific represents the fastest regional expansion at 10.44% CAGR. Domestic innovators such as Venus Medtech tailor self-expanding valves for prevalent anatomical features in Chinese and Indian populations. Japan's registry exceeding 8,000 transcatheter aortic cases provides a procedural blueprint for pulmonary adoption. Government initiatives to expand cardiac catheterization labs in South Korea and Australia further catalyze uptake.
South America and the Middle East & Africa trail but show rising interest as referral pathways mature. Partnerships with global device makers and training exchanges with European centers are improving procedural readiness. Incremental gains in reimbursement coverage, especially for pediatric CHD, are expected to translate into a steady but smaller share of the transcatheter pulmonary valve market by 2030.
- Medtronic
- Edward Lifesciences
- Boston Scientific
- Abbott Laboratories
- Venus MedTech (Hangzhou) Inc.
- Artivion, Inc.
- Jenavalve Technology
- LivaNova
- Braile Biomedica
- PolyVascular Inc.
- Xeltis AG
- MicroPort CardioFlow Medtech Corp.
- Terumo
- Meril Life Sciences Pvt Ltd (MyVal)
- T&N Medical (Pulsta Valve)
- Lepu Medical
- BIOTRONIK
- Peijia Medical Ltd.
- OrbusNeich Medical Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adult-Survivor CHD Population
- 4.2.2 Rapid Approvals Of Self-Expanding TPV Platforms
- 4.2.3 Patient & Clinician Shift To Minimally-Invasive Therapies
- 4.2.4 Investment Surge From Leading Med-Tech Strategics
- 4.2.5 Expansion Of Outpatient Cath-Lab Reimbursement Codes
- 4.3 Market Restraints
- 4.3.1 Durability & Strict Post-Market Surveillance
- 4.3.2 Surgical Alternatives (Ross, Homografts) Remain Viable
- 4.3.3 Endocarditis Uptick Triggering Caution In Key Centers
- 4.4 Porter's Five Forces
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Technology
- 5.1.1 Balloon-Expandable Valve
- 5.1.2 Self-Expanding Valve
- 5.2 By Application
- 5.2.1 Pulmonary Stenosis
- 5.2.2 Pulmonary Regurgitation
- 5.2.3 Tetralogy-of-Fallot Post-Repair
- 5.2.4 Others
- 5.3 By End-User
- 5.3.1 Pediatric Hospitals
- 5.3.2 Adult Congenital Heart Centers
- 5.3.3 Ambulatory Surgical Centers
- 5.4 By RVOT Anatomy
- 5.4.1 Conduit-Based RVOT
- 5.4.2 Native / Enlarged RVOT
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Rest of the World
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Medtronic PLC
- 6.3.2 Edwards Lifesciences Corporation
- 6.3.3 Boston Scientific Corporation
- 6.3.4 Abbott Laboratories
- 6.3.5 Venus MedTech (Hangzhou) Inc.
- 6.3.6 Artivion, Inc.
- 6.3.7 JenaValve Technology, Inc.
- 6.3.8 LivaNova PLC
- 6.3.9 Braile Biomedica
- 6.3.10 PolyVascular Inc.
- 6.3.11 Xeltis AG
- 6.3.12 MicroPort CardioFlow Medtech Corp.
- 6.3.13 Terumo Corporation
- 6.3.14 Meril Life Sciences Pvt Ltd (MyVal)
- 6.3.15 T&N Medical (Pulsta Valve)
- 6.3.16 Lepu Medical Technology Co., Ltd.
- 6.3.17 Biotronik SE & Co. KG
- 6.3.18 Peijia Medical Ltd.
- 6.3.19 OrbusNeich Medical Group
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment