|
시장보고서
상품코드
2123595
쿨링 패브릭 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cooling Fabrics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
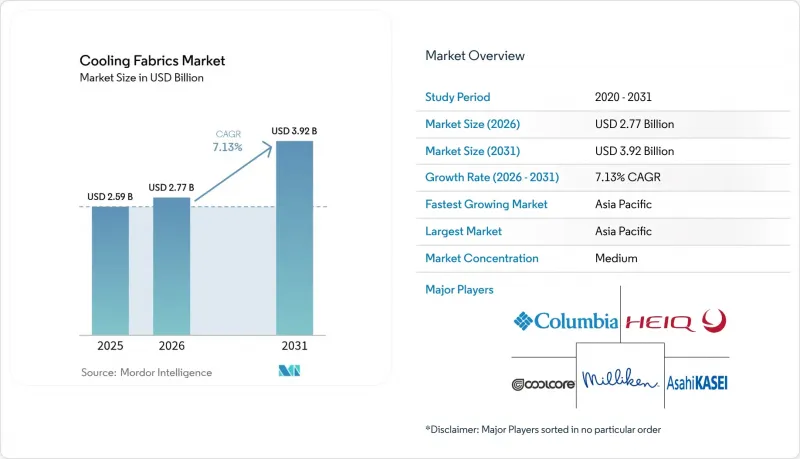
에 의하면, 2026년 쿨링 패브릭 시장 규모는 27억 7,000만 달러로 추정되고, 2025년 25억 9,000만 달러에서 확대해, 2031년에는 39억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 7.13%가 될 것으로 전망됩니다.
본 보고서는 섬유 유형별(천연섬유 및 합성 섬유), 원단 구조별(직물, 니트, 부직포), 용도별(스포츠웨어, 보호복, 기타), 최종 사용자 산업별(일반 소비자, 산업 및 제조, 헬스케어, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 쿨링 패브릭 시장 동향 및 인사이트
스포츠 및 애슬레저용 합성 흡습발산 섬유의 급증
애슬레저 및 고성능 스포츠웨어 분야에서 동적 냉각 기능은 이제 기본적인 요건으로 요구되고 있습니다. 각 브랜드는 상변화 물질이나 미세 광물을 배합한 ‘COOLMAX EcoMade’나 ‘brrr°’, 또는 이에 필적하는 원사를 채택하여 심한 발한 시에도 지속적인 열 제거를 실현하고 있습니다. 피트니스 및 아웃도어 레크리에이션에 대한 전 세계적인 참여가 시장 침투를 뒷받침하고 있으며, 합성 섬유는 안정적인 흡습발산성, 신축성, 기계적 내구성을 제공하기 때문에 여전히 시장을 독점하고 있습니다. 테크니컬 텍스타일의 발전으로 인해 전 세계 섬유 수요에서 합성 원사의 점유율은 19%를 넘어섰으며, 쿨링 패브릭 시장을 뒷받침하는 규모의 경제가 더욱 강화되고 있습니다. 나노 하이브리드 충전재로 인해 열전도율이 향상됨에 따라, 엔지니어링 합성섬유는 많은 천연 소재를 능가하는 성능을 발휘하고 있습니다. 동시에, 재생 폴리에틸렌 테레프탈레이트(PET)공급으로 비용 기반이 안정화되는 한편, 점점 더 엄격해지는 친환경 설계 규정에도 대응하고 있습니다.
전 세계 아웃도어 및 퍼포먼스 의류 브랜드의 확대
다국적 아웃도어 브랜드들은 독자적인 냉각 플랫폼을 백컨트리용 라인과 일상적인 도시 생활용 라인 모두에 적용하고 있습니다. 콜롬비아 스포츠웨어의 ‘옴니히트 인피니티’와 ‘옴니쉐이드’ 기술은 이러한 크로스오버의 좋은 예입니다. 열을 완화하는 원단은 주변 농촌 지역보다 8.9°C나 더 높아질 수 있는 도시 지역의 기온에 대처하며, 해당 수요를 확대되고 있습니다. 각 브랜드가 아시아태평양의 제조 클러스터를 활용함으로써 개발 주기를 단축하고 단가를 절감하고 있어, 일반 소비자들도 고품질의 냉각 기능을 합리적인 가격에 이용할 수 있게 되었습니다. 3D 프린팅 구조와 공기역학적 패널을 결합한 제품을 단계적으로 출시하는 움직임은 엘리트 스포츠 부문의 노하우가 라이프스타일 의류에 적용되고 있음을 보여주며, 이를 통해 쿨링 패브릭 시장이 확대되고 있습니다. 대륙을 초월한 기술 이전이 전 세계적인 보급을 더욱 가속화하고 있습니다.
고성능 쿨링 패브릭의 높은 생산 비용
수동 방열층에는 이산화티타늄 나노 입자, 고분자 막, 은 나노와이어가 필요하며, 이는 일반 의류에 비해 원자재 비용을 상승시킵니다. 전용 코팅 라인에는 설비 투자가 필요하며, 엄격한 품질 관리 프로토콜로 인해 노동 집약도도 높아집니다. 공정 최적화를 통해 추가 비용은 10% 가까이 절감되었지만, 저소득 지역에서는 여전히 높은 가격에 놀라워하는 경우가 많아 판매량 증가세가 둔화되고 있습니다. 공급업체는 대중용 가격대에 도달하기 위해 연속 롤 성막 기술을 정교화하고 원료 선택의 폭을 넓혀야 합니다. 규모 확대가 정체되어 있기는 하지만, 방위, 프로 스포츠, 산업용 개인보호구(PPE)(PPE) 등의 프리미엄 부문에서는 비용이 상쇄되어 연구 개발(R&D) 비용의 상각이 가능해졌습니다. 이를 통해 궁극적으로는 가치 부문에도 그 효과가 파급될 것입니다.
부문 분석
합성 섬유는 균일한 흡습·발산성과 신축성을 대규모로 구현함으로써 2025년 쿨링 패브릭 시장에서 60.45%의 점유율을 유지했습니다. 이러한 기술은 대량 생산되는 스포츠웨어에서 여전히 비용 면에서 최적의 선택인, 다수의 특허를 취득한 쿨링 화학 기술을 뒷받침하고 있습니다. 한편, 규제 당국과 소비자가 생분해성을 중시하는 가운데, 천연섬유는 연평균 성장률(CAGR) 8.03%의 성장 궤도에 올라 있습니다. 나노 다이아몬드와 키토산을 통해 미세 다공성을 부여한 면은 현재 2-3°C의 온도 저하를 실현하고 있으며, 한편 폐쇄형 루프 구조의 큐프로 원사는 식물 유래 원료와 산업용 재활용 가능성을 모두 충족시키고 있습니다. 혼방 구조에서는 재생 셀룰로오스와 미세 광물계 합성 섬유를 조합하여 촉감과 기능의 균형을 맞추고 있습니다. 따라서 투자자들은 천연섬유의 품질을 향상시키는 탈피기(진)의 업그레이드와 효소를 이용한 전처리에 자금을 지원하고 있으며, 이는 쿨링 패브릭 시장에서 더 광범위한 수용을 예고하고 있습니다.
하이브리드 원사의 발전은 지속가능성 목표와 성능 지표가 반드시 상충되는 것은 아니라는 점을 보여줍니다. 벤베르그 큐프로는 99%가 넘는 용매 회수율을 자랑하며, 방열 능력을 희생하지 않고도 순환성을 구현하고 있습니다. 또한, 파일럿 테스트에서 재생 면은 내열성 면에서도 버진 면을 능가하는 성능을 보여주었습니다. 패션 그룹들이 과학에 기반한 탄소 배출 감축 목표를 발표함에 따라, 조달 활동은 환경 부하가 낮은 선택지로 전환되고 있으며, 환경에 대한 배려가 측정 가능한 수요로 이어지고 있습니다. 예측 기간 동안 천연섬유로 만든 냉각 제품 라인은 점유율을 서서히 확대할 것으로 보이지만, 속건성 및 신축성이 중요한 의류 부문에서는 합성 섬유가 여전히 중심적인 역할을 계속할 것으로 보입니다.
직물은 2025년 매출의 40.12%를 차지했으며, 연평균 성장률(CAGR) 8.25%로 성장하고 있습니다. 이는 정밀하게 제어된 직조 구조가 나노 입자 코팅, 반사 필름, 상변화 프린트 페이스트를 위한 치수 안정성이 높은 기판을 제공하기 때문입니다. 직물 공장은 이미 높은 처리량으로 가동되고 있어, 냉각 기능을 추가할 때 발생하는 추가 비용을 최소화할 수 있습니다. 니트 원단은 편안한 신축성과 통기성 덕분에 액티브웨어 부문에서 확고한 입지를 유지하고 있지만, 루프 구조로 인해 더 저속의 기계가 필요하며, 다층 코팅을 복잡하게 만들 가능성이 있습니다. 부직포는 촉감이나 드레이프성이 부차적인 요소가 되는 일회용 의료용품 및 여과 틈새 시장에서 그 중요성이 커지고 있습니다.
공정 혁신을 통해 직물의 생산성은 지속적으로 향상되고 있으며, 워터젯 직기는 에너지 절약을 실현하면서 더 얇은 데니어의 원단을 생산하고 있습니다. 다상 직조는 미세 구멍의 형태를 조정하여 수증기 이동을 촉진합니다. 한편, 편직기도 디지털 제어와 더 미세한 게이지(gauge)를 채택하고 있어 표면 균일성 면에서의 차이는 점차 줄어들고 있습니다. 니트나 직물에 적층된 일렉트로스피닝 막은 초박형 방열층을 추가하여, 각 구조의 장점을 융합한 하이브리드 적층 소재를 만들어내고 있습니다. 비용 측면과 범용성의 이점으로 인해 쿨링 패브릭 시장에서는 직물이 계속해서 주도적인 위치를 유지할 것으로 보이지만, 신축성에 대한 소비자 수요가 증가함에 따라 니트 제품의 점유율은 감소하지 않고 안정적인 수준을 유지할 것으로 예측됩니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 31.05%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 7.63%로 성장하고 있습니다. 이는 중국의 테크니컬 텍스타일 수출 규모와 의류를 5°C 냉각시키는 수동적 복사 냉각 기술 연구 분야의 리더십에 힘입은 것입니다. 정부의 보조금을 통해 메타패브릭 시범 공장이 지원되는 한편, 베트남, 인도네시아, 인도의 하류 의류 제조업체들은 이러한 섬유를 비용 경쟁력이 있는 재단 및 봉제 라인에 통합하고 있습니다. 일본의 재료 과학 생태계는 자외선(UV) 반사용 폴리머 혼합물을 개선하고 있으며, 한국의 전자 산업은 체온 데이터를 모바일 기기로 전송하는 스마트 텍스타일 오버레이 개발을 추진하고 있습니다. 습도가 높은 여름을 맞이하는 중산층 인구 증가가 소매 수요를 더욱 높이고 있습니다.
북미에서는 국방 관련 계약과 아웃도어 레크리에이션 문화가 호재로 작용하고 있습니다. 미국 해군용 항공 시스템국의 프로그램을 통해 공급업체의 학습 곡선이 가속화되고 있으며, 내환경성이 뛰어난 쿨링 패브릭의 실용성이 입증되고 있습니다. 오리건주와 콜로라도주에 본사를 둔 아웃도어 브랜드들은 매년 여름 신제품 컬렉션을 발표하며, 소비자들의 꾸준한 수용을 뒷받침하고 있습니다. 캐나다의 극심한 기온 변동을 배경으로, 한쪽 면에는 냉각 기능, 다른 쪽 면에는 단열 기능을 갖춘 사계절용 레이어링 컨셉이 등장하며 제품의 실용성이 확대되고 있습니다. 멕시코는 근해 봉제 거점으로서의 역할을 확대하고 있어, 전 세계적인 물류 혼란 속에서도 브랜드에 유연성을 제공합니다.
유럽의 동향은 환경 정책과 밀접하게 연관되어 있습니다. 유럽연합(EU)의 에코디자인 규제는 섬유 제품을 우선 대상으로 삼고 있으며, 밸류체인의 추적 가능성과 재생 소재 사용을 의무화하고 있습니다. Outlast와 같은 독일 방적 제조업체는 NASA에서 개발된 상변화 물질(PCM) 처리를 친환경 인증을 받은 안감에 적용하고 있는 반면, 이탈리아의 방적 제조업체는 재활용 원사를 활용한 환경 부하가 낮은 염색 기술을 추진하고 있습니다. 영국(UK)의 연구평의회는 나노 구조의 복사 필름에 초점을 맞춘 산학 컨소시엄에 자금을 지원하고 있습니다. 이 지역의 에너지 비용 급등은 수동형 개인용 냉각에 대한 수요를 높이고 있으며, 높은 가격에도 불구하고 국내 보급을 촉진하고 있습니다.
남미, 중동 및 아프리카에서는 급속한 도시화와 강한 일사량으로 인해 새로운 비즈니스 기회가 창출되고 있습니다. 브라질의 스포츠웨어 붐은 상변화 물질을 배합한 폴리에스터 섬유의 현지 조달을 촉진하고 있으며, 걸프 국가에서는 낮 기온이 45°C에 달하는 환경에서 작업하는 건설 노동자를 위한 냉각 유니폼의 시범 도입이 이루어지고 있습니다. 인프라 미비 및 가처분 소득의 제한으로 인해 단기적인 물량은 억제되고 있지만, 지속적인 기후 온난화로 인해 장기적인 성장 기회가 예상됩니다. 전 세계 공급업체들은 관세 및 물류상의 장벽을 극복하기 위해 현지 파트너와의 합작 투자 및 기술 라이선싱에 주목하고 있으며, 이를 통해 쿨링 패브릭 시장이 더 광범위한 지역적 균형을 실현할 것으로 기대됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, cooling fabrics market size in 2026 is estimated at USD 2.77 billion, growing from 2025 value of USD 2.59 billion with 2031 projections showing USD 3.92 billion, growing at 7.13% CAGR over 2026-2031.
This report is Segmented by Fiber Type (Natural and Synthetic), Fabric Construction (Woven, Knitted, and Non-Woven), Application (Sportswear, Protective Wear, and More), End-User Industry (Consumer, Industrial and Manufacturing, Healthcare, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Cooling Fabrics Market Trends and Insights
Surge in Synthetic Moisture-wicking Fibers for Sports and Athleisure
Athleisure and performance sportswear now treat dynamic cooling as a baseline expectation. Brands integrate COOLMAX EcoMade, brrr° and comparable yarns that embed phase-change materials or micro-minerals, providing continuous heat draw-down even under heavy perspiration . Market penetration benefits from global participation in fitness and outdoor recreation, and synthetic fibers retain dominance because they deliver repeatable moisture transport, stretch and mechanical durability. Technical-textile advances lift synthetic yarns' share of global fiber demand above 19%, reinforcing scale economies that underpin the cooling fabrics market. With nanohybrid fillers improving thermal conductivity, engineered synthetics outperform many natural alternatives. In parallel, recycled Polyethylene Terephthalate (PET) streams keep cost bases stable while satisfying tightening eco-design rules.
Expansion of Outdoor and Performance Apparel Brands Globally
Multinational outdoor labels channel proprietary cooling platforms into both back-country and everyday urban lines. Columbia Sportswear's Omni-Heat Infinity and Omni-Shade technologies exemplify such crossover. Heat-mitigating fabrics combat city temperatures that can sit 8.9°C higher than surrounding rural zones, broadening addressable demand. As brands leverage Asia-Pacific manufacturing clusters, they shorten development cycles and lower per-unit costs, making premium cooling attainable for mainstream consumers. Iterative launches that combine 3D-printed structures with aerodynamic panels demonstrate a migration of elite-sport learnings to lifestyle garments, thus enlarging the cooling fabrics market. Technology transfer across hemispheres further accelerates global uptake.
High Production Cost of Advanced Cooling Textiles
Passive-radiative layers call for titanium dioxide nanoparticles, polymer membranes and silver nanowires that elevate bill-of-materials costs relative to commodity apparel. Specialized coating lines introduce capital outlays, while stringent quality-control protocols add labor intensity. Although process optimization has trimmed the premium to almost 10%, sticker shock persists in lower-income regions, slowing volume. Suppliers must refine continuous-roll deposition and broaden raw-material options to reach mass-price points. Scaling pauses notwithstanding, premium categories such as defense, professional sports and industrial Personal Protective Equipment (PPE) absorb the cost, allowing research and development (R&D) amortization that should eventually spill into value segments.
Other drivers and restraints analyzed in the detailed report include:
- Breakthrough Passive Radiative "Metafabrics" for Urban Heat Mitigation
- Military Procurement of Heat-stress Uniforms for Desert Operations
- Performance Degradation After Repeated Laundering Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Synthetic yarns retained 60.45% of cooling fabrics market share in 2025 by delivering uniform moisture transport and stretch at scale. They underpin many patented cooling chemistries that remain cost-optimal for high-volume sportswear. Natural fibers, though, are on an 8.03% CAGR path as regulators and consumers prize biodegradability. Cotton modified with nanodiamonds or chitosan micro-porosity now attains 2-3°C temperature drops, while closed-loop cupro yarns marry plant-based feedstocks with industrial recyclability. Blended constructions pair regenerated cellulose with micro-mineral synthetics, balancing feel and function. Investors therefore finance gin upgrades and enzymatic pre-treatments that elevate natural fiber quality, pointing to broader acceptance within the cooling fabrics market.
Hybrid yarn advances demonstrate that sustainability targets and performance metrics need not be mutually exclusive. Bemberg cupro showcases solvent recovery rates exceeding 99%, illustrating circularity without sacrificing heat-dissipation capacity. Recycled cotton streams also outperform virgin cotton on thermal resistance in pilot trials. As fashion groups publish science-based carbon goals, procurement pivots toward these lower-impact options, translating eco-preference into measurable demand. Over the forecast horizon, natural-fiber cooling lines will likely take incremental share, though synthetics will remain central to rapid-wicking and stretch-critical apparel tiers.
Woven fabrics supplied 40.12% of 2025 revenue and are growing at an 8.25% CAGR because their tightly-controlled interlacings provide dimensionally stable substrates for nanoparticle coatings, reflective films and phase-change print pastes. Weaving plants already operate at high throughput, minimizing incremental cost to add cooling capability. Knits retain strong footholds in activewear thanks to comfort stretch and breathability, yet their looped structure demands slower machinery and can complicate multilayer coatings. Non-wovens gain relevance in disposable medical or filtration niches where tactile drape is secondary.
Process innovation continues to lift woven productivity, with water-jet looms delivering finer deniers while conserving energy. Multi-phase weaves adjust pore geometry, aiding moisture vapor transport. At the same time, knitting equipment adopts digital control and finer gauges, narrowing the gap in surface regularity. Electrospun membranes layered onto knits or wovens add ultra-thin emissive skins, creating hybrid laminates that fuse each construction's strengths. Cost and versatility advantages suggest woven textiles will retain top billing in the cooling fabrics market, but rising consumer appetite for stretch will keep knitted shares steady rather than declining.
Complete Report Scope:
- By Fiber Type
- Natural
- Synthetic
- By Fabric Construction
- Woven
- Knitted
- Non-woven
- By Application
- Sportswear
- Protective Wear
- Apparels
- Other Applications (Medical and Healthcare Textiles, etc.)
- By End-user Industry
- Consumer
- Industrial and Manufacturing
- Defense and Security
- Healthcare
- Automotive and Transportation
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 31.05% of global revenue in 2025 and is moving at a 7.63% CAGR through 2031, anchored by China's scale in technical-textile exports and its leadership in passive-radiative research that delivers 5°C garment cooling. Government grants support pilot plants for metafabric yardage, while downstream apparel makers in Vietnam, Indonesia, and India integrate these textiles into cost-competitive cut-and-sew lines. Japan's material-science ecosystem refines polymer blends for Ultraviolet (UV) reflection, and South Korea's electronics sector pursues smart-textile overlays that feed body-temperature data to mobile devices. Rising middle-class populations confronting humid summers amplify retail pull.
North America benefits from defense contracts and an outdoor recreation culture. US Naval Air Systems programs accelerate supplier learning curves and validate ruggedized cooling fabrics. Outdoor labels headquartered in Oregon and Colorado roll new collections each summer, driving steady consumer uptake. Canada's severe temperature swings prompt multi-season layering concepts that embed cooling on one face and insulation on the other, stretching product utility. Mexico expands role as a near-shore sewing destination, giving brands flexibility amid global logistics disruptions.
Europe's trajectory intertwines with environmental policy. The European Union (EU) Ecodesign regulation prioritizes textiles, compelling value-chain traceability and recyclate usage. German mills like Outlast adapt NASA-born Phase Change Material (PCM) treatments into eco-certified linings, while Italian spinners push low-impact dyeing of recycled yarns. The United Kingdom (UK) research councils fund university-industry consortia focused on nanostructured emissive films. Higher energy costs in the region reinforce demand for passive personal cooling, stimulating domestic uptake despite premium pricing.
South America and the Middle East & Africa present emerging opportunities tied to rapid urbanization and intense solar exposure. Brazil's athletic-wear boom spurs local sourcing of phase-change infused polyester, and Gulf states test cooling uniforms for construction crews working in 45°C midday heat. Infrastructure gaps and limited disposable income temper near-term volumes, yet sustained climate warming suggests long-run growth. Global suppliers eye joint ventures and technology-licensing to local partners to overcome tariff and logistics hurdles, ensuring the cooling fabrics market achieves broader geographic balance.
- Ahlstrom
- Asahi Kasei Advance Corporation
- Balavigna Mills Pvt. Ltd.
- brrr°
- Cocona Labs
- Columbia Sportswear Company
- Coolcore
- Elevate Textiles, Inc.
- Everest Textile Co., Ltd.
- FORMOSA TAFFETA CO., LTD.
- HeiQ Materials AG
- LunaMicro AB
- Milliken & Company
- NAN YA PLASTICS CORPORATION
- NILIT
- Outlast Technologies GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Synthetic Moisture-wicking Fibers for Sports and Athleisure
- 4.2.2 Expansion of Outdoor and Performance Apparel Brands Globally
- 4.2.3 Breakthrough Passive Radiative "Metafabrics" for Urban Heat Mitigation
- 4.2.4 Military Procurement of Heat-stress Uniforms for Desert Operations
- 4.2.5 Sustainability Mandates Accelerating Recycled Cooling Fibers Adoption
- 4.3 Market Restraints
- 4.3.1 High Production Cost of Advanced Cooling Textiles
- 4.3.2 Performance Degradation After Repeated Laundering Cycles
- 4.3.3 Dye-uptake Limitations on High-reflectance Radiative Fabrics
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Fiber Type
- 5.1.1 Natural
- 5.1.2 Synthetic
- 5.2 By Fabric Construction
- 5.2.1 Woven
- 5.2.2 Knitted
- 5.2.3 Non-woven
- 5.3 By Application
- 5.3.1 Sportswear
- 5.3.2 Protective Wear
- 5.3.3 Apparels
- 5.3.4 Other Applications (Medical and Healthcare Textiles, etc.)
- 5.4 By End-user Industry
- 5.4.1 Consumer
- 5.4.2 Industrial and Manufacturing
- 5.4.3 Defense and Security
- 5.4.4 Healthcare
- 5.4.5 Automotive and Transportation
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 NORDIC Countries
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Ahlstrom
- 6.4.2 Asahi Kasei Advance Corporation
- 6.4.3 Balavigna Mills Pvt. Ltd.
- 6.4.4 brrr°
- 6.4.5 Cocona Labs
- 6.4.6 Columbia Sportswear Company
- 6.4.7 Coolcore
- 6.4.8 Elevate Textiles, Inc.
- 6.4.9 Everest Textile Co., Ltd.
- 6.4.10 FORMOSA TAFFETA CO., LTD.
- 6.4.11 HeiQ Materials AG
- 6.4.12 LunaMicro AB
- 6.4.13 Milliken & Company
- 6.4.14 NAN YA PLASTICS CORPORATION
- 6.4.15 NILIT
- 6.4.16 Outlast Technologies GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Cooling Fabric with Chalk-based Coating